ICHRA in Brunswick, Georgia 2026: Glynn County 49.2%
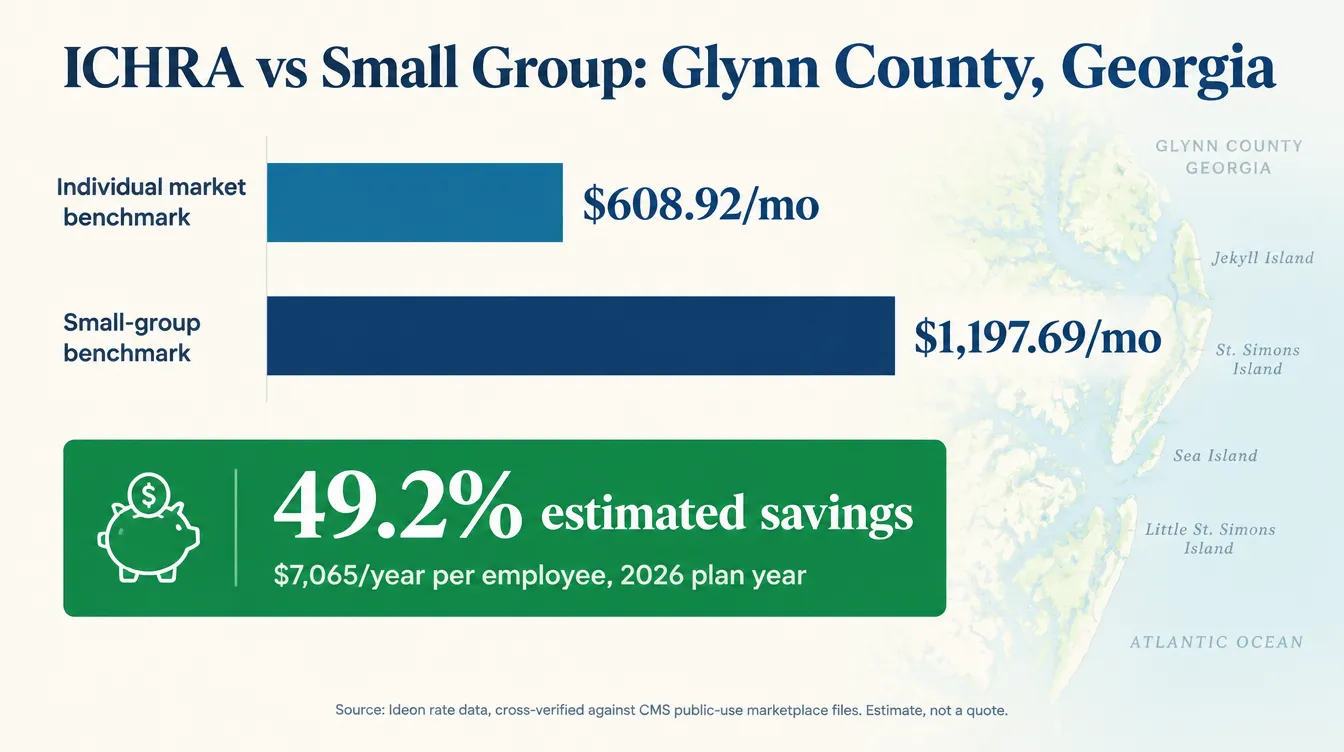
Glynn County's 2026 benchmark runs an estimated 49.2% below small group, about $7,065 a year per employee. See the sourced data for Brunswick.
The short version
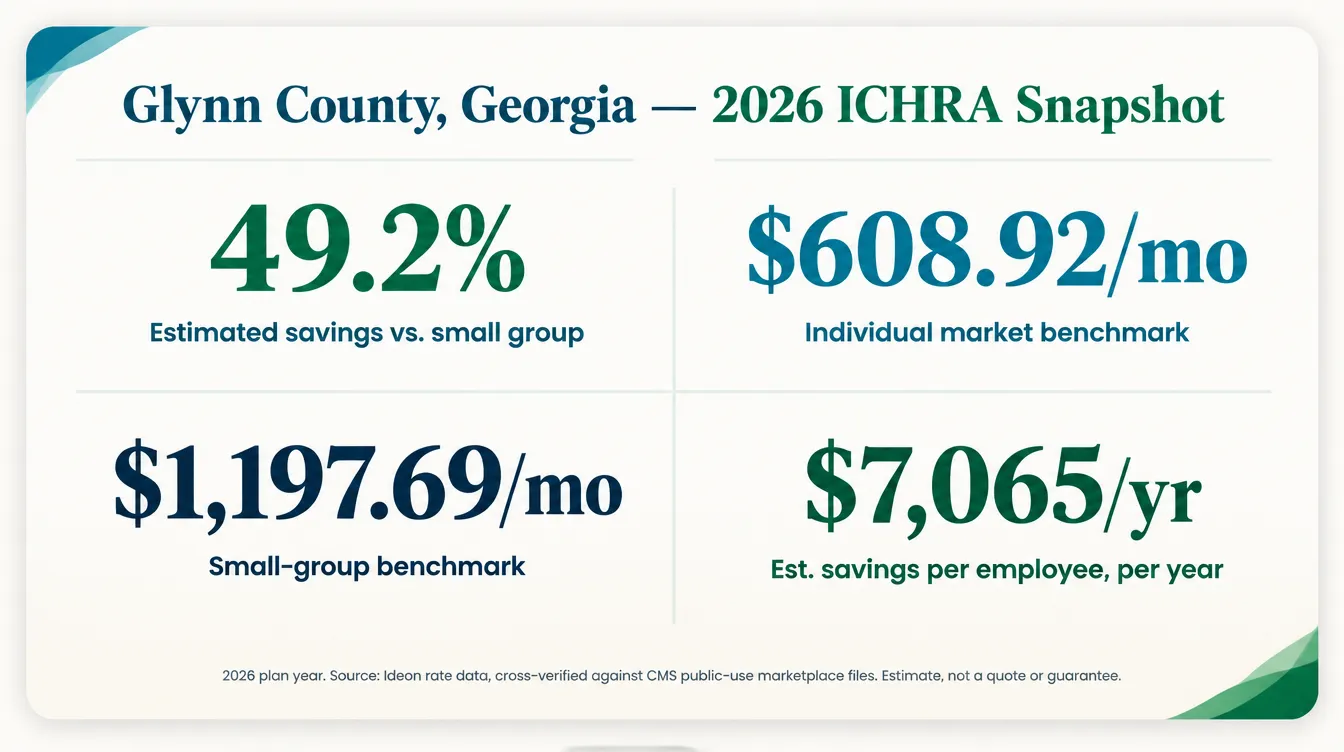
- Glynn County's 2026 individual-market benchmark runs an estimated 49.2% below the small-group benchmark, about $7,065 per employee per year — well above Georgia's statewide average of 37.2% across all 158 counties.
- Glynn shares its exact benchmark numbers with Camden, McIntosh, Wayne, Brantley, Pierce, Charlton and Ware counties, because Georgia prices these benchmarks by rating area, not by county — a real mechanic explained below, not a coincidence.
- Accommodation and food services alone employs 7,740 people across 410 Glynn-area firms, per the Georgia Department of Labor's Brunswick MSA profile (Q1 2026) — 16.1% of all covered jobs in a three-county area of 48,097 jobs.
- Per the same profile, 2,403 of the area's 3,868 covered establishments employ 0 to 4 people, and another 617 employ 5 to 9 — a workforce dominated by very small, often seasonal employers, exactly the group a group-insurance participation floor is hardest on.
- Georgia caps small-group participation requirements at 75% for groups of 4 to 50 — real relief compared to states with no cap, but still enough to sink a policy for a seasonal restaurant, inn or shop with part-time and rotating staff.
- Qualifying is not the same as guaranteed savings for your business. The honest limits are covered later, including where this comparison breaks down for a specific workforce.
Does ICHRA beat small group in Brunswick, Georgia?
Yes, and by one of the widest margins in the state. An ICHRA (Individual Coverage Health Reimbursement Arrangement) is an IRS-defined arrangement that lets an employer set a fixed monthly reimbursement amount and let each employee buy their own individual-market plan with it, tax-free. In Glynn County, the Georgia county that contains Brunswick, St. Simons Island, Sea Island and Jekyll Island, the 2026 individual-market benchmark premium runs an estimated 49.2% below the small-group benchmark premium, according to a county-by-county comparison built from Ideon rate data and cross-verified against CMS public-use marketplace files.
That 49.2% ranks 55 out of Georgia's 158 counties by percentage, and it sits well above the statewide average of 37.2%, far above what metro Atlanta shows for 2026 (Fulton County runs just 11.5%). Brunswick and the Golden Isles run on a genuinely distinct economy from the rest of coastal Georgia: a deepwater port, a regional hospital system, and — dominating the job count — tourism. That combination, a real rate spread plus an employer base stacked with small, seasonal businesses that group insurance underwrites badly, is what makes Glynn County worth its own guide rather than a line in a statewide roundup.
Of the 1,309 counties nationwide in our dataset, 158 are in Georgia, and 131 of them clear the $100-a-month gap we use as the floor for calling a county "qualifying" at all. Glynn clears it comfortably, at $ 588.77 a month. The question that matters for a Glynn County employer isn't whether the county "qualifies" in the abstract, it's what this specific gap is worth to a specific, often seasonal headcount, and whether it solves the actual problem a Golden Isles employer runs into with group coverage. That's what the rest of this guide works through.
49.2%
Estimated Glynn County savings vs. small group
55/158
Glynn's rank by percentage among Georgia counties
85K
Glynn County residents
$7,065
Est. Glynn County savings per employee, per year
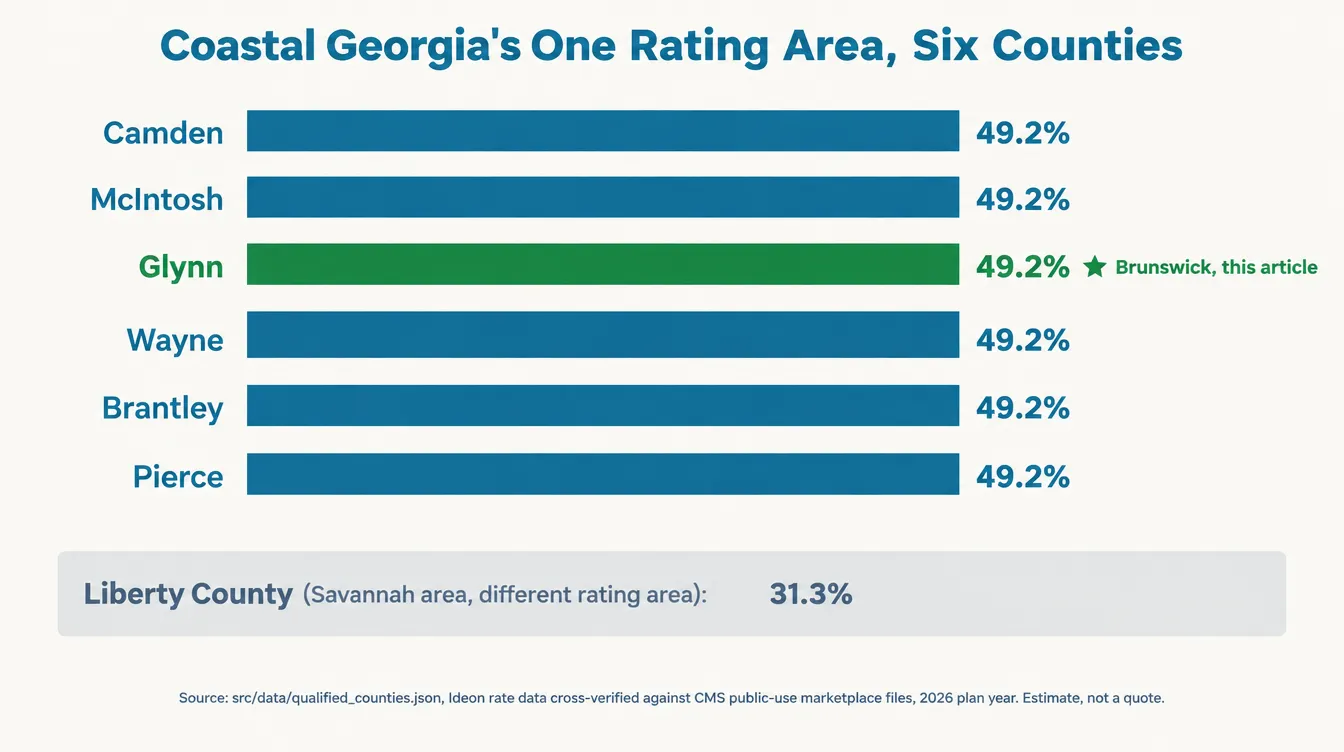
Why Glynn, Camden, McIntosh, Wayne, Brantley and Pierce share the exact same number
Look closely at the numbers behind this article and you'll notice something that looks like a typo but isn't: Glynn County's individual benchmark ($608.92), small-group benchmark ($1197.69), and 49.2% savings figure are identical, to the cent, to Camden, McIntosh, Wayne, Brantley and Pierce counties, plus Charlton and Ware counties farther inland. That's not a coincidence and it's not our dataset repeating a number by mistake.
The ACA marketplace and small-group insurance markets don't price coverage county by county. They price it by rating area, a set of geographic zones each state defines (subject to federal rules) that carriers use to file one set of benchmark rates covering every county inside that zone. Georgia's insurance regulators grouped Glynn, Camden, McIntosh, Wayne, Brantley, Pierce, Charlton and Ware counties into the same Southeast Georgia rating area for 2026, so any carrier filing a plan in that zone filed one price, not eight. A Brunswick employer and an employer in St. Marys (Camden County) or Jesup (Wayne County) are looking at the exact same underlying math, even though they sit in different counties and, in some cases, serve entirely different local economies — port and logistics in Camden, timber and agriculture in Wayne, tourism in Glynn.
Here's why that matters practically: if you're a Glynn County employer and a broker quotes you a small-group renewal that looks meaningfully different from the $1197.69 benchmark used here, ask whether that's a plan-design difference (richer benefits, a different metal tier) or a genuine rating-area mismatch, because it shouldn't be the latter. And if your business has locations or seasonal staff split across this rating area's eight counties, the ICHRA math doesn't get more complicated the way a multi-county group quote sometimes does, since the benchmark comparison is identical across all eight.
| County (city) | Population | Individual benchmark | Small-group benchmark | Savings vs. small group |
|---|---|---|---|---|
| Camden County | 55K | $608.92 | $1197.69 | 49.2% |
| McIntosh County | 11K | $608.92 | $1197.69 | 49.2% |
| Glynn County | 85K | $608.92 | $1197.69 | 49.2% |
| Wayne County | 30K | $608.92 | $1197.69 | 49.2% |
| Brantley County | 18K | $608.92 | $1197.69 | 49.2% |
| Pierce County | 20K | $608.92 | $1197.69 | 49.2% |
Source: src/data/qualified_counties.json, 2026 plan year (Ideon rate data,
cross-verified against CMS public-use marketplace files). Estimates, not quotes.
One rating area away, the answer drops
Liberty County, part of the Savannah-area rating area rather than Glynn's, shows only 31.3% for 2026 — a real, sourced number from the same dataset, not a rounding difference. Chatham County (Savannah itself, covered in our Savannah ICHRA guide) shows the same 31.3%. "Coastal Georgia" is not one ICHRA answer; it's 131 distinct county answers layered on top of a smaller number of distinct rating-area prices. Check your own county before assuming Glynn's number applies to you, even if you're only an hour up the coast.
How Georgia's 158 counties break down by savings tier
Number of counties in each savings band, 2026 plan year. Source: Ideon rate data, cross-verified against CMS public-use files.
Glynn sits in the 45-55% band, well above the statewide average and well clear of Georgia's many near-zero-percent metro counties. Illustrative and rounded; not an offer of insurance or a guarantee of savings.
Brunswick and the Golden Isles' seasonal economy, in the numbers
Glynn County doesn't run on one dominant employer the way some qualifying counties do; it runs on tourism, split across a large number of small operators. Per the U.S. Bureau of Labor Statistics' Quarterly Census of Employment and Wages (QCEW) for Glynn County (area code 13127), 2025 annual averages, the county's private-sector employers reported 3,258 establishments employing 35,763 people at an average annual pay of $52,838. Within that total, Accommodation and Food Services (NAICS 72) alone accounted for 370 establishments and 7,527 jobs — more than a fifth of all private employment in the county — at a considerably lower average annual pay of $32,888. Arts, Entertainment, and Recreation (NAICS 71) added another 79 establishments and 1,338 jobs.
The Georgia Department of Labor's Brunswick, GA Metropolitan Statistical Area profile (covering Glynn, Brantley and McIntosh counties together, updated September 2026) tells the same story at the regional level: for the first quarter of 2026, Accommodation and Food Services was the area's single largest industry by employment, with 410 firms and 7,740 jobs, 16.1% of all covered employment, at an average weekly wage of just $642 — the lowest of any major industry in the profile. Health Care and Social Assistance was close behind at 7,173 jobs across 358 firms, anchored by Southeast Georgia Health System (listed in Georgia Department of Labor records under its former name, Glynn-Brunswick Memorial Hospital). The same profile's establishment size-class table shows 2,403 of the area's 3,868 covered establishments employ 0 to 4 people, and another 617 employ 5 to 9 — together, more than three-quarters of all establishments in the area. This is a small-business economy, not a big-employer one.
| Sector | Establishments | Employment | Avg. annual pay |
|---|---|---|---|
| All private industry | 3,258 | 35,763 | $52,838 |
| Accommodation and food services (NAICS 72) | 370 | 7,527 | $32,888 |
| Health care and social assistance (NAICS 62) | 335 | 6,794 | $68,490 |
| Arts, entertainment and recreation (NAICS 71) | 79 | 1,338 | $38,930 |
Source: U.S. Bureau of Labor Statistics, Quarterly Census of Employment and Wages, Glynn County, Georgia (area code 13127), 2025 annual averages.
A port economy sits underneath the tourism story
Glynn County isn't only beach towns. The Port of Brunswick has been "the No. 1 gateway in the nation for auto and heavy machinery" for the past two years, per the Georgia Ports Authority, with more than 20 major auto manufacturers and four auto processors operating at its Colonels Island Terminal. That adds a logistics and manufacturing layer on top of the tourism economy, but it doesn't change the underlying pattern: per the Georgia Department of Labor's regional profile, the county's top employers by name include Southeast Georgia's health system, Sea Island's resort operations, International Auto Processing, Rich Products and Walmart alongside a long tail of small shops, restaurants and inns.
Why a seasonal, small-business workforce breaks group insurance math
Group health insurance was built around a stable headcount: the same employees, enrolled once a year, staying enrolled all year. A tourism-driven economy like Glynn County's doesn't work that way. A restaurant on St. Simons Island might run a skeleton crew in January and triple its staff by June. A Jekyll Island retail shop might rely on college students home for the summer. An inn might keep two full-time managers and a rotating cast of part-time housekeeping and front-desk staff who turn over every season. None of that is unusual for a $32,888-average-pay, 370-establishment industry — it's the normal shape of hospitality employment, and the Georgia Department of Labor's own data confirms it's the largest single employment category in the county.
A group health plan penalizes exactly that shape of workforce. Carriers price a group policy assuming a knowable, relatively stable pool of enrollees, and they protect that pricing with a participation requirement — a minimum share of eligible employees who must actually enroll before the carrier will issue the policy. A seasonal business with rotating part-time staff, employees covered through a spouse's plan, and new hires still inside a waiting period is structurally likely to miss that bar, even when every employee technically has coverage somewhere. It's not that hospitality employers don't want to offer a benefit; it's that the group-insurance underwriting model assumes a workforce most tourism businesses don't have.
This is the pain point this guide is written for: an owner who has looked at group coverage, run into the participation math or the price, and concluded there's nothing realistic to offer — when in fact the individual market in Glynn County is priced low enough, relative to small group, that a modest fixed monthly contribution goes a long way, without requiring the employer to hit any participation threshold at all.
See the full Georgia savings breakdown for every qualifying county, the national savings map to look up a specific county by name, or the statewide Georgia ICHRA guide for how Glynn County's number fits into the bigger picture.
Brunswick isn't a hard county to make the case for. The rate spread is wide and the workforce is exactly the kind that group insurance underwrites worst: small, seasonal, and part-time by design.
Mike MooreHow an ICHRA (now also called CHOICE) actually works
Before the Glynn County numbers mean anything, it helps to be precise about what's being compared.
An ICHRA is an employer-funded health reimbursement arrangement created by a 2019 final rule from the IRS and Treasury, the Department of Labor, and HHS, published at 84 Fed. Reg. 28888 on June 20, 2019, applicable to plan years beginning on or after January 1, 2020. Instead of choosing one group health plan for everyone, the employer sets a fixed monthly reimbursement amount, and each employee uses that money to buy an individual-market plan of their own choosing, then submits proof of coverage (called substantiation) to get reimbursed tax-free. The employer isn't picking a plan for dozens of households with different doctors, different needs and, in Glynn County's case, wildly different work schedules across the year; the employer is funding a budget, and the employee is doing the shopping.
Worth naming directly: as of this article's publish date, HealthCare.gov's own page on this arrangement is titled "CHOICE Arrangements," and states plainly that CHOICE Arrangements are "formerly known as the Individual Coverage Health Reimbursement Arrangements, or ICHRAs." That's an administrative renaming on federal consumer-facing pages, not a change to the 2019 final rule or to any compliance requirement described in this article. We use "ICHRA" throughout this site, since that's still the term used in the regulations themselves.
The comparison behind every number in this article rests on two specific prices for a given rating area. The individual-market benchmark premium is the second-lowest-cost silver-level plan available in that rating area to a representative 40-year-old enrollee. "Silver" is one of four ACA metal levels (bronze, silver, gold, platinum) describing how costs split between premium and out-of-pocket spending, not the quality of care. This is the same benchmark the federal government uses to calculate premium tax credits, which is why it's a defensible number to build a comparison on rather than one insurer's list price. The small-group benchmark premium is the equivalent figure built from comparable small-group plan filings for that same rating area. When the individual benchmark is lower, the county "qualifies," and the gap between the two is the estimated per-employee savings if the employer funds ICHRA at that benchmark level.
Two more terms matter once an employer is actually deciding whether to switch. The affordability safe harbor is the test that decides whether the ICHRA offer counts as "affordable" under IRS rules — for plan years beginning in 2026 that test runs against a Required Contribution Percentage of 9.96% of household income (IRS Rev. Proc. 2025-25), rising to 10.22% for plan years beginning in 2027 (IRS Rev. Proc. 2026-26). Get the contribution amount wrong relative to that threshold and an ALE (applicable large employer, generally 50 or more full-time-equivalent employees) can trigger an employer-mandate penalty. Most Glynn County hospitality and retail operators, running under 50 employees, sit well under that threshold, though a larger resort operation may not.
Glynn County's rate spread, in dollars
Here is the actual 2026 benchmark comparison for Glynn County, the county that contains Brunswick, St. Simons Island, Sea Island and Jekyll Island. The individual-market benchmark premium is $608.92 a month. The small-group benchmark premium, built from comparable small-group plan filings for the same rating area, is $1197.69 a month. That's a gap of $588.77 a month, or $7,065 a year, per employee, an estimated 49.2% in favor of the individual market.
Put next to the rest of coastal Georgia, Glynn's number is the shared rating-area figure for Camden, McIntosh, Wayne, Brantley and Pierce counties as well, while Liberty County (the Fort Stewart and Hinesville area, closer to Savannah) sits in a different rating area at only 31.3%. Chatham County (Savannah) shows the identical 31.3%. Metro Atlanta is a different story entirely: Fulton County shows just 11.5%. Glynn County's gap is real, sourced, and among the widest in the state, but it is not universal even within a two-hour drive up the coast.
Georgia's group participation rule, and why it still bites in a tourism economy
Small-group health insurance isn't sold to individual employees one at a time; it's underwritten as a pool, and a carrier can require a minimum share of a company's eligible employees to actually enroll before it will issue the policy at all. Georgia regulates that authority more tightly than some states: under Ga. Comp. R. & Regs. R. 120-2-10-.12(9)(b), a small-group carrier cannot require more than 100% of eligible employees to participate for groups of three or fewer, and cannot require more than 75% of eligible employees for groups of four to fifty. That's a real cap, not a suggestion, and it's more employer-protective than a rule that simply lets carriers set their own bar with no ceiling.
Even a capped 75% requirement still bites hard for a Golden Isles hospitality business. A 16-person restaurant with a summer-only prep cook, two servers still in a 90-day new-hire waiting period, and a bartender covered through a spouse's employer plan can fail that 75% mark even though every one of those employees technically has coverage somewhere. That isn't a hypothetical extreme; per the Georgia Department of Labor's own data above, the average covered establishment in the accommodation-and-food-services category runs about 20 employees (7,740 jobs across 410 firms), and that average hides plenty of operations running smaller and leaner, exactly where a firm participation floor is easiest to miss.
An ICHRA (or CHOICE Arrangement, per HealthCare.gov's current naming) sidesteps the mechanic entirely when it's the only benefit offered. Per HealthCare.gov, there is no participation-percentage requirement at all in that case. A minimum class size only applies when an employer offers a CHOICE Arrangement to one employee class while also offering a traditional group plan to a different class: 10 employees for employers with fewer than 100 total employees, 10% of the total workforce for employers with 100 to 200 employees, and 20 employees for employers with more than 200. Those class-size rules exist to keep the two benefit types properly separated when both are in use; they don't apply at all to an employer offering only a CHOICE Arrangement, which describes most Glynn County small businesses.
If a group quote already fell through on participation
If you've already tried to set up small-group coverage in Glynn County and couldn't clear a carrier's 75% participation floor, that's a specific, common signal that an ICHRA is worth pricing out next, since the mechanic that blocked you doesn't apply to it when it's the only benefit you offer.
A worked example for a Golden Isles employer
Here's what the Glynn County numbers look like applied to a real headcount. Assume a 14-employee Glynn County company — a boutique inn, a mid-size restaurant, or a professional-services firm near the port — currently renewing a small-group plan priced at this year's Glynn County benchmark.
Here's the math
The 2026 small-group benchmark in Glynn County is $1197.69 a month per employee, or $14372.28 a year. The 2026 individual-market benchmark is $608.92 a month, or $7307.04 a year. The difference is $7,065 a year per employee. For a 14-person company, funding ICHRA contributions at the benchmark level instead of renewing small group works out to an estimated $98,913 a year in aggregate estimated savings.
This is illustrative math built from real 2026 county rate data and a hypothetical headcount. It is not a quote, and it assumes the employer sets the ICHRA contribution at the benchmark level, which is a design choice, not a requirement. Your actual number depends on your employees' ages, exact home counties, and the plans they choose once they're shopping with their own budget.
The same arithmetic scales down cleanly to a smaller case: a 6-person gift shop on St. Simons Island that never seriously priced group coverage because the owner assumed a business that small couldn't offer anything worth having. At the $608.92 individual benchmark, funding an ICHRA for all six employees costs about $ 3654 a month in total contributions — a real, tax-free benefit offered to every eligible employee regardless of how many hours they work per season, since there's no enrollment percentage to clear and no group underwriting to qualify for.
At the other end of the size range, a 55-employee resort-adjacent operation crosses into ALE territory under the employer mandate, which changes the calculus without changing the underlying county math. The same benchmark comparison applies, but an ALE has to run the affordability safe-harbor test — against the 9.96% threshold for 2026 or 10.22% for 2027 — carefully for every employee class, since an ICHRA offer judged "unaffordable" for even a handful of lower-paid employees can trigger a penalty. That's not a reason to avoid ICHRA at that size; it's a reason to model the affordability test before setting a contribution amount, which our eligibility guide walks through in detail.
Setting up an ICHRA in Glynn County
Georgia layers its own participation-cap rule on top of the federal framework, but the underlying setup sequence is the same one that applies in any other state. What determines whether a Glynn County rollout goes smoothly:
- Pull your census by county, not by office address. A business headquartered in Brunswick with staff living in Camden, McIntosh, Wayne, Brantley or Pierce County shares the same rate comparison; confirm each employee's actual home county rather than assuming.
- Decide how you'll define your seasonal or part-time class. An hours-based eligible class (for example, employees regularly scheduled 20+ hours a week) is a legitimate way to extend a benefit to seasonal staff without promising it to every one-week fill-in hire.
- Check whether you're offering ICHRA alone or alongside a group plan. That decision determines whether any class-size minimum applies at all.
- Model affordability before you set a contribution. The reimbursement level decides whether an employee keeps or waives premium tax credit eligibility, against the 9.96% (2026) or 10.22% (2027) Required Contribution Percentage.
- Send the required notice on time. Eligible employees need written notice at least 90 days before the plan year starts, with specific required content.
- Budget for onboarding support, especially at hiring surges. Seasonal hires who've never shopped Georgia's individual marketplace need guidance once, at enrollment, not a lengthy annual open-enrollment process.
See our full ICHRA setup timeline for the detailed rollout plan, including the exact notice content requirements, and our eligibility guide for the affordability test itself.
If your employer just offered you an ICHRA
This guide is written for the employer side of the decision, but if you're a Glynn County employee who was just told your benefit is changing, the short version is: you'll get a fixed monthly amount and shop for your own plan on the individual marketplace instead of picking from your employer's group menu. Our guide for employees walks through what to expect.
The honest limits of this data
A strong county average is not a guarantee for your specific workforce
- A benchmark comparison is not your actual renewal. The $1197.69 Glynn County figure is a small-group benchmark built from filed rates, not your specific carrier's quote for your specific group.
- The number is shared across eight counties, not unique to Brunswick. Because Glynn sits in a shared rating area, this figure applies identically in Camden, McIntosh, Wayne, Brantley, Pierce, Charlton and Ware counties too; it isn't a Brunswick-specific discount.
- A seasonal workforce cuts both ways. ICHRA removes the participation-percentage mechanic, but it doesn't change the fact that a benefit offered only to a narrow eligible class (say, employees scheduled 30+ hours) leaves your part-time and one-week-fill-in staff uncovered by design, the same as most group plans would.
- Older or higher-risk workforces change the math. Individual-market premiums are age-rated more steeply in some rating areas than small-group premiums, which can narrow real-world savings for an older management or health-system workforce below the benchmark figure.
- Rates move every plan year. A carrier entering or leaving this rating area can shift the comparison for 2027; recheck before every renewal, not just once. Georgia's individual market already moved 34.6% for 2026 per healthinsurance.org, so don't assume this year's spread holds next year.
- Waiving the premium tax credit is part of the deal. An employee whose ICHRA offer is deemed affordable generally cannot also claim a marketplace subsidy for that month, which matters in a state where 89% of marketplace enrollees currently receive one. Model both sides before assuming the reimbursement is pure upside.
How these numbers are calculated
Every county figure in this article comes from the same dataset that powers our savings map, not a survey or a sales estimate. For each county, we compare a 2026 individual-market benchmark premium — the second-lowest-cost silver plan available to a representative enrollee, the same benchmark the federal government uses to calculate premium tax credits — against a small-group benchmark premium built from comparable small-group plan filings for that rating area. Both figures come from Ideon, a licensed insurance rate-data provider, and are cross-verified against CMS public-use marketplace files before publication. A county appears in our location-page dataset when the individual benchmark sits below the small-group benchmark by at least $100 a month; the percentage and dollar figures in this article are the gap between those two numbers, expressed as an annual per-employee figure at 12 times the monthly difference.
Glynn County's population figure (85K) comes from the same underlying county dataset used across the site. The Georgia Department of Labor's Brunswick, GA MSA Area Labor Profile, updated September 2026 and citing the U.S. Census Bureau, separately lists Glynn County's 2025 annual population at 90,306, up from 86,540 in 2024 — a close, independently sourced check using a different methodology and reporting year from our own county dataset. The employment figures in the economy section — 35,763 total private jobs across 3,258 establishments at $52,838 average pay, 7,527 accommodation-and-food-services jobs across 370 establishments at $32,888 average pay, 6,794 health-care jobs across 335 establishments at $68,490 average pay, and 1,338 arts-and-recreation jobs across 79 establishments at $38,930 average pay — come from the U.S. Bureau of Labor Statistics' Quarterly Census of Employment and Wages, Glynn County, Georgia (area code 13127), 2025 annual averages, a separate federal dataset from our own county premium comparison. The regional industry-mix figures (410 accommodation-and-food-services firms, 7,740 jobs, $642 average weekly wage; the 2,403-establishment and 617-establishment size-class rows; and the top-employer list) come from the Georgia Department of Labor's Brunswick, GA Metropolitan Statistical Area Area Labor Profile, Version 4.0, updated September 2026, covering Glynn, Brantley and McIntosh counties together. The Port of Brunswick description comes from the Georgia Ports Authority's own website. The participation-rule citation comes from Ga. Comp. R. & Regs. R. 120-2-10-.12(9)(b), as mirrored by Cornell Law School's Legal Information Institute. The national small-group premium figure (Peterson-KFF), the Georgia individual-market figures (healthinsurance.org), the national family premium figure (KFF), the IRS affordability percentages (Rev. Proc. 2025-25 and 2026-26), and the HealthCare.gov participation and naming details each come from separately published, independent sources, described and cited where they appear. We've kept these data sources clearly separate throughout this article rather than blending them into one number.
Three limitations are worth stating plainly. First, benchmark premiums are built around a representative enrollee profile, so an unusually young or unusually old workforce will see a different real-world spread than the county figure implies. Second, these are benchmark plans, not every plan on the market; an employee who chooses a richer or leaner plan than the benchmark will see a different premium, though the relative spread tends to hold directionally. Third, rates are filed and refreshed annually, so a rating area that qualifies for 2026 is not guaranteed to qualify, or to keep its current percentage, for 2027 if a carrier enters or exits that market.
Questions Glynn County employers actually ask
Does ICHRA beat small-group insurance in Brunswick, Georgia?
Yes. In Glynn County, the Georgia county that contains Brunswick, St. Simons Island, Sea Island and Jekyll Island, the 2026 individual-market benchmark premium runs an estimated 49.2% below the small-group benchmark, about $7,065 per employee per year. That's an estimate built from public and industry rate data, not a quote. It sits well above Georgia's statewide average of 37.2% across the state's 158 counties, ranking 55 by percentage.
Why do Glynn, Camden, McIntosh, Wayne, Brantley and Pierce counties show the exact same numbers?
Georgia, like most states, prices ACA marketplace and small-group benchmark premiums by federally defined rating area, not by individual county. Glynn, Camden, McIntosh, Wayne, Brantley, Pierce, Charlton and Ware counties fall inside the same Southeast Georgia rating area for 2026, so carriers filed one set of benchmark rates that applies identically across all of them: $608.92 individual and $1197.69 small-group, to the cent. A Brunswick employer and a St. Marys (Camden County) or Jesup (Wayne County) employer are looking at the same underlying math, even though they sit in different counties.
How much can a Glynn County employer expect to save?
Using 2026 benchmark data, the estimated gap in Glynn County is $588.77 a month, or $7,065 a year, per employee. For a 14-employee company, that's roughly $98,913 a year in aggregate estimated savings if the employer funds ICHRA contributions at the benchmark level instead of renewing small group. This is illustrative math from public rate data, not a projection of what any specific employer will actually pay.
Why did my 2026 small-group renewal come in higher than expected?
Nationally, small-group insurers filed a median proposed premium increase of 11% for the 2026 plan year across 318 insurers in all 50 states and the District of Columbia, according to the Peterson-KFF Health System Tracker brief published September 24, 2025. That same analysis notes Georgia's rate filings weren't all publicly available, so no Georgia-specific proposed increase percentage exists in that dataset. On the individual-market side, healthinsurance.org's 2026 Georgia marketplace guide puts the average unsubsidized rate increase at 34.6% across the 10 insurers offering marketplace plans in Georgia for 2026, with the average post-subsidy premium actually paid by enrollees running about $164 a month.
Does a small Glynn County employer have to hit a participation minimum to offer ICHRA?
No, not if ICHRA is the only benefit offered. Georgia insurance regulation Ga. Comp. R. & Regs. R. 120-2-10-.12(9)(b) caps how much a small-group carrier can require: 100% of eligible employees for groups of three or fewer, and 75% of eligible employees for groups of four to fifty. That's real relief compared to states with no cap, but a 75% participation bar is still hard to clear for a seasonal restaurant or shop where staff rotate through spring and fall, several are part-time, and a few are already covered through a spouse's plan or Medicare. Per HealthCare.gov's current CHOICE Arrangement guidance, there is no participation-percentage requirement at all when an employer offers the arrangement on its own.
What happens to my employees' premium tax credit if I switch to ICHRA?
An employee who is offered an affordable ICHRA generally becomes ineligible for a premium tax credit for any month that offer applies, whether or not they accept it. Affordability is measured against the IRS's Required Contribution Percentage, which is 9.96% of household income for plan years beginning in 2026 (Rev. Proc. 2025-25) and rises to 10.22% for plan years beginning in 2027 (Rev. Proc. 2026-26). Model that test before you set a contribution amount, especially given that healthinsurance.org's 2026 data shows 89% of Georgia's marketplace enrollees are already receiving a subsidy.
How does ICHRA work for seasonal or part-time hospitality staff?
ICHRA doesn't require full-year, full-time status the way group-plan eligibility rules often do in practice. An employer can define an eligible class (for example, employees who work a minimum number of hours per week) and fund a monthly reimbursement for anyone in that class, including someone who's only on payroll through the spring-to-fall tourist season, without needing to hit a participation percentage across the whole workforce. That doesn't waive the affordability test for employees who are offered coverage, and it doesn't turn a part-time job into a full benefits package on its own; it just removes the group-underwriting mechanic that specifically penalizes a business for having a workforce that shifts month to month.
Is ICHRA now called something else? I keep seeing "CHOICE Arrangement."
HealthCare.gov now labels the same arrangement a "CHOICE Arrangement," and its own page states it is "formerly known as the Individual Coverage Health Reimbursement Arrangements, or ICHRAs." That is an administrative naming update on federal consumer-education pages, not a change to the underlying 2019 federal rule or the compliance requirements it sets. We use "ICHRA" throughout this site because it is still the term used in the regulations themselves; the two names describe the identical arrangement.
Sources
- Cornell Law School Legal Information Institute, Ga. Comp. R. & Regs. R. 120-2-10-.12(9)(b) — Georgia small-group participation-rule cap
- Peterson-KFF Health System Tracker, "How Much and Why Premiums Are Going Up for Small Businesses in 2026" (Sept. 24, 2025)
- healthinsurance.org, "Georgia Health Insurance Marketplace: 2026 Guide"
- KFF, 2025 Employer Health Benefits Survey — national average premiums (Oct. 22, 2025)
- IRS Revenue Procedure 2025-25 — Required Contribution Percentage, plan years beginning in 2026 (9.96%)
- IRS Revenue Procedure 2026-26 — Required Contribution Percentage, plan years beginning in 2027 (10.22%)
- 84 Fed. Reg. 28888 — ICHRA final rule, Departments of the Treasury/IRS, Labor, and Health and Human Services (June 20, 2019)
- HealthCare.gov, "CHOICE Arrangements" — participation and class-size rules; naming update from "Individual Coverage HRA"
- U.S. Bureau of Labor Statistics, Quarterly Census of Employment and Wages — Glynn County, Georgia (area code 13127), 2025 annual averages
- Georgia Department of Labor, Brunswick, GA Metropolitan Statistical Area Area Labor Profile (Version 4.0, updated September 2026) — population, industry mix, size class and top-employer data for Glynn, Brantley and McIntosh counties
- Georgia Ports Authority, "Our Port" — Port of Brunswick cargo and terminal description
- County-level premium comparison:
src/data/qualified_counties.json, 2026 plan year (Ideon rate data, cross-verified against CMS public-use marketplace files)