ICHRA in Newark, Ohio 2026: Licking County 59.6%
Licking County's 2026 benchmark runs an estimated 59.6% below small group, near Intel's $28B Ohio mega-site. See the county data, sourced.
The short version
- Licking County's 2026 individual-market benchmark runs an estimated 59.6% below the small-group benchmark, about $10,624 per employee per year.
- All 88 of Ohio's counties currently clear the $100-a-month bar we use to decide whether a county belongs in this dataset at all — Licking's own gap is nearly $900 a month.
- Licking County is also the site of Intel's planned $28 billion chip-fab project, which JobsOhio says has already produced more than 9.4 million construction work hours through 2025 — a hiring boom that makes "we can't compete for workers" a live problem for local small employers, not a hypothetical one.
- Qualifying is not the same as guaranteed savings for your business. The honest limits are covered later, including where this comparison breaks down for a specific workforce.
Does ICHRA beat small group in Newark, Ohio?
Yes, on the numbers behind the 2026 plan year. An ICHRA (Individual Coverage Health Reimbursement Arrangement) is an IRS-defined arrangement that lets an employer set a fixed monthly reimbursement amount and let each employee buy their own individual-market plan with it, tax-free. In Licking County, the Ohio county that contains Newark, Pataskala, Heath and Granville, the 2026 individual-market benchmark premium runs an estimated 59.6% below the small-group benchmark premium, according to a county-by-county comparison built from Ideon rate data and cross-verified against CMS public-use marketplace files.
Licking isn't Ohio's widest percentage spread — it ranks 27 out of 88 qualifying counties on that measure, tied with the rest of the Columbus rating area, including Franklin County itself. What makes Licking County worth its own guide isn't the percentage; it's that the county is in the middle of the largest single private construction project in Ohio history, and that project is reshaping the local labor market faster than most small employers' benefits plans can keep up.
Of the 1,309 counties nationwide in our dataset, 88 are in Ohio, and every one of them clears the $100-a-month gap we use as the floor for including a county at all. That's a genuinely unusual finding for a state this size, and we treat it carefully rather than as a marketing headline — it does not mean every Licking County employer saves money by switching. It means the county-level obstacle that rules ICHRA out entirely in states like Texas or Florida simply isn't present here. The real question for a Licking County employer is how big the gap is for their specific workforce, and whether a rollout is worth the administrative change. That's what the rest of this guide works through.
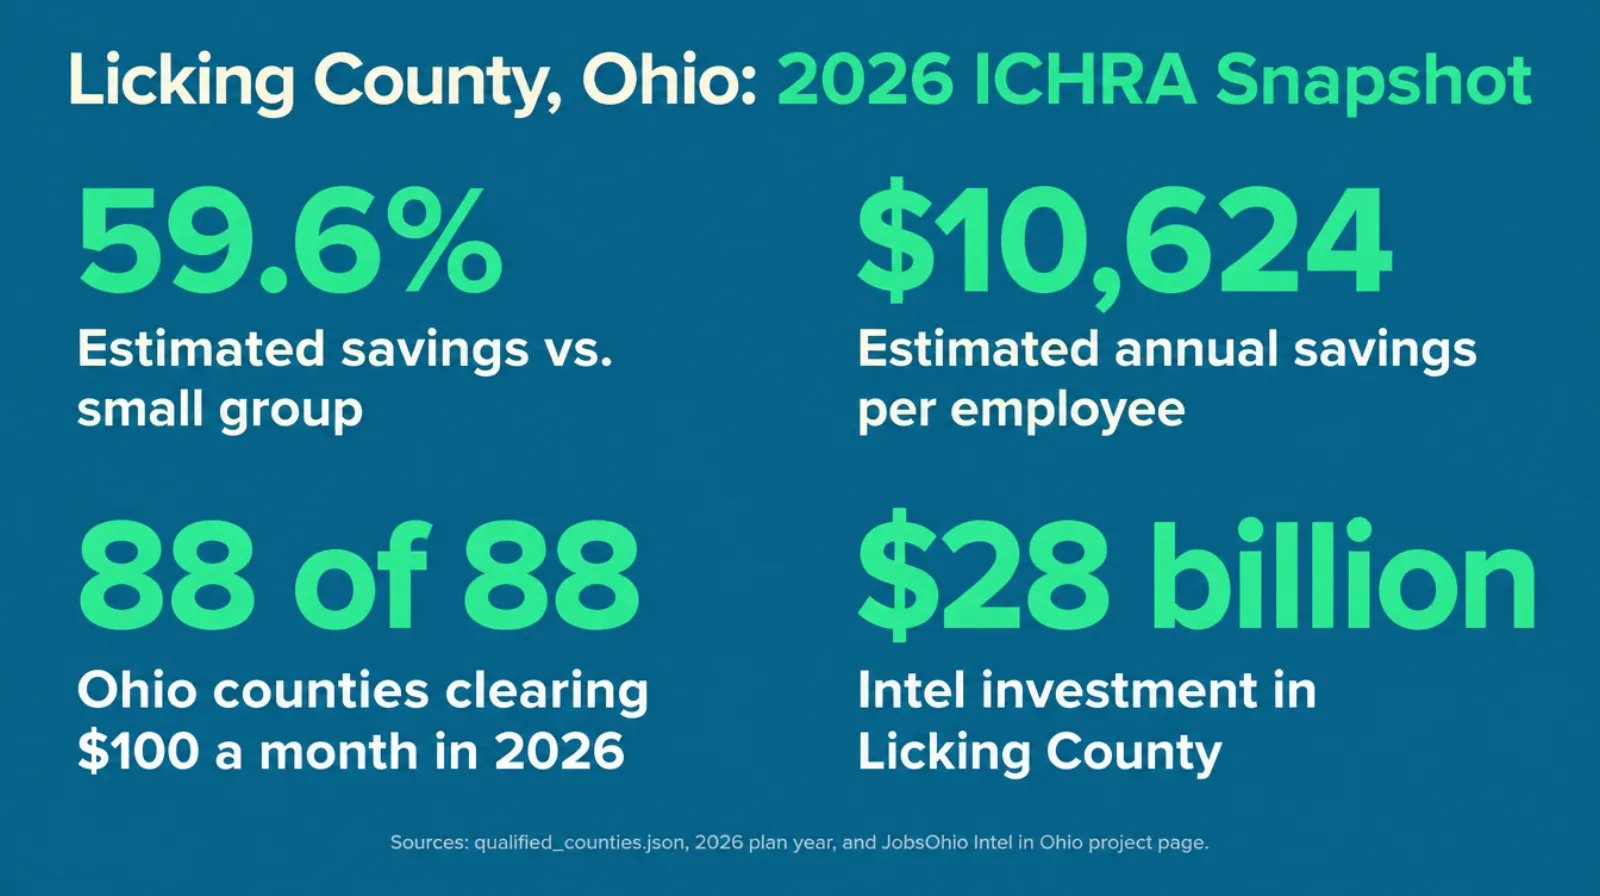
59.6%
Estimated Licking County savings vs. small group
88/88
Ohio counties clearing $100/month in 2026
179K
Licking County residents
$10,624
Est. Licking County savings per employee, per year
Licking County's hiring boom, and the benefits problem it creates
Start with the pain point, because it's a real one for small employers around Newark right now: you are trying to hire and keep good people in a county where the area's biggest employer just announced it needs thousands of workers, and you cannot match its budget. That is the position a lot of Licking County subcontractors, suppliers, restaurants and service businesses are in today, and a benefits offer of any size is one of the few levers a small company actually has.
According to JobsOhio's own project page, Intel's planned investment in its Licking County chip manufacturing site is $28 billion, spread across two new semiconductor fabs on roughly 926 acres of the New Albany International Business Park, land that sits inside Licking County even though the surrounding community carries the New Albany name. The project is expected to create 3,000 direct Intel manufacturing jobs, 7,000 construction jobs over the course of the build, and roughly 10,000 additional indirect and support roles across the broader supplier and service ecosystem. JobsOhio reports that, through 2025, crews had logged more than 9.4 million work hours on-site, with construction still underway heading into the 2026 plan year.
None of that changes Licking County's benchmark insurance math directly — the 59.6% spread comes from countywide individual and small-group rate filings, not from any single employer's payroll. What it changes is the competitive environment every other Licking County employer is hiring into. A construction subcontractor, an electrical contractor, a caterer, or a retail operation near Heath or Pataskala is now competing for hourly workers against a project measured in the billions of dollars. Wages are one lever in that fight, and most small employers can only move that one so far. A real, tax-free health benefit — even a modest one — is a lever a five-person company can pull that it genuinely could not afford under a traditional small-group plan with a participation minimum.
This is not an ICHRA endorsement of the Intel project
We're not evaluating the semiconductor project itself, its incentive package, or its economic development merits — that's outside what this dataset measures. The relevant fact for this article is narrower: a large, fast-moving construction and hiring project is underway inside Licking County, and it changes the local labor market that every small employer in the county is hiring into, benefits offer or not.
Why Ohio's 2027 renewal letters keep landing high
If your broker's renewal letter came in heavier than last year, you're reading it correctly and you're far from alone. Ohio's small-group insurers filed for an unweighted average increase of about 16.4% for 2027 coverage, according to ACA Signups' analysis of the federal Rate Review database at ratereview.healthcare.gov. On the individual side, that same analysis put Ohio's quasi-weighted filed increase at roughly 13.0% — the gap between the two figures is the mechanism that makes ICHRA math work, not a coincidence.
That follows a national pattern. Nationally, small-group insurers filed a median premium increase of 14% for the 2027 plan year, across 295 insurers filing in all 50 states and the District of Columbia, and about 59% of those insurers requested increases between 10% and 20%, according to the Peterson-KFF Health System Tracker. The same analysis notes the underlying medical trend driving those filings sits at a median estimate of 10.8%, reflecting price and utilization growth across services and pharmaceuticals, and that the fully-insured small-group market itself has shrunk from roughly 17 million covered lives in 2013 to about 10 million in 2024 — a 41% drop, per KFF's analysis of that same market. Fewer covered lives in the small-group risk pool tends to push per-employee costs higher for the businesses that remain in it, which is part of why so many Licking County small businesses are looking at ICHRA for the first time, not because individual coverage got dramatically cheaper, but because group coverage kept climbing.
None of that changes the underlying mechanic that makes ICHRA work in a county like Licking: what matters isn't whether either market's prices went up in isolation, it's whether individual rates rose relative to small-group rates in the same county. Ohio's small-group carriers have been filing steep increases for two consecutive cycles, and the individual market hasn't closed that gap in a single one of the state's 88 counties.
A rising individual market doesn't cancel out the spread
Individual-market premiums have been climbing too, but small-group premiums have climbed by a similar or larger margin in most Ohio counties. What decides the ICHRA math is the gap between the two, county by county — not whether either one went up on its own.
How an ICHRA actually works, mechanically
Before the Licking County numbers mean anything, it helps to be precise about what's being compared, since most of the confusion around ICHRA comes from skipping this step.
An ICHRA is an employer-funded health reimbursement arrangement created by a 2019 final rule from the IRS and Treasury, the Department of Labor, and HHS, published at 84 Fed. Reg. 28888 on June 20, 2019, effective August 19, 2019, and applicable to plan years beginning on or after January 1, 2020. Instead of choosing one group health plan for everyone, the employer sets a fixed monthly reimbursement amount, and each employee uses that money to buy an individual-market plan of their own choosing, then submits proof of coverage (called substantiation) to get reimbursed tax-free. The employer isn't picking a plan for forty different households; the employer is funding a budget, and the employee is doing the shopping.
The comparison behind every number in this article rests on two specific prices for a given county and rating area — the geographic zone insurance regulators use to set premiums, usually a cluster of neighboring counties. The individual-market benchmark premium is the second-lowest-cost silver-level plan available in that rating area to a representative 40-year-old enrollee. "Silver" refers to one of four ACA metal levels (bronze, silver, gold, platinum) describing how costs split between premium and out-of-pocket spending, not the quality of care. This is the same benchmark the federal government uses to calculate premium tax credits, which is why it's a defensible number to build a comparison on rather than one insurer's list price. The small-group benchmark premium is the equivalent figure built from comparable small-group plan filings for that same rating area. When the individual benchmark is lower, the county "qualifies," and the gap between the two is the estimated per-employee savings if the employer funds ICHRA at that benchmark level.
Two more terms matter once an employer is actually deciding whether to switch. The affordability safe harbor is the test that decides whether the ICHRA offer counts as "affordable" under IRS rules — for plan years beginning in 2026 that test runs against a Required Contribution Percentage of 9.96% of household income (IRS Rev. Proc. 2025-25), rising to 10.22% for plan years beginning in 2027 (IRS Rev. Proc. 2026-26), the highest that percentage has ever been. Get the contribution amount wrong relative to that threshold and an employer can trigger a penalty tied to the employer mandate, the ACA requirement that applies to ALEs (applicable large employers, generally 50 or more full-time-equivalent employees). Smaller, non-ALE employers aren't subject to that mandate at all, which matters for the many small subcontractors and suppliers scaling up around the Intel build without yet crossing that headcount line.
One structural piece is often misunderstood: an employer can define different employee classes — for example, full-time versus part-time, salaried versus hourly, or by geographic rating area — and offer different benefits to each class, subject to federal minimum-size rules for some class types. What an employer cannot do is offer the same class of employees a choice between ICHRA and a traditional group plan; it's one or the other, per class, not both at once for the same people.
Licking County's rate spread, in dollars
Here is the actual 2026 benchmark comparison for Licking County, the county that contains Newark, Pataskala, Heath, Granville and Johnstown. The individual-market benchmark premium is $600.46 a month. The small-group benchmark premium, built from comparable small-group plan filings for the same rating area, is $1485.83 a month. That's a gap of $885.37 a month, or $10,624 a year, per employee, an estimated 59.6% in favor of the individual market.
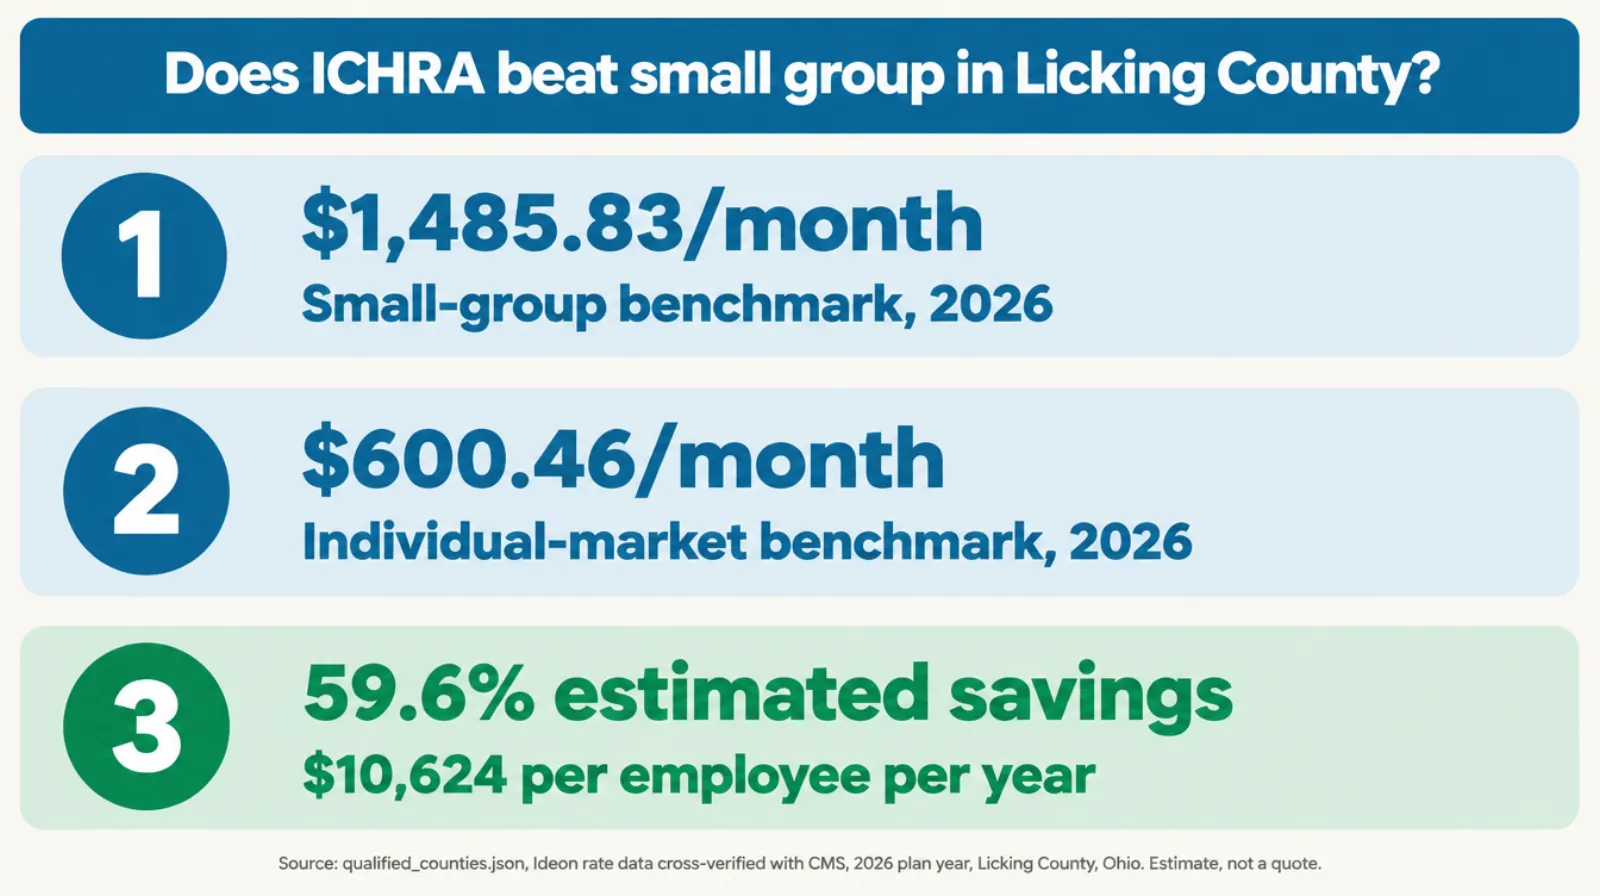
Put another way: over a full year, the small-group benchmark works out to about $17,830 per employee, while the individual-market benchmark works out to about $7,206. That's the $10,624 gap in annual terms, per employee, if an employer funds ICHRA contributions at the benchmark level instead of renewing small group.
| County | Individual benchmark | Small-group benchmark | Savings vs. small group |
|---|---|---|---|
| Franklin (Columbus) | $600.46 | $1485.83 | 59.6% |
| Licking (Newark) | $600.46 | $1485.83 | 59.6% |
| Fairfield County | $600.46 | $1485.83 | 59.6% |
| Delaware County | $600.46 | $1485.83 | 59.6% |
| Knox (Mount Vernon) | $768.89 | $1485.83 | 48.3% |
| Muskingum (Zanesville) | $746.66 | $1294.77 | 42.3% |
Licking County sits inside the Columbus metro's rating cluster despite feeling, in Newark and points east, more like its own small city than a Columbus suburb. See the full Ohio savings breakdown for every qualifying county, or the national savings map to look up a specific county by name.
What changes for a Licking County employer
The rate spread explains where the money comes from. It doesn't explain what actually changes day to day for the person running payroll and benefits. Here's the practical shift, side by side.
Renewing small group
- Cost is whatever the renewal letter says it is
- One or two plans have to suit everybody on staff
- Carrier participation minimums to maintain
- Enrollment can stall when hiring moves fast and unevenly
- Shopping the market every single year, hoping for a smaller increase
VariableBudget set by the carrier's renewal
Running an ICHRA
- Cost is the contribution the employer chose
- Each employee picks their own plan and network
- No carrier participation minimum to worry about
- A new hire is a contribution and a notice, not a re-enrollment event
- A substantiation and reimbursement workflow instead of annual shopping
FixedBudget set by the employer
Admin work doesn't disappear in that trade, it moves. Renewal shopping and census management get replaced by substantiation review and monthly reimbursements. For a Licking County subcontractor adding crew members through 2026 and 2027 as the Intel build continues, the ability to add a new hire's contribution without touching a group enrollment window is a real operational advantage, not just a cost one.
Why Franklin, Fairfield and Delaware price identically, and Knox does not
Licking County doesn't stand alone. Franklin County (1.3M residents, home to Columbus), Fairfield County (159K residents, home to Lancaster) and Delaware County (216K residents) sit in the same marketplace rating area as Licking and carry the exact same 2026 benchmark comparison: a $600.46 individual benchmark against a $1485.83 small-group benchmark, the same 59.6% spread and the same $10,624 estimated annual savings per employee. A Licking County-based employer with staff commuting in from Columbus, Lancaster or Delaware County, or Intel subcontractor crews commuting the other direction from Columbus into the New Albany site, doesn't need a separate calculation for each — the same math applies across the whole cluster.
Knox County, just to the east toward Mount Vernon, and Muskingum County, further southeast toward Zanesville, sit in different rating areas with noticeably different spreads: Knox runs $768.89 individual against $1485.83 small-group, a 48.3% spread, while Muskingum runs $746.66 against $1294.77, a 42.3% spread. Coshocton County, further east still, comes in at 55.2%. All three still clear the $100-a-month floor comfortably, but an employer whose staff spans both the Columbus cluster and points east should check each rating area separately on the savings map rather than average them.
Why all 88 Ohio counties qualify, and what that does not mean
A qualifying county means the individual-market benchmark premium sits below the small-group benchmark premium for that county, for the 2026 plan year, based on the rate filings each carrier submitted. Ohio's small-group carriers have filed some of the steeper increases in the country across the last two cycles, which pushes small-group benchmarks up. At the same time, the state's individual market hasn't seen its benchmark premiums rise by enough to close that gap in any county. The net effect for 2026 is that all 88 Ohio counties land on the ICHRA side of the comparison, with an average spread of 54.9% and every single one clearing the $100-a-month floor we use to decide whether a county belongs in the dataset at all. Licking sits in the state's largest savings band, 50-60%, alongside 46 of Ohio's 88 qualifying counties.
This is a real, dataset-driven finding, not a promotional claim, and it is also not permanent. Rates are filed and refreshed every plan year. A single large carrier entering or exiting even one Ohio county's individual market could shift that county's benchmark enough to change the comparison for 2027. We rebuild this dataset each plan year rather than reusing prior-year numbers, and we'd recommend any Licking County employer do the same before every renewal, not just once.
It's also worth being precise about what "every Ohio county qualifies" does not mean. It does not mean every Licking County employer saves money by switching, and it does not mean the savings are the same size everywhere — Licking County's 59.6% spread is real money, but it trails Cincinnati's Hamilton County at 62.3% and leads Youngstown's Mahoning County at 58.9% by a modest margin. It does not account for your specific employees' ages, since individual-market premiums are age-rated more steeply in some rating areas than small-group premiums are. And it is a benchmark comparison, not a quote for any real plan a specific employee would actually choose.
Licking County's insurance math doesn't move because a $28 billion chip plant is under construction next door. Its labor market does. A benefits offer a five-person company can actually afford is one of the few things that competes with that.
Mike MooreA worked example for a Newark-area employer
Here's what the Licking County numbers look like applied to a real headcount. Assume a 20-employee Newark-area company currently renewing a small-group plan priced at this year's Licking County benchmark.
Here's the math
The 2026 small-group benchmark in Licking County is $1485.83 a month per employee, or $17829.96 a year. The 2026 individual-market benchmark is $600.46 a month, or $7205.52 a year. The difference is $10,624 a year per employee. For a 20-person company, funding ICHRA contributions at the benchmark level instead of renewing small group works out to an estimated $212,489 a year in aggregate estimated savings.
This is illustrative math built from real 2026 county rate data and a hypothetical headcount. It is not a quote, and it assumes the employer sets the ICHRA contribution at the benchmark level, which is a design choice, not a requirement. Your actual number depends on your employees' ages, exact home counties, and the plans they choose once they're shopping with their own budget.
| Employees | Small-group benchmark, annual | ICHRA at individual benchmark, annual | Estimated annual savings |
|---|---|---|---|
| 6 | $106,980 | $43,233 | $63,747 |
| 20 | $356,599 | $144,110 | $212,489 |
| 50 | $891,498 | $360,276 | $531,222 |
Source: src/data/qualified_counties.json, 2026 plan year, Licking County, Ohio
benchmark comparison. Illustrative arithmetic, not a quote for any specific employer.
The same arithmetic scales down cleanly. A 6-person Licking County subcontractor that has never offered health coverage at all — the scenario the HRA Council data below shows is now the norm rather than the exception — could fund an ICHRA at the $600.46 individual benchmark and offer a real, tax-free benefit for about $3603 a month in total contributions, or roughly $43,233 a year for the whole company. That's a genuinely different conversation than trying to buy a six-person small-group plan, where participation minimums and per-employee pricing tend to make the smallest groups the hardest and most expensive to cover, and it's a small enough number that it can compete on the same job posting as a wage bump.
At the other end of the size range, a 50-employee Licking County company — a scale several Intel-adjacent suppliers are approaching as the project ramps — crosses into ALE territory under the employer mandate, which changes the calculus without changing the underlying county math. The same Licking County benchmark comparison applies, but an ALE has to run the affordability safe-harbor test — against the 9.96% threshold for 2026 or 10.22% for 2027 — carefully for every employee class, since an ICHRA offer judged "unaffordable" for even a handful of lower-paid employees can trigger an employer-mandate penalty. That's not a reason to avoid ICHRA at 50 employees; it's a reason to model the affordability test before setting a contribution amount, which our eligibility guide walks through in detail.
How Ohio's 88 qualifying counties break down by savings tier
Number of counties in each savings band, 2026 plan year. Source: Ideon rate data, cross-verified against CMS public-use files.
Licking sits in the 50-60% band, Ohio's largest, above the state's lower tiers and well clear of the $100-a-month floor. Illustrative and rounded; not an offer of insurance or a guarantee of savings.
How ICHRA adoption is actually growing
Licking County's numbers sit inside a national adoption trend that keeps compounding. The HRA Council's fifth annual report, Growth Trends for ICHRA & QSEHRA, Vol. 5 (released August 12, 2026), found that ICHRA-covered lives surpassed 500,000 nationally at the start of 2026 — roughly double the 250,000 covered lives the Council substantiated for January 2025 — spread across more than 20,000 U.S. businesses now offering ICHRA or QSEHRA. Adoption among applicable large employers (ALEs) grew 108% year over year, the fastest-growing segment in the report.
The number that matters most for a Licking County employer weighing this for the first time: more than two-thirds of small businesses offering ICHRA had previously offered no health coverage options at all, and 93% of small employers newly adopting QSEHRA in 2026 had never offered coverage before. For most small Licking County businesses hiring around the Intel build, the realistic comparison usually isn't "ICHRA versus our current group plan." It's "ICHRA versus offering nothing," which is a much easier case to make when the county's largest project is hiring construction and manufacturing workers by the thousands.
New coverage, not a switch
Over two-thirds of small ICHRA employers had never offered coverage before.
500,000+ lives covered nationally
ICHRA-covered lives surpassed 500,000 at the start of 2026, across 20,000+ businesses.
Large employers are following
ALE adoption grew 108% year over year, the fastest-growing segment.
Setting up an ICHRA in Licking County
Ohio does not layer state-specific ICHRA rules on top of the federal framework. The same IRS, Department of Labor and HHS final rule that governs ICHRA everywhere applies here, and the setup sequence is the same one that applies in any other state. What determines whether a Licking County rollout goes smoothly:
- Pull your census by county, not by office address. A company headquartered in Newark with crew or staff living in Franklin, Fairfield, Knox or Muskingum County has employees spread across more than one rating area.
- Check every employee's actual county on the savings map. Given that all 88 Ohio counties currently qualify, this step is less about ruling counties out and more about sizing the real dollar gap for your specific workforce.
- Model affordability before you set a contribution. The reimbursement level decides whether an employee keeps or waives premium tax credit eligibility, against the 9.96% (2026) or 10.22% (2027) Required Contribution Percentage.
- Define employee classes carefully, if you use them. Class rules carry minimum-size requirements and cannot offer the same class a choice between ICHRA and group coverage.
- Send the required notice on time. Eligible employees need written notice at least 90 days before the plan year starts, with specific required content.
- Build a workflow for fast hiring. If you're adding crew or staff monthly around the Intel build, plan a repeatable process for adding a new hire's contribution and notice rather than treating each one as a one-off.
See our full ICHRA setup timeline for the detailed rollout plan, including the exact notice content requirements, and our eligibility guide for the affordability test itself. Before anything else, check whether your county is one where this works: the savings map answers that in about ten seconds.
If your employer just offered you an ICHRA
This guide is written for the employer side of the decision, but if you're a Licking County-area employee who was just told your benefit is changing, the short version is: you'll get a fixed monthly amount and shop for your own plan on the individual marketplace instead of picking from your employer's group menu. Our guide for employees walks through what to expect.
Run your counties first
Before scheduling a single meeting, look up every county where you actually have employees on the savings map. Licking's spread is real, but if your crews also work in Knox or Muskingum County, their numbers look noticeably different — worth knowing before you set one contribution amount for the whole company.
The honest limits of this data
Qualifying statewide is not a guarantee for your business
- A benchmark comparison is not your actual renewal. The $1485.83 Licking County figure is a small-group benchmark built from filed rates, not your specific carrier's quote for your specific group.
- Older or higher-risk workforces change the math. Individual-market premiums are age-rated more steeply in some Ohio rating areas than small-group premiums, which can narrow real-world savings for an older team.
- Rates move every plan year. A carrier entering or leaving a county can shift the comparison for 2027; recheck before every renewal, not just once.
- A qualifying county means the benchmark comparison favors ICHRA, not that every employee will pick a plan priced at the benchmark. Some employees will choose richer or leaner plans than the benchmark, which changes their individual premium without changing the underlying spread.
- Waiving the premium tax credit is part of the deal. An employee whose ICHRA offer is deemed affordable generally cannot also claim a marketplace subsidy for that month. Model both sides before assuming the reimbursement is pure upside for the employee.
- A construction boom is not a permanent labor-market condition. The Intel build is a multi-year project, not a guarantee of the local labor market's shape in 2030 and beyond. Build a benefits plan you can sustain past the construction phase, not just through it.
How these numbers are calculated
Every county figure in this article comes from the same dataset that powers our savings map, not a survey or a sales estimate. For each county, we compare a 2026 individual-market benchmark premium — the second-lowest-cost silver plan available to a representative enrollee, the same benchmark the federal government uses to calculate premium tax credits — against a small-group benchmark premium built from comparable small-group plan filings for that rating area. Both figures come from Ideon, a licensed insurance rate-data provider, and are cross-verified against CMS public-use marketplace files before publication. A county "qualifies" for our dataset when the individual benchmark sits below the small-group benchmark by at least $100 a month; the percentage and dollar figures in this article are the gap between those two numbers, expressed as an annual per-employee figure at 12 times the monthly difference. Licking County's population figure (179K) comes from the same underlying county dataset used across the site.
The Intel project figures ($28 billion investment, 926 acres, 3,000 direct jobs, 7,000 construction jobs, roughly 10,000 indirect and support roles, and the 9.4-million-work-hour construction milestone through 2025) come from JobsOhio's own "Intel in Ohio" project page, the state's official economic development agency, fetched directly rather than taken from a news summary. The 2027 national small-group figure (14% median across 295 insurers) comes from a separately published Peterson-KFF analysis, not from our own county dataset, and describes a national trend rather than the Licking-specific benchmark comparison above. The Ohio-specific 2027 filing figures (16.4% small group, 13.0% individual) are a trade-press aggregation of the federal Rate Review database at ratereview.healthcare.gov, produced independently by ACA Signups; we confirmed that organization names that same federal database as its underlying source rather than treating the aggregation itself as the primary record. We've kept every one of these data sources clearly separate throughout this article rather than blending them into one number.
Three limitations are worth stating plainly. First, benchmark premiums are built around a representative enrollee profile, so an unusually young or unusually old workforce will see a different real-world spread than the county figure implies. Second, these are benchmark plans, not every plan on the market; an employee who chooses a richer or leaner plan than the benchmark will see a different premium, though the relative spread tends to hold directionally. Third, rates are filed and refreshed annually, so a county that qualifies for 2026 is not guaranteed to qualify for 2027 if a carrier enters or exits that market.
Questions Licking County employers actually ask
Does ICHRA beat small-group insurance in Newark, Ohio?
Yes, on the 2026 benchmark comparison. In Licking County, the county that contains Newark, Pataskala, Heath and Granville, the individual-market benchmark premium runs an estimated 59.6% below the small-group benchmark, about $10,624 per employee per year. That's an estimate built from public and industry rate data, not a quote, and your actual result depends on your employees' ages and the plans they choose.
Does Intel's construction project in Licking County actually affect ICHRA pricing?
No, not directly. Licking County's 59.6% benchmark spread comes from countywide individual and small-group rate filings, not from any single employer or project. What the Intel build changes is the local labor market: JobsOhio puts the project at a planned $28 billion investment across two chip fabs on roughly 926 acres of the New Albany International Business Park inside Licking County, with 3,000 direct Intel jobs, 7,000 construction jobs during the build, and about 10,000 additional indirect and support roles. That's a lot of employers, from subcontractors to suppliers to the businesses that serve those workers, all competing for the same local hires at the same time the benefits conversation is happening.
How much can a Licking County employer expect to save?
Using 2026 benchmark data, the estimated gap in Licking County is $885.37 a month, or $10,624 a year, per employee. For a 20-person company, that is roughly $212,489 a year in aggregate estimated savings if the employer funds ICHRA contributions at the benchmark level instead of renewing small group. This is illustrative math from public rate data, not a projection of what any specific employer will actually pay.
Are Franklin, Fairfield and Delaware counties priced the same as Licking County?
Yes. Franklin County (Columbus), Fairfield County (Lancaster) and Delaware County sit in the same marketplace rating area as Licking and carry the identical 2026 benchmark comparison: a $600.46 individual benchmark against a $1485.83 small-group benchmark, the same 59.6% spread. An employer with staff commuting in from any of those counties, or from Columbus into Licking County for the Intel build, doesn't need a separate calculation for them.
Why did my 2026 or 2027 small-group renewal come in higher than I expected?
Nationally, small-group insurers filed a median premium increase of 14% for 2027 across 295 insurers in all 50 states and the District of Columbia, according to the Peterson-KFF Health System Tracker. Ohio's own carriers filed for even more on the small-group side: an unweighted average increase of about 16.4% for 2027, per ACA Signups' analysis of the federal Rate Review database (ratereview.healthcare.gov). Ohio's individual-market filings for 2027 came in lower by comparison, an estimated 13.0% on a quasi-weighted basis, per that same ACA Signups analysis. Thinner competition among small-group insurers and rising medical claims are pushing most 2026 and 2027 renewal letters up from that side of the market in particular.
Does Ohio impose any state-specific ICHRA rules?
No. ICHRA is a federal HRA structure created by a 2019 final rule from the IRS and Treasury, the Department of Labor, and HHS (84 Fed. Reg. 28888, effective August 19, 2019, applicable to plan years beginning on or after January 1, 2020), and it works the same way in Ohio as in any other state. The Ohio Department of Insurance reviews carrier rate filings for the small-group and individual markets, but it does not add ICHRA-specific requirements on top of the federal rule.
What happens to my employees' premium tax credit if I switch to ICHRA?
An employee who is offered an affordable ICHRA generally becomes ineligible for a premium tax credit for any month that offer applies, whether or not they accept it. Affordability is measured against the IRS's Required Contribution Percentage, which is 9.96% of household income for plan years beginning in 2026 (Rev. Proc. 2025-25) and rises to 10.22% for plan years beginning in 2027 (Rev. Proc. 2026-26), the highest that percentage has ever been. Model that test before you set a contribution amount.
Is a fast-growing small business a good fit for ICHRA, or does it complicate hiring?
It tends to simplify a fast-growth situation rather than complicate it. A small-group plan usually has a participation minimum, so a company hiring quickly and unevenly across departments can run into enrollment problems that have nothing to do with cost. ICHRA has no federal participation minimum, and adding a new hire is a matter of setting their contribution and sending the required notice, not renegotiating group enrollment. For a subcontractor or supplier scaling up around the Licking County Intel build, that administrative flexibility is often worth as much as the 59.6% benchmark spread itself.
Sources
- JobsOhio, "Intel in Ohio" — project investment, jobs and construction-progress figures
- Peterson-KFF Health System Tracker, "How Much and Why Premiums Are Going Up for Small Businesses in 2027"
- ACA Signups, "2027 Rate Changes: Ohio" — analysis of the federal Rate Review database, ratereview.healthcare.gov
- IRS Revenue Procedure 2025-25 — Required Contribution Percentage, plan years beginning in 2026 (9.96%)
- IRS Revenue Procedure 2026-26 — Required Contribution Percentage, plan years beginning in 2027 (10.22%)
- 84 Fed. Reg. 28888 — ICHRA final rule, Departments of the Treasury/IRS, Labor, and Health and Human Services (June 20, 2019)
- HRA Council, "Growth Trends for ICHRA & QSEHRA, Vol. 5" (Aug. 12, 2026)
- County-level premium comparison:
src/data/qualified_counties.json, 2026 plan year (Ideon rate data, cross-verified against CMS public-use marketplace files)