ICHRA in Thomasville, Georgia 2026: Thomas County 53.3%
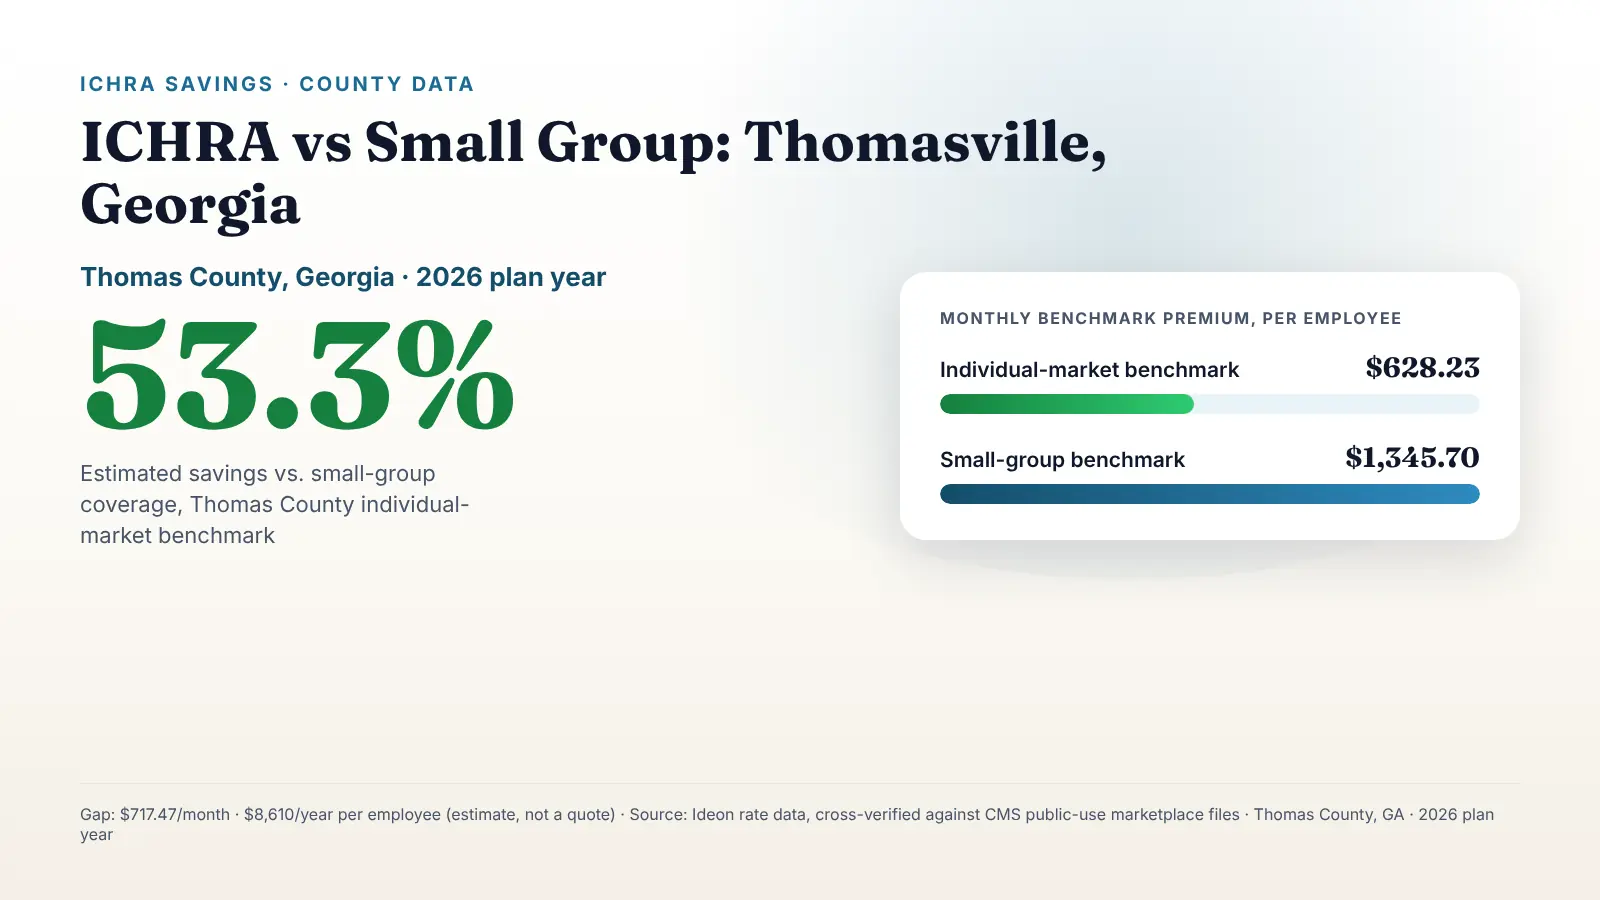
Thomas County's 2026 benchmark runs an estimated 53.3% below small group, about $8,610 a year per employee, one of Georgia's widest gaps. Sourced data.
The short version
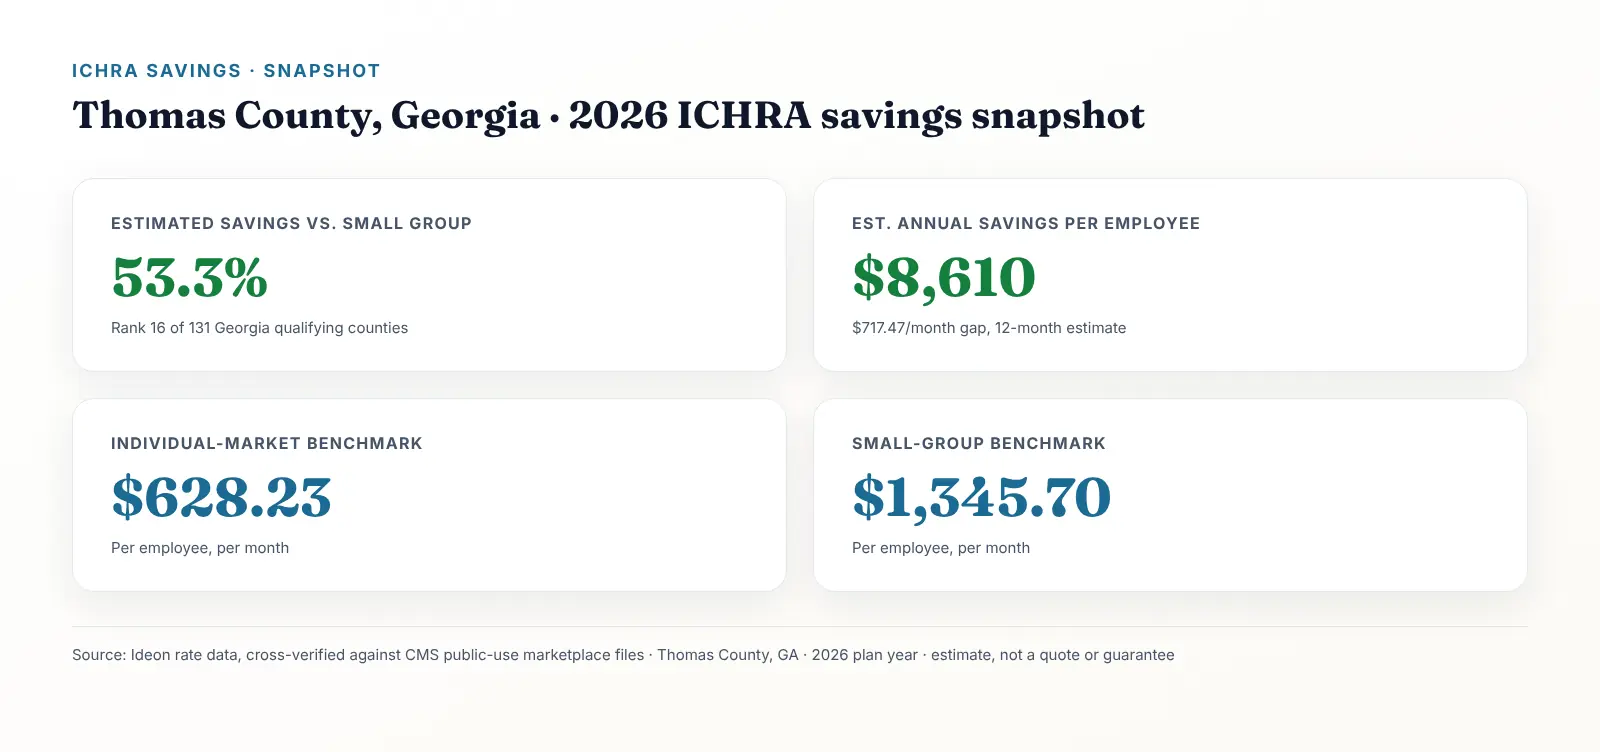
- Thomas County's 2026 individual-market benchmark runs an estimated 53.3% below the small-group benchmark, about $8,610 per employee per year — ranked 16 of Georgia's 131 qualifying counties, well above the statewide qualifying average of 43.8%.
- Eighteen South Georgia counties, covering roughly 440K residents, share Thomas County's exact rating area and carry the identical comparison, including Moultrie, Tifton, Bainbridge, and Cairo.
- Thomasville's two largest private employers — Flowers Foods (headquartered there, about 10,300 employees nationwide) and Archbold, the regional health system (about 2,700 staff) — don't need this comparison. The clinics, vendors, and smaller shops around them do.
- Georgia isn't a uniform "yes" the way Ohio is. 131 of the state's 159 counties clear the $100-a-month bar, and metro Atlanta's core counties fall short — covered later, plainly.
- Qualifying is not the same as guaranteed savings for your business. The honest limits are covered later, including where this comparison breaks down for a specific workforce.
Does ICHRA beat small group in Thomasville, Georgia?
Yes, and the margin here is wider than in most of the Georgia cities we've covered. An ICHRA (Individual Coverage Health Reimbursement Arrangement) is an IRS-defined arrangement that lets an employer set a fixed monthly reimbursement amount and let each employee buy their own individual-market plan with it, tax-free. In Thomas County, the Georgia county that contains Thomasville, the 2026 individual-market benchmark premium runs an estimated 53.3% below the small-group benchmark premium, according to a county-by-county comparison built from Ideon rate data and cross-verified against CMS public-use marketplace files.
That 53.3% ranks 16 out of 131 qualifying Georgia counties on percentage spread, well above the statewide qualifying average of 43.8%. Thomas County isn't Georgia's biggest city or its biggest payroll. What makes it worth its own guide is the opposite: it's proof that a rural, agriculture-and-food- manufacturing county with no major metro nearby can show one of the state's widest individual- versus-small-group gaps, because the gap is driven by how each rating area's carriers priced the two markets, not by population or wealth.
Of the 1,309 counties nationwide in our dataset, 131 Georgia counties clear the $100-a-month gap we use as the floor for including a county at all, out of 159 counties statewide. Thomas sits comfortably inside the upper third of that list.
53.3%
Estimated Thomas County savings vs. small group
131/159
Georgia counties clearing $100/month in 2026
46K
Thomas County residents
$8,610
Est. Thomas County savings per employee, per year
The employer problem this is actually solving
Thomasville calls itself Georgia's "City of Roses." The state legislature made it official on January 26, 2016, during Tourism Day at the Capitol, and the city's annual Rose Show and Festival traces back to a garden-club fundraiser that started in the early 1920s, per the city of Thomasville's own announcement of the designation. That's the postcard version. The working economy underneath it is agriculture, food processing, and furniture manufacturing, anchored by two institutions that dwarf everything else in Thomas County: Flowers Foods, the Fortune 500 baking company behind Nature's Own, Wonder Bread, and Dave's Killer Bread, which has been headquartered at 1919 Flowers Circle in Thomasville since the company's founding and employed roughly 10,300 people nationwide as of its fiscal year ended January 3, 2026, per its 10-K annual report filed with the SEC; and Archbold, the nonprofit regional health system built around John D. Archbold Memorial Hospital, which lists about 2,700 staff members and more than 650 patient beds across Thomas, Grady, Mitchell, Decatur, and Brooks counties, per Archbold's own website.
A company with a national headquarters and a multi-county hospital system in the same small city isn't a typical South Georgia profile, and it creates a specific, repeatable kind of employer problem. A twelve-person logistics brokerage that hauls for Flowers Foods' bakery network, a fifteen-person physical therapy practice that takes referrals from Archbold without being part of it, or an eight-person equipment-repair shop that services the farms and poultry operations around Thomasville watches two institutions that size offer full corporate benefits packages and concludes that competing on benefits is out of reach at its size. That's the pain this article answers: not "our renewal is too expensive," though that's covered too, but "we can't put together a benefit that looks like anything next to Flowers Foods or Archbold."
Why 2026 and 2027 renewals keep landing high
For the Thomasville employers who already carry a small-group plan, the renewal letter has been getting heavier for two straight years, and that's not a local quirk. Nationally, small-group insurers filed a median proposed premium increase of 14% for the 2027 plan year, across 295 insurers filing in all 50 states and the District of Columbia, according to the Peterson-KFF Health System Tracker's August 6, 2026 brief — up from an 11% median across 318 insurers for the 2026 plan year, per the same tracker's September 24, 2025 brief. Fifty-nine percent of insurers proposed increases between 10% and 20% for 2027.
The pressure isn't limited to small group. KFF's own tracking of ACA marketplace competition found that the average number of insurers participating per state fell from 9.6 in 2025 to 9.0 in 2026, and that the number of counties served by only a single ACA issuer jumped from 93 in 2025 to 165 in 2026 — a shift KFF ties largely to Aetna CVS's exit from 17 states and other insurer departures following the expiration of enhanced premium tax credits. Georgia has moved in the opposite direction on that specific point, for reasons covered in the Georgia Access section below.
None of that changes the underlying mechanic that makes ICHRA work in a county like Thomas: what matters isn't whether either market's prices went up in isolation, it's whether individual rates rose relative to small-group rates in the same county and rating area. Thomas County's gap is one of the widest we've found in Georgia, and it's held for the entire 2026 plan year.
How an ICHRA actually works, mechanically
Before the Thomas County numbers mean anything, it helps to be precise about what's being compared, since most of the confusion around ICHRA comes from skipping this step.
An ICHRA is an employer-funded health reimbursement arrangement created by a 2019 final rule from the IRS and Treasury, the Department of Labor, and HHS, published at 84 Fed. Reg. 28888 on June 20, 2019, effective August 19, 2019, and applicable to plan years beginning on or after January 1, 2020. Instead of choosing one group health plan for everyone, the employer sets a fixed monthly reimbursement amount, and each employee uses that money to buy an individual-market plan of their own choosing, then submits proof of coverage (called substantiation) to get reimbursed tax-free. The employer isn't picking a plan for fifteen different households; the employer is funding a budget, and the employee is doing the shopping. HealthCare.gov's current guidance also refers to this arrangement as a CHOICE Arrangement, a federal renaming that doesn't change any of the underlying rules.
The comparison behind every number in this article rests on two specific prices for a given county and rating area — the geographic zone insurance regulators use to set premiums, usually a cluster of neighboring counties. The individual-market benchmark premium is the second-lowest-cost silver-level plan available in that rating area to a representative 40-year-old enrollee. "Silver" refers to one of four ACA metal levels (bronze, silver, gold, platinum) describing how costs split between premium and out-of-pocket spending, not the quality of care. This is the same benchmark the federal government uses to calculate premium tax credits, which is why it's a defensible number to build a comparison on rather than one insurer's list price. The small-group benchmark premium is the equivalent figure built from comparable small-group plan filings for that same rating area. When the individual benchmark is lower, the county "qualifies," and the gap between the two is the estimated per-employee savings if the employer funds ICHRA at that benchmark level.
Two more terms matter once an employer is actually deciding whether to switch. The affordability safe harbor is the test that decides whether the ICHRA offer counts as "affordable" under IRS rules — for plan years beginning in 2026 that test runs against a Required Contribution Percentage of 9.96% of household income (IRS Rev. Proc. 2025-25), rising to 10.22% for plan years beginning in 2027 (IRS Rev. Proc. 2026-26). Get the contribution amount wrong relative to that threshold and an employer can trigger a penalty tied to the employer mandate, the ACA requirement that applies to ALEs (applicable large employers, generally 50 or more full-time-equivalent employees). Smaller, non-ALE employers aren't subject to that mandate at all, which covers nearly every independent business in Thomas County.
One structural piece is often misunderstood: an employer can define different employee classes — for example, full-time versus part-time, or by geographic rating area — and offer different benefits to each class, subject to federal minimum-size rules for some class types. What an employer cannot do is offer the same class of employees a choice between ICHRA and a traditional group plan; it's one or the other, per class, not both at once for the same people.
Thomas County's rate spread, in dollars
Here is the actual 2026 benchmark comparison for Thomas County, the county that contains Thomasville and the smaller communities of Boston, Ochlocknee, and Meigs. The individual-market benchmark premium is $628.23 a month. The small-group benchmark premium, built from comparable small-group plan filings for the same rating area, is $1345.70 a month. That's a gap of $717.47 a month, or $8,610 a year, per employee, an estimated 53.3% in favor of the individual market.
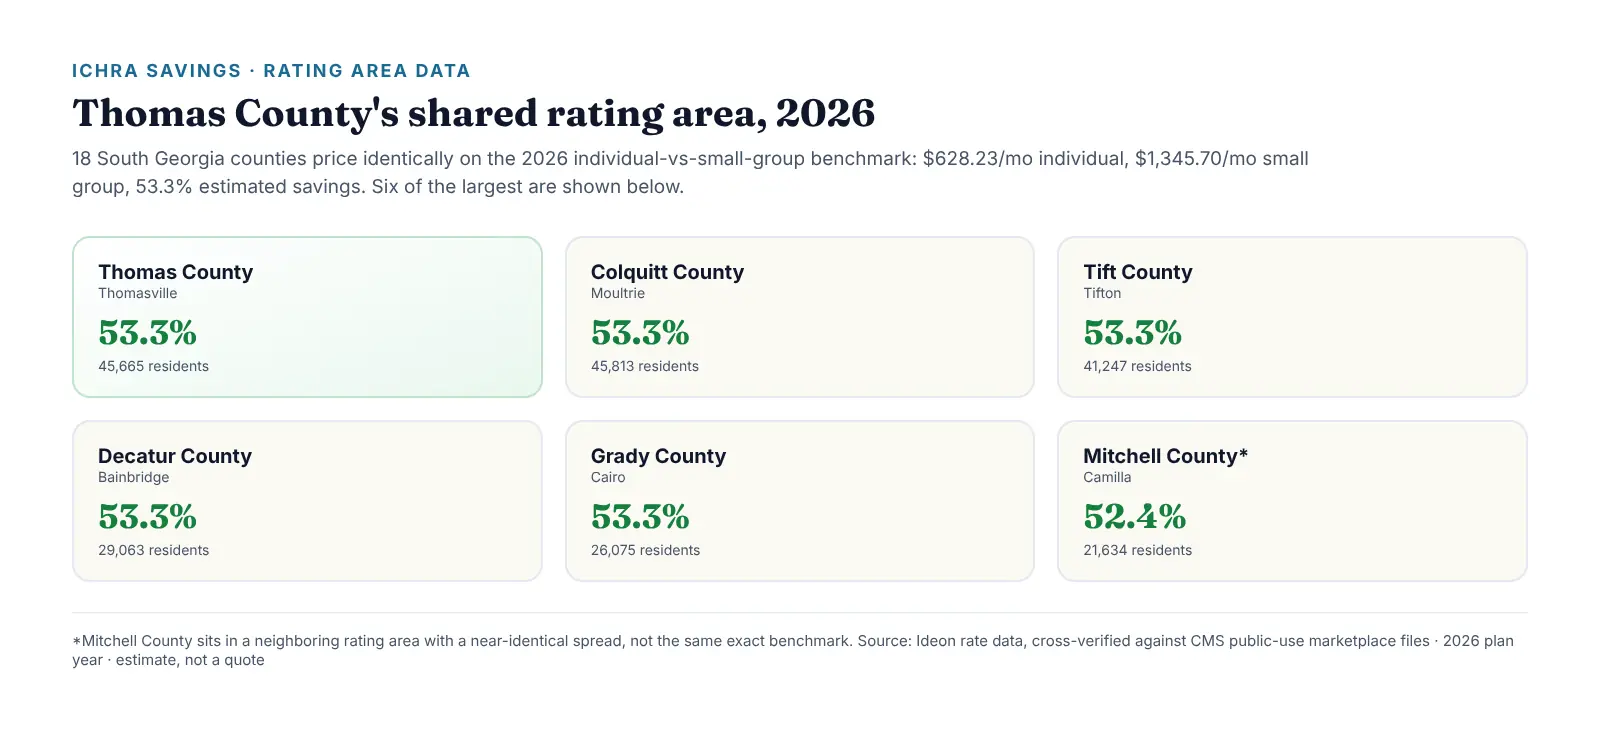
That spread sits well above the statewide qualifying average of 43.8%, and above every Ohio-sized Georgia city we've profiled to date except a handful of other rural counties. At 46K residents, Thomas County is a mid-sized county by Georgia standards — smaller than the Hall, Houston, or Muscogee County metros, but with one of the state's widest percentage gaps.
| County | Population | Savings vs. small group |
|---|---|---|
| Colquitt | 45,813 | 53.3% |
| Thomas | 45,665 | 53.3% |
| Tift | 41,247 | 53.3% |
| Decatur | 29,063 | 53.3% |
| Grady | 26,075 | 53.3% |
See the full Georgia savings breakdown for every qualifying county, or the national savings map to look up a specific county by name.
The 18-county rating area behind that number
Thomas County doesn't stand alone. Eighteen South Georgia counties sit in the same marketplace rating area and carry the exact same 2026 benchmark comparison: a $628.23 individual benchmark against a $1345.70 small-group benchmark, the same 53.3% spread. Besides Thomas, that list includes Ben Hill, Berrien, Brooks, Clinch, Colquitt (Moultrie), Cook, Decatur (Bainbridge), Early, Echols, Grady (Cairo), Irwin, Lanier, Lowndes (Valdosta, which we've covered in its own guide), Miller, Seminole, Tift (Tifton), and Turner counties. Combined, those 18 counties hold an estimated 440K residents, so a Thomasville-based employer with staff commuting in from Moultrie, Tifton, Bainbridge, or Cairo doesn't need to run a separate calculation for them — the same math applies across the shared rating area.
Mitchell County, home to Camilla and part of Archbold's own service area, sits in a neighboring rating area with a close but not identical 52.4% spread — close enough to make the same general case, not close enough to assume the exact dollar figures carry over.
A wide rating area cuts both ways
Carriers price an entire rating area together, so a county doesn't need its own hospital system or population base to qualify — it just needs to sit in a rating area where the individual and small-group markets priced apart. That's good news for employers scattered across rural South Georgia, and it's also why percentage savings and population size don't move together in this dataset.
Flowers Foods and Archbold don't need this guide
Flowers Foods has been publicly traded since the 1960s and today ranks among the largest baking companies in North America, with its corporate headquarters still at 1919 Flowers Circle in Thomasville — the address on the cover page of its own SEC filings. Its fiscal 2025 annual report (10-K, filed February 25, 2026, covering the year ended January 3, 2026) puts total employment at roughly 10,300 people across the country, plus about 5,500 additional full-time leased and temporary workers. That's a national figure, not a Thomas County headcount, but the company's continued presence as a Thomasville-headquartered Fortune 500 employer is itself the relevant fact: a company that size runs its own large-group benefits program as a matter of scale, the same way Archbold does on the healthcare side.
Archbold, the nonprofit system anchored by John D. Archbold Memorial Hospital in Thomasville, lists about 2,700 staff members, 200 "qualified specialists," and more than 650 patient beds across hospitals and clinics serving Thomas, Grady, Mitchell, Decatur, and Brooks counties, per the system's own website. Four of those five counties — Thomas, Grady, Decatur, and Brooks — sit in the exact same rating area covered in this article; Mitchell sits just next door.
Neither institution is shopping for the kind of small-group plan this article is built around. What's left — and what this article is actually for — is the layer of smaller businesses around them: logistics and maintenance contractors that haul for or service Flowers Foods' plant without being on its payroll, independent clinics and diagnostic practices that refer to or contract with Archbold without being owned by it, and the farms, packing houses, retailers, and professional- services firms competing for labor in a county where the two biggest employers already offer real benefits.
Flowers Foods and Archbold don't need this comparison. The contractors, clinics, and shops that supply and surround them do, and Thomas County's math is some of the strongest we've found in Georgia.
Mike MooreWhy participation minimums bite hardest here
Small-group health insurance isn't sold to individual employees one at a time; it's underwritten as a pool, and most carriers require a minimum share of a company's eligible employees to actually enroll before they'll issue the policy at all. That's a participation minimum, and it's a real reason a company can want to offer group coverage and still fail to get a policy issued — not because the price is wrong, but because not enough employees signed up.
The mechanic matters in a market like Thomasville's for a straightforward reason: when a meaningful share of a small company's staff already has coverage through a spouse who works at Flowers Foods, Archbold, or another large local employer with its own benefits, that coverage often keeps them from enrolling in their own employer's smaller group plan. Depending on how the carrier defines its participation math, those declines can push a company below the enrollment threshold even when every eligible employee has coverage somewhere. We've written a full breakdown of exactly how that calculation works, and what counts against you, in our participation requirements guide.
A CHOICE Arrangement sidesteps the mechanic entirely. Per HealthCare.gov, an employer offering a traditional group plan to any employees does face class-size minimums if it also wants to offer a CHOICE Arrangement to a different class — generally 10 employees per class for employers under 100 total employees — but an employer that isn't offering a group plan at all can offer the arrangement to any size class, with no carrier-side participation percentage to clear, because each employee's reimbursement is a separate arrangement funding their own individual-market plan choice, not a pooled insurance product. An eight-person Thomasville shop where five employees are already covered through a spouse's plan at Flowers Foods or Archbold can still offer all eight of them an ICHRA; the three who need it can use it, and the five who don't aren't required to enroll in anything to make the arrangement work.
If a group quote already fell through
If you've already tried to set up small-group coverage in the Thomasville area and couldn't hit a carrier's participation minimum, that's not a dead end — it's a specific, common signal that an ICHRA is worth pricing out next, since the mechanic that blocked you doesn't apply to it.
Georgia's own exchange changes the individual side
Georgia is unusual in a way that matters to this comparison. Since November 1, 2024, the state has run its own state-based health insurance marketplace, Georgia Access, instead of routing individual-market enrollment through the federal HealthCare.gov platform. The Centers for Medicare and Medicaid Services approved Georgia's transition, and the state's Office of Commissioner of Insurance and Safety Fire confirmed that consumers previously enrolled through HealthCare.gov were automatically migrated to the new platform.
The launch coincided with a genuine jump in individual-market participation. Georgia's Office of Commissioner of Insurance and Safety Fire reported that more than 1.3 million Georgians enrolled in marketplace coverage during the transition open enrollment period, the largest figure ever recorded in Georgia's market, and that carrier participation had more than doubled since 2019, with nearly every county having three or more carriers offering on-exchange plans. That is a different trajectory than the national insurer-participation figures cited above, where the number of single-issuer counties nationwide grew. Georgia moved the opposite direction on that specific point right as its own exchange came online.
Why does that belong in a Thomas County-specific article? Because the individual-market benchmark used in every calculation on this page is a function of how many carriers are competing to offer silver plans in Thomas's rating area. More carrier competition on the individual side tends to hold individual premiums down relative to small group — directional, structural context, not a claim that Georgia Access caused Thomas County's specific dollar figure. The benchmark numbers above come from the county dataset, not from the exchange's enrollment report.
For an employer, the practical takeaway is narrower still: Georgia Access changes how a Thomas County employee shops for and enrolls in an individual plan once an ICHRA is in place. It doesn't change any ICHRA compliance requirement, which remains entirely federal.
A worked example for a Thomasville employer
Here's what the Thomas County numbers look like applied to a real headcount. Assume a 15-employee Thomasville company currently renewing a small-group plan priced at this year's Thomas County benchmark.
Here's the math
The 2026 small-group benchmark in Thomas County is $1345.70 a month per employee, or $16148.40 a year. The 2026 individual-market benchmark is $628.23 a month, or $7538.76 a year. The difference is $8,610 a year per employee. For a 15-person company, funding ICHRA contributions at the benchmark level instead of renewing small group works out to an estimated $129,145 a year in aggregate savings.
This is illustrative math built from real 2026 county rate data and a hypothetical headcount. It is not a quote, and it assumes the employer sets the ICHRA contribution at the benchmark level, which is a design choice, not a requirement. Your actual number depends on your employees' ages, exact home counties, and the plans they choose once they're shopping with their own budget.
The same arithmetic scales down to the kind of company this article opened on: an eight-person equipment-repair shop or a twelve-person logistics brokerage that couldn't justify a group plan at its size. That company could fund an ICHRA at the $628.23 individual benchmark and offer a real, tax-free benefit for about $7539 a month in total contributions per employee, offered to every eligible employee regardless of how many of them already have coverage through a spouse's plan at Flowers Foods or Archbold, since there's no enrollment percentage to clear.
At the other end of the size range, a 55-employee Thomasville company crosses into ALE territory under the employer mandate, which changes the calculus without changing the underlying county math. The same Thomas County benchmark comparison applies, but an ALE has to run the affordability safe-harbor test — against the 9.96% threshold for 2026 or 10.22% for 2027 — carefully for every employee class, since an ICHRA offer judged "unaffordable" for even a handful of lower-paid employees can trigger an employer-mandate penalty. That's not a reason to avoid ICHRA at 55 employees; it's a reason to model the affordability test before setting a contribution amount, which our eligibility guide walks through in detail.
How ICHRA adoption is actually growing
Thomas County's numbers sit inside a national adoption trend that keeps compounding. The HRA Council's fifth annual report, Growth Trends for ICHRA & QSEHRA, Vol. 5 (released August 12, 2026, data current through January 31, 2026), found that ICHRA-covered lives surpassed 500,000 nationally at the start of 2026, spread across more than 20,000 U.S. businesses now offering ICHRA or QSEHRA. Adoption among applicable large employers (ALEs) more than doubled year over year, the fastest-growing segment in the report.
The number that matters most for the Thomasville employer this article opened on — the small shop, clinic, or contractor that has never offered coverage, or couldn't get a group quote to go through: over two-thirds of small businesses offering ICHRA had previously offered no health coverage options at all, and 93% of small employers newly adopting QSEHRA in 2026 had never offered coverage before. For most small Thomas County businesses, the realistic comparison usually isn't "ICHRA versus our current group plan." It's "ICHRA versus offering nothing, or versus a group plan we couldn't even get issued," which is a much easier case to make than it sounds.
New coverage, not a switch
Over two-thirds of small ICHRA employers had never offered coverage before.
500,000+ lives covered nationally
ICHRA-covered lives surpassed 500,000 at the start of 2026, across 20,000+ businesses.
Large employers are following
ALE adoption more than doubled year over year, the fastest-growing segment.
Setting up an ICHRA in Thomasville
Georgia does not layer state-specific ICHRA rules on top of the federal framework. The same IRS, Department of Labor, and HHS final rule that governs ICHRA everywhere applies here, and the setup sequence is the same one that applies in any other state, Georgia Access notwithstanding. What determines whether a Thomasville rollout goes smoothly:
- Pull your census by county, not by office address. A company headquartered in Thomasville with staff living in Moultrie or Tifton shares the same numbers, since they're in the same rating area.
- Check every employee's actual county on the savings map. Given that Georgia isn't a uniform "every county qualifies" state the way Ohio is, this step actually rules counties in or out — it isn't a formality here.
- Model affordability before you set a contribution. The reimbursement level decides whether an employee keeps or waives premium tax credit eligibility, against the 9.96% (2026) or 10.22% (2027) Required Contribution Percentage.
- Define employee classes carefully, if you use them. Class rules carry minimum-size requirements when a group plan is also offered, and cannot offer the same class a choice between ICHRA and group coverage.
- Send the required notice on time. Eligible employees need written notice at least 90 days before the plan year starts, with specific required content.
- Budget for onboarding support. Employees who have never shopped Georgia Access on their own need guidance, once, at enrollment.
See our full ICHRA setup timeline for the detailed rollout plan, including the exact notice content requirements, and our eligibility guide for the affordability test itself. Before anything else, it's worth checking whether your county is one where this works at all: the national savings map takes about ten seconds to search.
If your employer just offered you an ICHRA
This guide is written for the employer side of the decision, but if you're a Thomas County employee who was just told your benefit is changing, the short version is: you'll get a fixed monthly amount and shop for your own plan on Georgia Access instead of picking from your employer's group menu. Our guide for employees walks through what to expect.
The honest limits of this data
A strong county average is not a guarantee for your business
- A benchmark comparison is not your actual renewal. The $1345.70 Thomas County figure is a small-group benchmark built from filed rates, not your specific carrier's quote for your specific group.
- A wide percentage doesn't mean every employee saves the same amount. Benchmark premiums reflect a representative 40-year-old enrollee; an older or higher-risk workforce will see a different real-world comparison.
- Metro Atlanta is a real counterexample elsewhere in the state. Fulton County currently misses the $100-a-month floor entirely at just $97.53 a month, and Dougherty County (Albany) lands much closer to Thomas at 52.4%. An employer with staff split across Georgia will see very different answers county by county.
- Rates move every plan year. A carrier entering or leaving the rating area can shift the comparison for 2027; recheck before every renewal, not just once.
- Waiving the premium tax credit is part of the deal. An employee whose ICHRA offer is deemed affordable generally cannot also claim a marketplace subsidy for that month. Model both sides before assuming the reimbursement is pure upside for the employee.
- Participation-minimum relief is a structural point, not a guarantee of enrollment. ICHRA removes the carrier-side participation percentage in most cases, but employees still have to actually use their reimbursement to buy a plan for the arrangement to do them any good.
If your renewal letter is already sitting on your desk and you're working against a deadline, it's worth a conversation before you sign: book time with our team. If you'd rather work through the mechanics on your own first, start with how ICHRA works and come back when you have questions.
How these numbers are calculated
Every county figure in this article comes from the same dataset that powers our savings map, not a survey or a sales estimate. For each county, we compare a 2026 individual-market benchmark premium — the second-lowest-cost silver plan available to a representative enrollee, the same benchmark the federal government uses to calculate premium tax credits — against a small-group benchmark premium built from comparable small-group plan filings for that rating area. Both figures come from Ideon, a licensed insurance rate-data provider, and are cross-verified against CMS public-use marketplace files before publication. A county "qualifies" for our dataset when the individual benchmark sits below the small-group benchmark by at least $100 a month; the percentage and dollar figures in this article are the gap between those two numbers, expressed as an annual per-employee figure at 12 times the monthly difference. Thomas County's population figure (46K) comes from the same underlying county dataset used across the site.
The national small-group figures (11% median for 2026 across 318 insurers; 14% median for 2027 across 295 insurers), the national insurer-participation figures (9.6 to 9.0 issuers per state; 93 to 165 single-issuer counties), the Georgia Access enrollment and carrier-participation figures, the HRA Council adoption figures, the Flowers Foods employment and headquarters figures, the Archbold staff and bed-count figures, the Thomasville Rose City designation, and the fact that Georgia has 159 counties (New Georgia Encyclopedia, citing the state's 1983 Constitution) each come from separately published, independent sources, not from our own county dataset, and describe national, statewide, company-specific, or local context rather than the Thomas-specific benchmark comparison above. We've kept these data sources clearly separate throughout this article rather than blending them into one number.
Three limitations are worth stating plainly. First, benchmark premiums are built around a representative enrollee profile, so an unusually young or unusually old workforce will see a different real-world spread than the county figure implies. Second, these are benchmark plans, not every plan on the market; an employee who chooses a richer or leaner plan than the benchmark will see a different premium, though the relative spread tends to hold directionally. Third, rates are filed and refreshed annually, so a county that qualifies for 2026 is not guaranteed to qualify for 2027 if a carrier enters or exits that market.
Questions Thomasville employers actually ask
Does ICHRA beat small-group insurance in Thomasville, Georgia?
Yes, and by a wider margin than most Georgia counties we've covered. In Thomas County, the county that contains Thomasville, the 2026 individual-market benchmark premium runs an estimated 53.3% below the small-group benchmark, about $8,610 per employee per year. That's an estimate built from public and industry rate data, not a quote. It ranks 16 of Georgia's 131 qualifying counties by percentage spread, well above the statewide qualifying average of 43.8%.
Why does Thomas County qualify by such a wide margin compared to Hall County or Fulton County?
Rate spreads move with how each rating area's carriers priced small-group and individual plans for 2026, not with a county's population or how urban it is. Thomas County's 53.3% sits well above Hall County's 24.2% (Gainesville) and far above Fulton County, which currently misses our $100-a-month floor entirely. A rural South Georgia rating area with fewer small-group carriers can produce a wider individual-versus-group gap than a dense metro county, which is exactly what's happening here.
How much can a Thomasville-area employer expect to save?
Using 2026 benchmark data, the estimated gap in Thomas County is $717.47 a month, or $8,610 a year, per employee. For a 15-person company, that's roughly $129,145 a year in aggregate estimated savings if the employer funds ICHRA contributions at the benchmark level instead of renewing small group. This is illustrative math from public rate data, not a projection of what any specific employer will actually pay.
Are Flowers Foods and Archbold Medical Center employees covered by this comparison?
Not directly, and not usefully. Flowers Foods, the Fortune 500 baking company behind brands like Nature's Own and Wonder Bread, is headquartered at 1919 Flowers Circle in Thomasville and employed about 10,300 people nationwide as of its fiscal 2025 year-end (January 3, 2026), per its 10-K filed with the SEC. Archbold, the regional health system based in Thomasville, lists about 2,700 staff members and more than 650 patient beds across its service area, per its own website. Both run large-group benefits programs that don't need this guide. This article is written for the independent clinics, contractors, and smaller employers that sit alongside them, not inside them.
Is Colquitt, Tift, Decatur, or Grady County priced the same as Thomas County?
Yes. Colquitt County (Moultrie), Tift County (Tifton), Decatur County (Bainbridge), and Grady County (Cairo) all sit in the same marketplace rating area as Thomas County and carry the identical 2026 benchmark comparison: a $628.23 individual benchmark against a $1345.70 small-group benchmark, the same 53.3% spread. In total, 18 South Georgia counties share this exact rating area, covering an estimated 440K residents. Mitchell County (Camilla) sits in a neighboring rating area with a close but not identical 52.4% spread.
Why did my 2026 or 2027 small-group renewal come in higher than I expected?
Nationally, small-group insurers filed a median proposed premium increase of 14% for 2027 across 295 insurers in all 50 states and the District of Columbia, according to the Peterson-KFF Health System Tracker (published August 6, 2026), up from an 11% median across 318 insurers for 2026 from the same source (published September 24, 2025). Separately, KFF found the average number of ACA marketplace insurers per state fell from 9.6 in 2025 to 9.0 in 2026, with 165 counties nationwide now served by only one issuer, up from 93 the year before, a shift KFF ties largely to Aetna CVS exiting 17 states and other insurer departures following the expiration of enhanced premium tax credits. Thinner competition and rising medical trend are the two forces behind most 2026 and 2027 renewal letters.
Does Georgia impose any state-specific ICHRA rules?
No. ICHRA is a federal HRA structure created by a 2019 final rule from the IRS and Treasury, the Department of Labor, and HHS (84 Fed. Reg. 28888, effective August 19, 2019, applicable to plan years beginning on or after January 1, 2020), and it works the same way in Georgia as in any other state. HealthCare.gov now also refers to the arrangement as a CHOICE Arrangement under updated federal guidance, but the underlying rules are unchanged. Georgia does run its own state-based marketplace, Georgia Access, rather than routing enrollment through HealthCare.gov, but that affects how residents shop for individual coverage, not the ICHRA rules an employer follows.
What happens to my employees' premium tax credit if I switch to ICHRA?
An employee who is offered an affordable ICHRA generally becomes ineligible for a premium tax credit for any month that offer applies, whether or not they accept it. Affordability is measured against the IRS's Required Contribution Percentage, which is 9.96% of household income for plan years beginning in 2026 (Rev. Proc. 2025-25) and rises to 10.22% for plan years beginning in 2027 (Rev. Proc. 2026-26). Model that test before you set a contribution amount.
How Georgia's 131 qualifying counties break down by savings tier
Number of counties in each savings band, 2026 plan year. Source: Ideon rate data, cross-verified against CMS public-use files.
Thomas sits in the 50-60% band, among the widest gaps in the state. Illustrative and rounded; not an offer of insurance or a guarantee of savings.
Sources
- Peterson-KFF Health System Tracker, "How Much and Why Premiums Are Going Up for Small Businesses in 2027" (Aug. 6, 2026)
- Peterson-KFF Health System Tracker, "How Much and Why Premiums Are Going Up for Small Businesses in 2026" (Sep. 24, 2025)
- KFF, "How Has Insurer Participation in the ACA Marketplaces Changed in 2026?"
- Georgia Office of Commissioner of Insurance and Safety Fire, "Georgia's 2025 Open Enrollment Period Begins as New State-Based Exchange, Georgia Access, Goes Live" (Nov. 1, 2024)
- IRS Revenue Procedure 2025-25 — Required Contribution Percentage, plan years beginning in 2026 (9.96%)
- IRS Revenue Procedure 2026-26 — Required Contribution Percentage, plan years beginning in 2027 (10.22%)
- 84 Fed. Reg. 28888 — ICHRA final rule, Departments of the Treasury/IRS, Labor, and Health and Human Services (June 20, 2019)
- HealthCare.gov, "Individual Coverage HRA" (CHOICE Arrangement) — class-size minimums and participation rules
- HRA Council, "Growth Trends for ICHRA & QSEHRA, Vol. 5" (Aug. 12, 2026)
- New Georgia Encyclopedia, "Georgia's County Governments" — 159 counties, 1983 Constitution
- Flowers Foods, Inc., Form 10-K (filed Feb. 25, 2026, for fiscal year ended Jan. 3, 2026) — headquarters address, employee count
- Archbold, "About Us" — staff count, bed count, five-county service area
- City of Thomasville, "Thomasville Designated as the State's Official Rose City"
- County-level premium comparison:
src/data/qualified_counties.json, 2026 plan year (Ideon rate data, cross-verified against CMS public-use marketplace files)