ICHRA in Kentucky 2026: 118 of 120 Counties Qualify
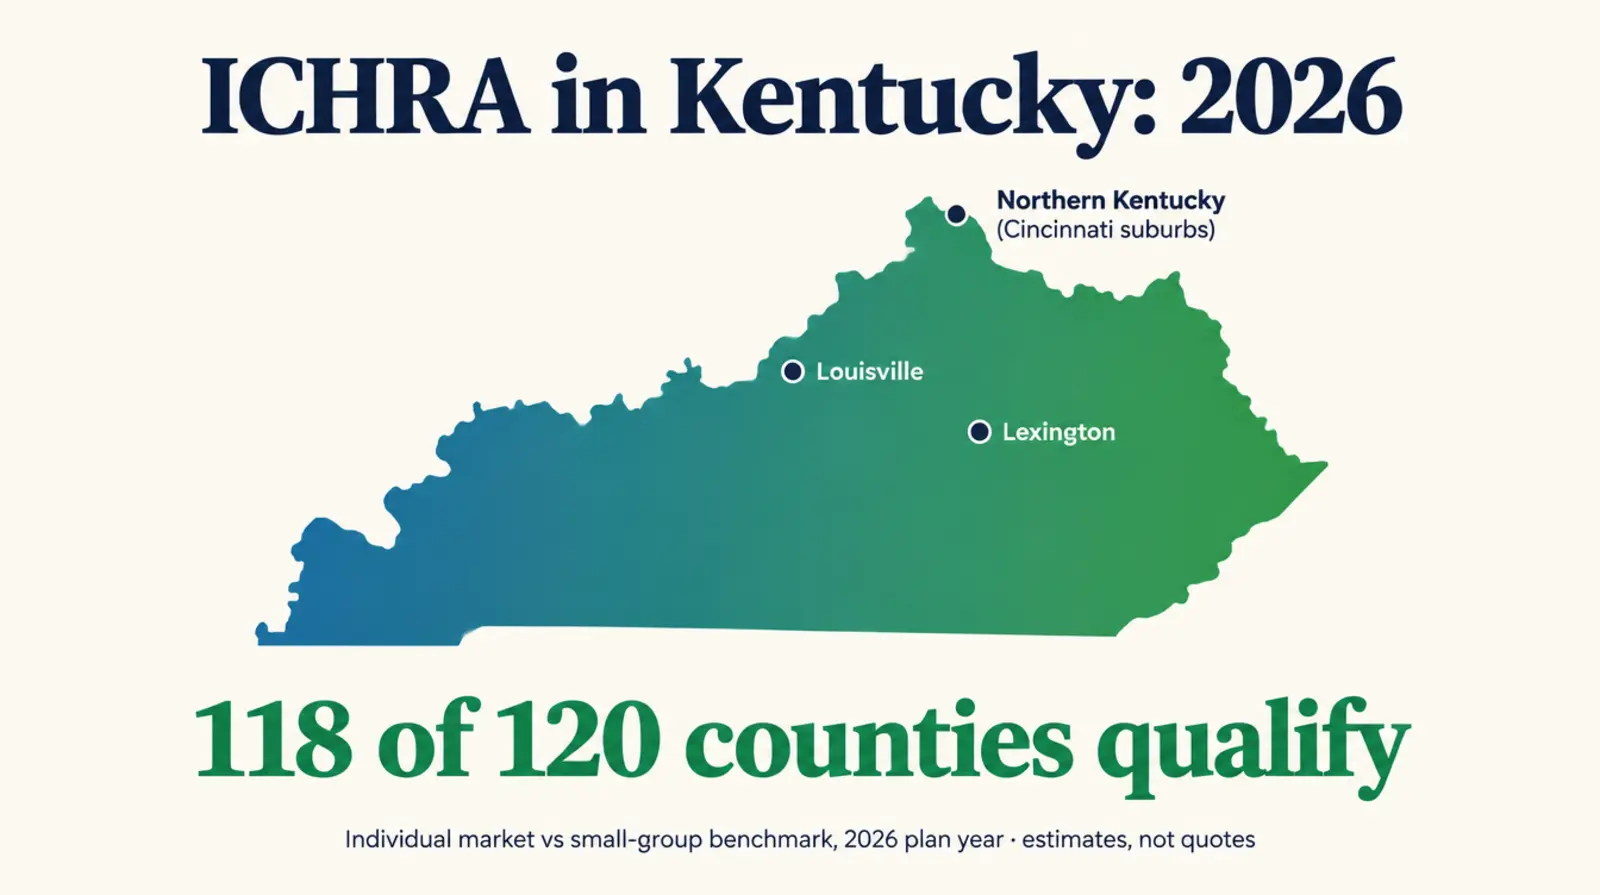
Kentucky's 2026 county data: ICHRA beats small group in 118 of 120 counties, from 7.2% to 34.8% savings. See the 2027 rate filings and the honest limits.
The short version
- ICHRA beats small-group coverage in an estimated 118 of Kentucky's 120 counties for the 2026 plan year, covering roughly 4.4M residents.
- The margin is not uniform. Boyd County, anchoring the Ashland area, qualifies at 34.8%, the widest in the state. Louisville (Jefferson County) qualifies at 27.1%, Lexington (Fayette County) at 25.2%, and Bowling Green (Warren County) at a thinner 17.1%.
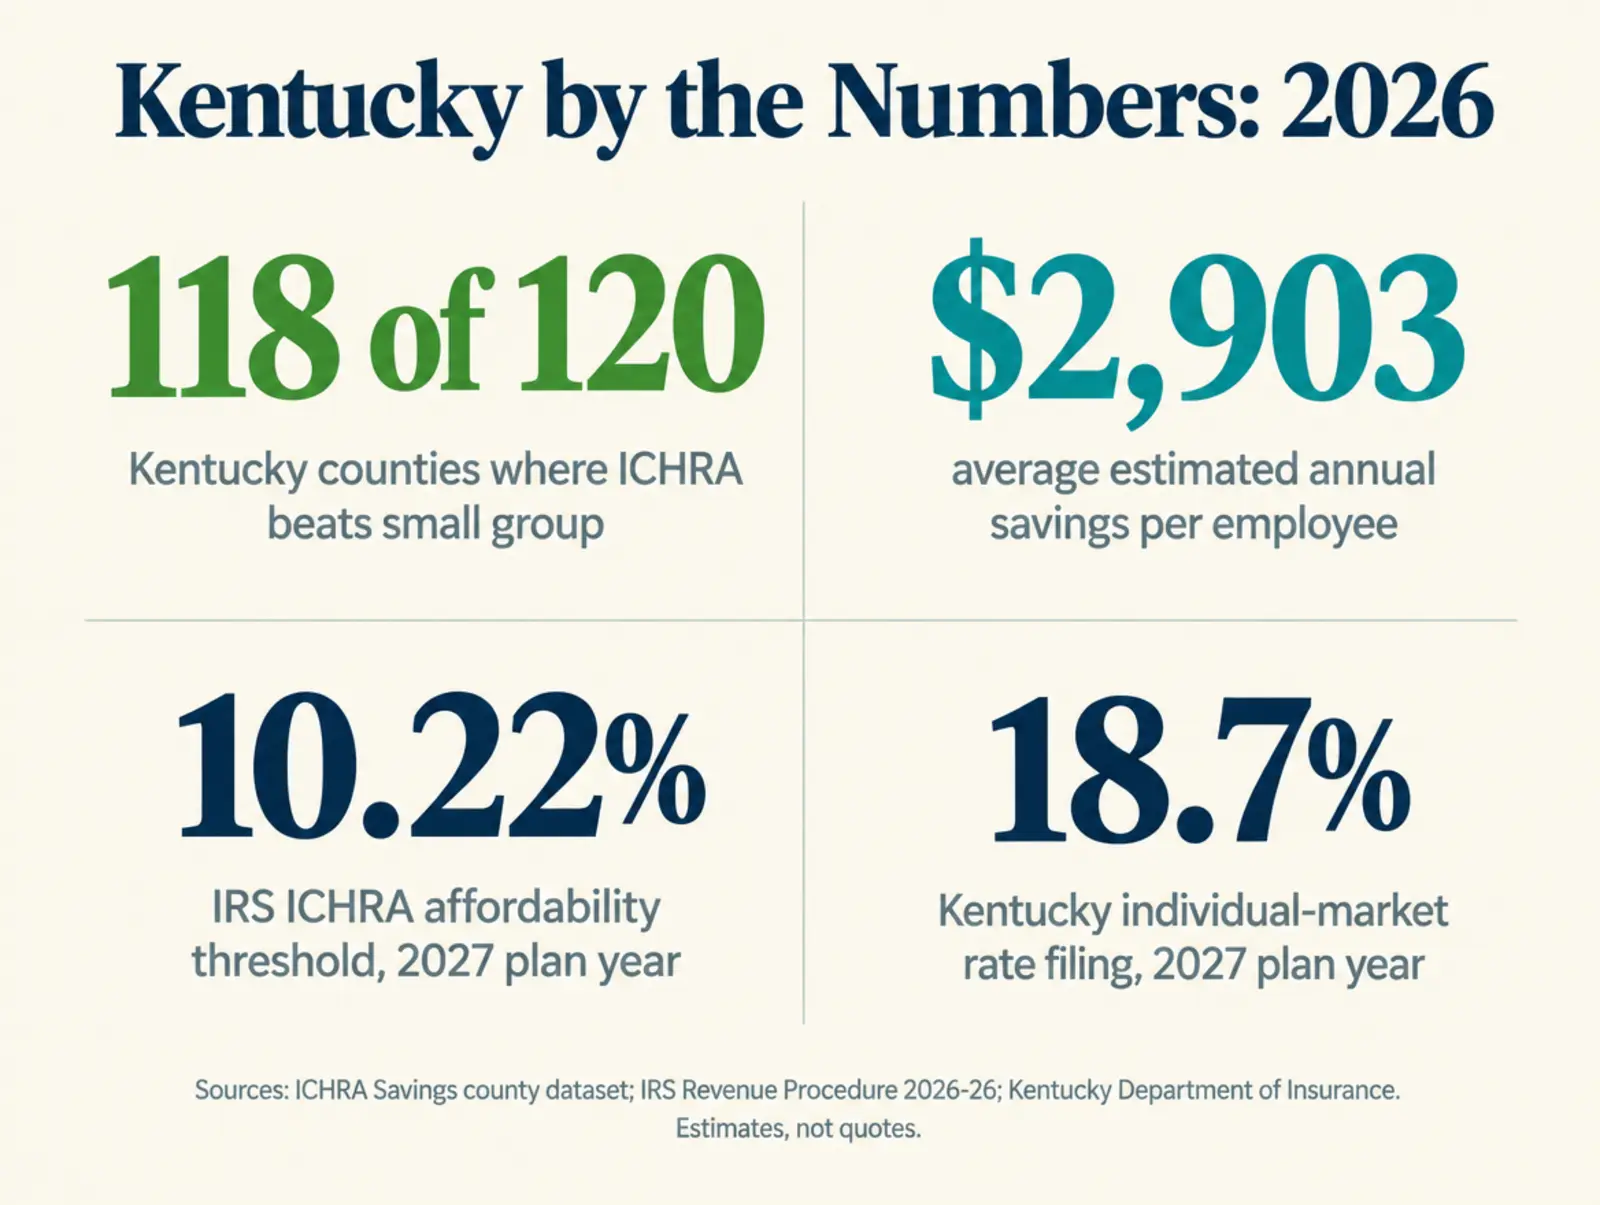
- Kentucky's individual-market carriers filed preliminary 2027 rates averaging 18.7%; small-group carriers filed averaging 10.7%. Both are requested, not approved, per Kentucky Department of Insurance filings.
- The 2027 IRS affordability threshold is 10.22% of household income, up from 9.96% for 2026 and the highest it has ever been.
- Kentucky runs its own exchange, kynect, where 2026 plan selections fell to about 89,000 from 97,374 the year before.
Does ICHRA beat small group in Kentucky?
Yes, in most of the state, though the size of the win changes a lot depending on where your employees live. An ICHRA (Individual Coverage Health Reimbursement Arrangement) currently beats traditional small-group coverage in an estimated 118 of Kentucky's 120 counties for the 2026 plan year, based on a county-by-county comparison of individual-market and small-group benchmark premiums. Those 118 counties make up about 9% of the 1309 counties nationwide where the math currently favors ICHRA, and cover nearly all of the state's population.
If you haven't worked through the general decision yet, our ICHRA vs. small group decision guide walks through the framework this article applies specifically to Kentucky. Here's what a flat "Kentucky qualifies" headline hides: the spread runs from 7.2% in a handful of counties near the Ohio River to 34.8% around Ashland in the northeast corner. A county that clears the bar by 7 points and a county that clears it by nearly 35 both "qualify." Only one of them is worth the administrative lift for most small employers.
118
Kentucky counties where ICHRA beats small group in 2026
118/120
Share of Kentucky's counties that qualify
4.4M
Kentuckians living in a qualifying county
$2,903
Average estimated savings per employee, per year
Why Kentucky's 2027 rate filings matter now
Kentucky employers are looking at another steep renewal before this year's even finishes playing out. The state's individual-market carriers have filed preliminary 2027 rate requests averaging an 18.7% increase, and small-group carriers filed averaging 10.7%, according to filings posted on the Kentucky Department of Insurance's rate-filing portal. Three carriers remain in the individual market: Molina Healthcare of Kentucky requested the steepest increase at 21.2%, WellCare Health Plans of Kentucky requested 20.7%, and Anthem Health Plans of Kentucky requested 16.91%. On the small-group side, three entities filed: two UnitedHealthcare subsidiaries at 10.84% and 10.57%, and Anthem at 10.72%.
None of these figures are final. The Kentucky Department of Insurance reviews every rate filing before approving it, and the requested numbers above can move before they take effect for January 1, 2027. Still, a filed 10.7% small-group increase, on top of whatever your last renewal already did to your budget, is the specific, dated reason an ICHRA conversation is worth having in Kentucky now rather than a vague "costs keep rising" claim.
This matters for ICHRA specifically because reimbursements under this structure track individual-market prices, not small-group prices. When small-group rates move up, as filed for Kentucky's 2027 plan year, the spread this entire strategy depends on can widen even if individual-market rates also rise, so long as they don't rise as fast. That's why every figure in this article is tied to a specific plan year, and why the underlying dataset gets rebuilt annually instead of reused.
| Metric | Kentucky | Detail |
|---|---|---|
| 2027 individual-market change (preliminary) | +18.7% average | Anthem, WellCare, Molina |
| 2027 small-group change (preliminary) | +10.7% average | Anthem, two UnitedHealthcare entities |
| Filing status | Pending | Kentucky Department of Insurance review |
| IRS affordability threshold | 10.22% of household income | 2027 plan year, national |
Filed is not final
The 2027 figures above are requested rates pending Kentucky Department of Insurance review, not approved ones. Treat 18.7% and 10.7% as the direction insurers proposed, not a locked-in number for your actual renewal.
The 2027 filings, carrier by carrier
The 18.7% individual-market average sits across a thin field: only three carriers continue selling individual coverage in Kentucky for 2027. Anthem Health Plans of Kentucky, generally the state's largest individual-market carrier, filed the smallest of the three requested increases at 16.91%. WellCare Health Plans of Kentucky filed 20.7%, and Molina Healthcare of Kentucky filed the steepest at 21.2%. On the small-group side, Anthem filed 10.72%, and two UnitedHealthcare entities filed 10.84% and 10.57% respectively.
| Carrier | Market | Requested change |
|---|---|---|
| Molina Healthcare of Kentucky, Inc. | Individual | +21.2% |
| WellCare Health Plans of Kentucky, Inc. | Individual | +20.7% |
| Anthem Health Plans of Kentucky, Inc. | Individual | +16.91% |
| UnitedHealthcare Insurance Company | Small group | +10.84% |
| UnitedHealthcare of Kentucky, Ltd. | Small group | +10.57% |
| Anthem Health Plans of Kentucky, Inc. | Small group | +10.72% |
A narrow field of three carriers on each side means a single large filer can move the state average more than it would in a bigger market. An employer or employee shopping Molina's plans in particular is looking at a materially steeper filed increase than the 18.7% headline number suggests, a reminder that "the state average" and "your actual plan" aren't the same thing.
All 118 qualifying counties, ranked
Kentucky's qualifying list isn't confined to its two big metros. It runs from Louisville and Lexington, through Bowling Green and Owensboro, up into the Northern Kentucky suburbs across the river from Cincinnati, and out across most of the state's rural counties, including the cluster around Ashland in the northeast corner that posts the widest spread in the state. Savings for 2026 run from about 7.2% to 34.8% below the small-group benchmark, averaging 23.3% across all 118 qualifying counties.
| County | Population | Savings vs. small group | Est. annual savings / employee |
|---|---|---|---|
| Jefferson County | 779,232 | 27.1% | $3,195 |
| Fayette County | 321,276 | 25.2% | $2,937 |
| Kenton County | 169,066 | 28.6% | $4,016 |
| Boone County | 136,150 | 28.6% | $4,016 |
| Warren County | 135,307 | 17.1% | $2,038 |
| Hardin County | 111,005 | 27.1% | $3,195 |
| Daviess County | 102,916 | 23.2% | $3,018 |
| Campbell County | 93,122 | 28.6% | $4,016 |
| Madison County | 92,955 | 25.2% | $2,937 |
| Bullitt County | 82,482 | 27.1% | $3,195 |
Jefferson County, Kentucky's largest county by population at roughly 779,000 residents and home to Louisville, qualifies at 27.1%. Fayette County, home to Lexington, qualifies at 25.2%. The Northern Kentucky counties of Boone, Kenton and Campbell, the Cincinnati-metro suburbs across the Ohio River, share the state's widest spread among its most populous counties at 28.6%. None of the three biggest metros, however, match Boyd County's 34.8%, the state's actual high point.
How Kentucky's 118 qualifying counties break down by savings tier
Number of counties in each savings band, 2026 plan year. Source: repo county dataset.
Illustrative and rounded; not an offer of insurance or a guarantee of savings.
See the full Kentucky savings breakdown for every qualifying county, or the national savings map to check a specific county by name.
Why Ashland saves more than Louisville or Lexington
Boyd County and a cluster of neighboring rural counties in Kentucky's northeast corner, anchored by the city of Ashland, post the state's widest spread at 34.8%. Their 2026 individual-market benchmark runs $673 a month against a small-group benchmark of $1,031, a gap of $359 a month, or $4,304 a year per employee. Jefferson County's individual-market benchmark runs $714, not far off Boyd's, against a small-group benchmark of $981. What separates Ashland's spread from Louisville's isn't a dramatically cheaper individual market; it's a comparatively higher small-group benchmark priced into the smaller Ashland-area rating region.
Lexington's Fayette County lands at 25.2%, with an individual benchmark of $726 against a small-group benchmark of $971. Bowling Green's Warren County, home to Western Kentucky University, qualifies at a much thinner 17.1%, worth an estimated $2,038 a year, a reminder that a mid-sized college city can produce a narrower spread than either big metro. Owensboro's Daviess County sits in between at 23.2%, worth an estimated $3,018 a year.
Kentucky doesn't have one ICHRA story. It has an Ashland story at 34.8%, a Louisville story at 27.1%, and a Bowling Green story at 17.1%. All three are true at once.
Mike Moore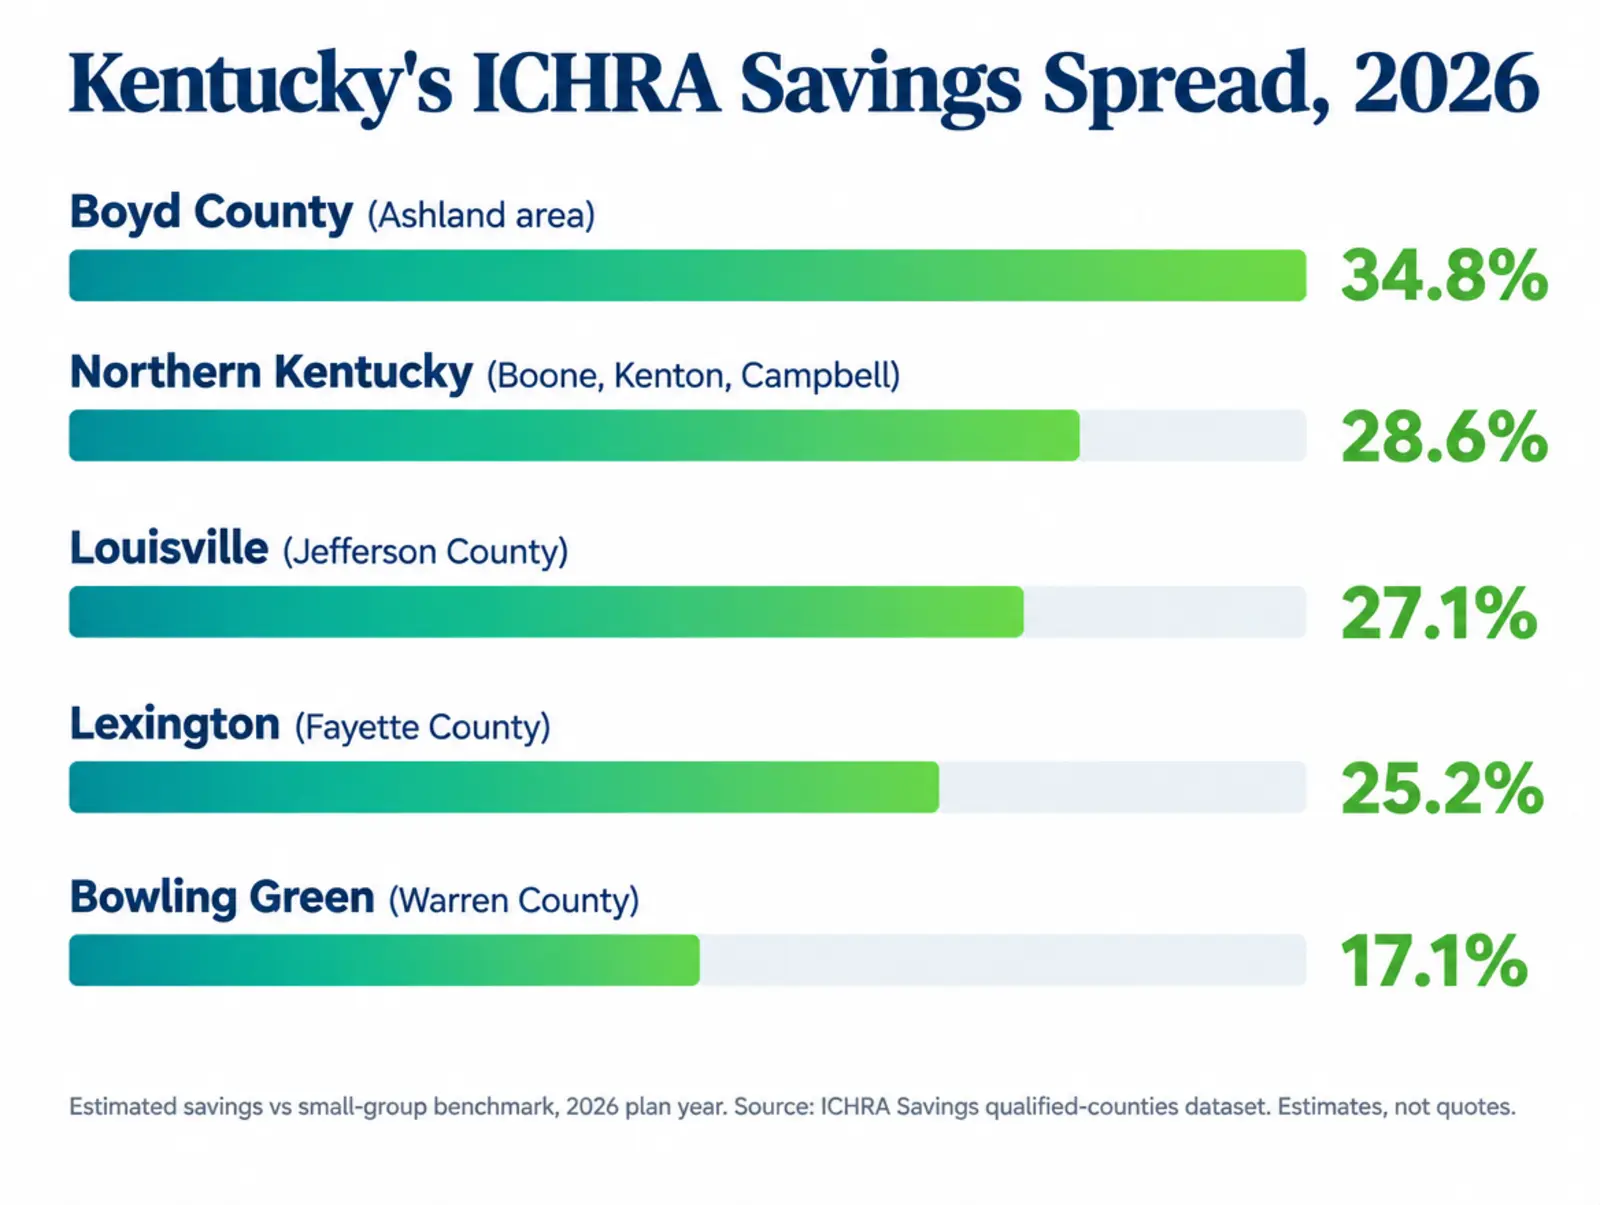
A worked example: three Kentucky cities
Here's what the county-level math looks like for a small employer with staff split across Kentucky's three largest metro areas, using real 2026 rate data. Assume a 15-employee company with 6 employees in Jefferson County (Louisville), 5 in Fayette County (Lexington), and 4 in Boone County (Northern Kentucky).
Here's the math
In Jefferson County, the 2026 individual-market benchmark runs $714 a month against a small-group benchmark of $981, a savings of $266 a month, or $3,195 a year per employee. In Fayette County, the individual benchmark runs $726 against a small-group benchmark of $971, or $2,937 a year. In Boone County, the individual benchmark runs $834 against a small-group benchmark of $1,169, or $4,016 a year.
For this hypothetical 15-person company: 6 x $3,195 (Louisville) + 5 x $2,937 (Lexington) + 4 x $4,016 (Northern Kentucky) = an estimated $49,919 a year in aggregate savings using benchmark-level ICHRA contributions across the whole workforce. This is illustrative, built on real county rate data and a hypothetical headcount split; your actual result depends on your employees' ages, exact counties, and the plans they choose.
Notice what this example does not do: claim one statewide "Kentucky saves X%" figure. That would blur the fact that the Northern Kentucky share of this workforce is worth more per employee than the Louisville share, which is itself worth more than many thinner-margin counties elsewhere in the state. Checking counties individually, not trusting a state average, is the entire point of county-level data.
The affordability test, in plain numbers
Every ICHRA has to clear the IRS's affordability test to avoid pushing an eligible employee's premium tax credit decision the wrong way. Under IRS Revenue Procedure 2026-26, the required contribution percentage for plan years beginning in 2027 is 10.22% of household income, up from 9.96% for 2026 and the highest this figure has been since the test began. In plain terms: an employer's ICHRA is affordable for an employee if that employee's own required monthly contribution toward the lowest-cost silver plan in their rating area doesn't exceed 10.22% of household income, divided by 12.
Here's the math on affordability
Take a Jefferson County employee earning $36,000 a year. Under the 2027 required contribution percentage of 10.22%, their household's monthly contribution toward the lowest-cost silver plan is considered affordable if it doesn't exceed $306.60 a month (10.22% of $36,000, divided by 12). Jefferson County's 2026 individual-market benchmark runs near $714 a month; if the employer's ICHRA contribution covers, say, $450 of it, the employee's remaining share is well under $306.60, so the ICHRA is affordable for this employee, meaning they generally must waive the premium tax credit to use it. A smaller contribution, or a lower-income employee, can flip that answer. Model this test against your actual census before setting a contribution amount, not a round number copied from last year's renewal.
Say this plainly to employees
Taking an employer's ICHRA contribution generally means an employee waives the federal premium tax credit for that month, unless the ICHRA is unaffordable under the IRS test, in which case they can decline it and keep shopping the marketplace with a subsidy instead. This isn't a detail to bury in fine print; employees deciding whether to enroll need to understand which side of that line they're on.
Kentucky runs its own exchange, and enrollment is falling
Unlike most states, Kentucky doesn't use HealthCare.gov. It runs its own state-based marketplace, kynect, which means Kentucky employees shop a state-run site rather than the federal one whether they're buying a subsidized marketplace plan or a plan funded through an ICHRA. That distinction doesn't change how ICHRA itself works, but it is the detail an employer needs to know before telling employees where to go.
Kynect's own enrollment trend is worth flagging. According to CMS's 2026 Marketplace Open Enrollment Period Public Use Files, roughly 89,000 Kentucky residents selected a plan through kynect during the open enrollment period for 2026 coverage, down from 97,374 the year before, a decline of about 8.6%. Roughly 80% of kynect's 2026 enrollees received a premium tax credit, and about 43% enrolled in a Silver plan with built-in cost-sharing reductions. Three carriers sell on kynect for 2026: Anthem, WellCare (marketed as Ambetter), and Molina.
A shrinking marketplace matters for an ICHRA rollout because it's a sign the individual market an ICHRA leans on is getting thinner in Kentucky, not thicker. Fewer enrollees generally means a narrower set of plan choices for employees shopping with their ICHRA contribution, even where the benchmark math still favors ICHRA on price. It's a reason to check plan availability in your employees' specific counties, not just the benchmark percentage, before finalizing a rollout.
Kentucky runs kynect, not HealthCare.gov
Employees enroll in an ICHRA-funded plan through the state's own exchange.
2026 enrollment fell about 8.6%
From 97,374 plan selections in 2025 to roughly 89,000 for 2026, per CMS data.
Three carriers remain statewide
Anthem, WellCare/Ambetter, and Molina sell kynect plans for 2026.
How ICHRA Savings helps
None of the county math above requires talking to anyone. The savings map lets you look up every Kentucky county by name and see the same individual-market and small-group benchmark premiums used in this article, so you can check whether your workforce sits inside a strong-margin county like Boyd, a thinner one like Montgomery, or somewhere closer to the state average before spending time on anything else. Beyond the map, we help employers design and set up an ICHRA: building employee classes correctly, modeling affordability against your real census instead of a rule of thumb, and getting the required employee notice right and on time. We don't pick your employees' plans for them; that choice, including which kynect carrier and network to use, stays with each person buying their own coverage. Our part is the budget, the design, and the compliance scaffolding around it.
Before anything else, check whether your county is one where this works well: https://ichrasavings.com/ichra-savings-map/. A few minutes there tells you whether your Kentucky workforce lands closer to Ashland's 34.8% or Bowling Green's 17.1%.
If your renewal letter is already in hand and you're working against a deadline, it's worth a conversation: https://ichrasavings.com/book.
One more wrinkle worth flagging for Kentucky specifically: the state shares a border with seven others, Ohio and Indiana to the north, Illinois and Missouri to the west, Tennessee to the south, and Virginia and West Virginia to the east. The Northern Kentucky counties covered in this article, Boone, Kenton and Campbell, sit in the same labor market as Cincinnati, Ohio, just across the river, and it's common for a single employer in that corridor to have staff living on both sides of the state line. Ohio runs its own rate filings and its own set of qualifying counties on our savings map, not a mirror of Kentucky's numbers, so an employee who lives in Cincinnati rather than Covington needs their own county looked up separately. The same applies along the Ohio River toward Huntington, West Virginia, or across the Mississippi-adjacent corridor toward southern Illinois. Check every employee's actual county of residence, not the state your office happens to sit in.
What actually changes for your employees
An ICHRA shifts the plan-picking decision away from the employer and onto each employee, and that shift is worth describing plainly before anyone rolls one out. Under a traditional small-group plan, an employer (often with a broker's help) picks one or a handful of plans, and employees choose among those options or go without. Under an ICHRA, the employer sets a monthly reimbursement amount per employee class, and each employee shops the individual market, in Kentucky's case through kynect, for whatever plan fits their household, then gets reimbursed up to the set amount for substantiated premium costs.
That means an employee with a chronic condition can choose a richer plan with a lower deductible by paying more out of pocket than the ICHRA contribution covers, while a healthy employee who rarely sees a doctor can choose a cheaper plan and pocket the difference by paying less. It also means the employer stops being the one who decides which network a given employee's doctor has to be in, which can matter a great deal in a state where carrier participation varies meaningfully by county. The tradeoff is real: employees who have always had a plan picked for them need guidance the first time they shop kynect on their own, which is why a one-time enrollment walkthrough is worth budgeting for even though the ICHRA itself requires no ongoing plan administration from the employer.
Setting up an ICHRA in Kentucky
Kentucky doesn't add state-specific ICHRA rules on top of the federal framework. The same IRS, DOL and HHS final rule that governs ICHRA everywhere applies here, and the setup sequence is the same as in any other state:
- Pull your census by county, not by office address. A company headquartered in Louisville with staff in Lexington or the Northern Kentucky suburbs has a materially different savings story per location.
- Check each employee's county on the savings map. A 34.8% county and a 7.2% county both "qualify," but they're not the same decision.
- Model affordability using the 2027 threshold. At 10.22% of household income, this is the number that decides whether your ICHRA contribution counts as affordable for a given employee.
- Define employee classes carefully, if you use them. An employee class is a group defined by an IRS-permitted objective factor, such as full-time versus part-time status or geographic location. Class rules carry minimum-size requirements and can't offer the same class a choice between ICHRA and group coverage.
- Send the required notice on time. Under the federal ICHRA final rule, eligible employees generally need written notice at least 90 days before the plan year starts, per CMS guidance on Individual Coverage HRAs.
- Budget for onboarding help. Employees shopping kynect for the first time need guidance once, at enrollment, especially with only three carriers competing statewide and availability varying by county.
See our full ICHRA setup timeline for the detailed rollout plan, including the exact notice content requirements, and our guide to ICHRA employee classes if your Kentucky workforce spans more than one rating area.
Run your counties first
Before scheduling a single meeting, look up every county where you have Kentucky employees on the savings map. If your workforce sits mostly in Warren, Montgomery or another thin-margin county, you have a more marginal conversation ahead than an employer centered on Ashland, Louisville or the Northern Kentucky suburbs.
The honest limits of this data
Read this before you commit
- Two Kentucky counties don't clear the bar at all. The 118-of-120 figure means a small number of counties show a small-group benchmark at or below the individual-market one; an ICHRA isn't the cost-saving move there on this benchmark comparison.
- "Qualifies" isn't one tier. Montgomery and Harrison Counties clear the bar by about $70 a month per employee, thin enough that a small employer should weigh it against the administrative cost of running the program correctly.
- Rates move every plan year. With 2027 individual-market filings already up an average of 18.7% and small-group filings up 10.7%, next year's spread could widen or narrow from this year's; recheck before every renewal.
- Kynect's shrinking enrollment is a market signal, not a pricing one. A 2026 enrollment drop to about 89,000 doesn't change the benchmark math in this article, but it's worth watching for plan-choice availability in thinner counties.
- These are benchmark comparisons, not a guarantee for your specific workforce. Model your actual census, ages and plan choices before committing.
How these numbers are calculated
Every county figure in this article comes from the same dataset that powers our savings map, not a survey or a sales estimate. For each of Kentucky's 120 counties, we compare a 2026 individual-market benchmark premium, the second-lowest-cost silver plan available to a representative 50-year-old enrollee, against a small-group benchmark premium built from comparable small-group plan filings for that county's rating area. A county "qualifies" when the individual benchmark sits below the small-group benchmark; the percentage and dollar savings figures here are the gap between those two numbers, expressed as an annual per-employee figure at 12 times the monthly difference. The separate 2027 rate-filing figures come directly from the Kentucky Department of Insurance's rate-filing portal and are not reflected in the county-level qualifying dataset above, which uses the 2026 benchmark comparison described here.
Three limitations are worth stating plainly. First, benchmark premiums are built around a representative enrollee profile, so an unusually young or unusually old workforce will see a different real-world spread than the county average implies. Second, these are benchmark plans, not every plan on the market; an employee who chooses a richer or leaner plan will see a different premium, though the relative spread tends to hold directionally. Third, rates are filed and refreshed annually, so a county that qualifies for 2026 is not guaranteed to qualify for 2027 once the current filings are approved. We rebuild this dataset each plan year rather than reusing prior-year figures, and we recommend employers do the same before every renewal.
Questions Kentucky employers actually ask
Does ICHRA beat small-group insurance everywhere in Kentucky?
Why does the Ashland area save more than Louisville or Lexington?
What's happening with Kentucky's 2027 health insurance rates?
What is the 2027 ICHRA affordability percentage, and why does it matter in Kentucky?
Does Kentucky use HealthCare.gov or its own marketplace?
Is a county that only qualifies at 7.2% worth pursuing?
Does Kentucky add any state-specific ICHRA rules?
Where can I check whether my specific Kentucky county qualifies?
What happens if an employee lives just across the state line from Kentucky?
Can a Kentucky business with just a few employees offer an ICHRA?
Sources
- Kentucky Department of Insurance, 2027 health insurance rate filings (pending)
- ACA Signups, "2027 Rate Changes - Kentucky: +18.7% indy mkt, +10.7% sm. group" (compiled from Kentucky DOI filings)
- IRS, Revenue Procedure 2026-26 (2027 ACA/ICHRA required contribution percentage, 10.22%)
- CMS.gov, "2026 Marketplace Open Enrollment Period Public Use Files" (Kentucky/kynect plan selections)
- healthinsurance.org, "Kentucky health insurance marketplace" (compiling CMS kynect enrollment figures)
- Kentucky Secretary of State, "Counties" (120-county count)
- CMS, "Individual Coverage HRAs" (90-day employee notice requirement)
- Federal Register, "Health Reimbursement Arrangements and Other Account-Based Group Health Plans" (84 Fed. Reg. 28888, June 20, 2019; the ICHRA final rule)
- HealthCare.gov, "Individual coverage HRAs"
- ICHRA Savings qualified-counties dataset (
src/data/qualified_counties.json), 2026 plan year