ICHRA in North Carolina 2026: Mecklenburg Wins, Most Lag
North Carolina's rates rose an estimated 28.6% for 2026. See which of its 100 counties beat small group with an ICHRA estimate, and why most don't.
The short version
- ICHRA beats small-group coverage by our $100-a-month bar in an estimated 21 of North Carolina's 100 counties for 2026, covering about 5,356,994 residents.
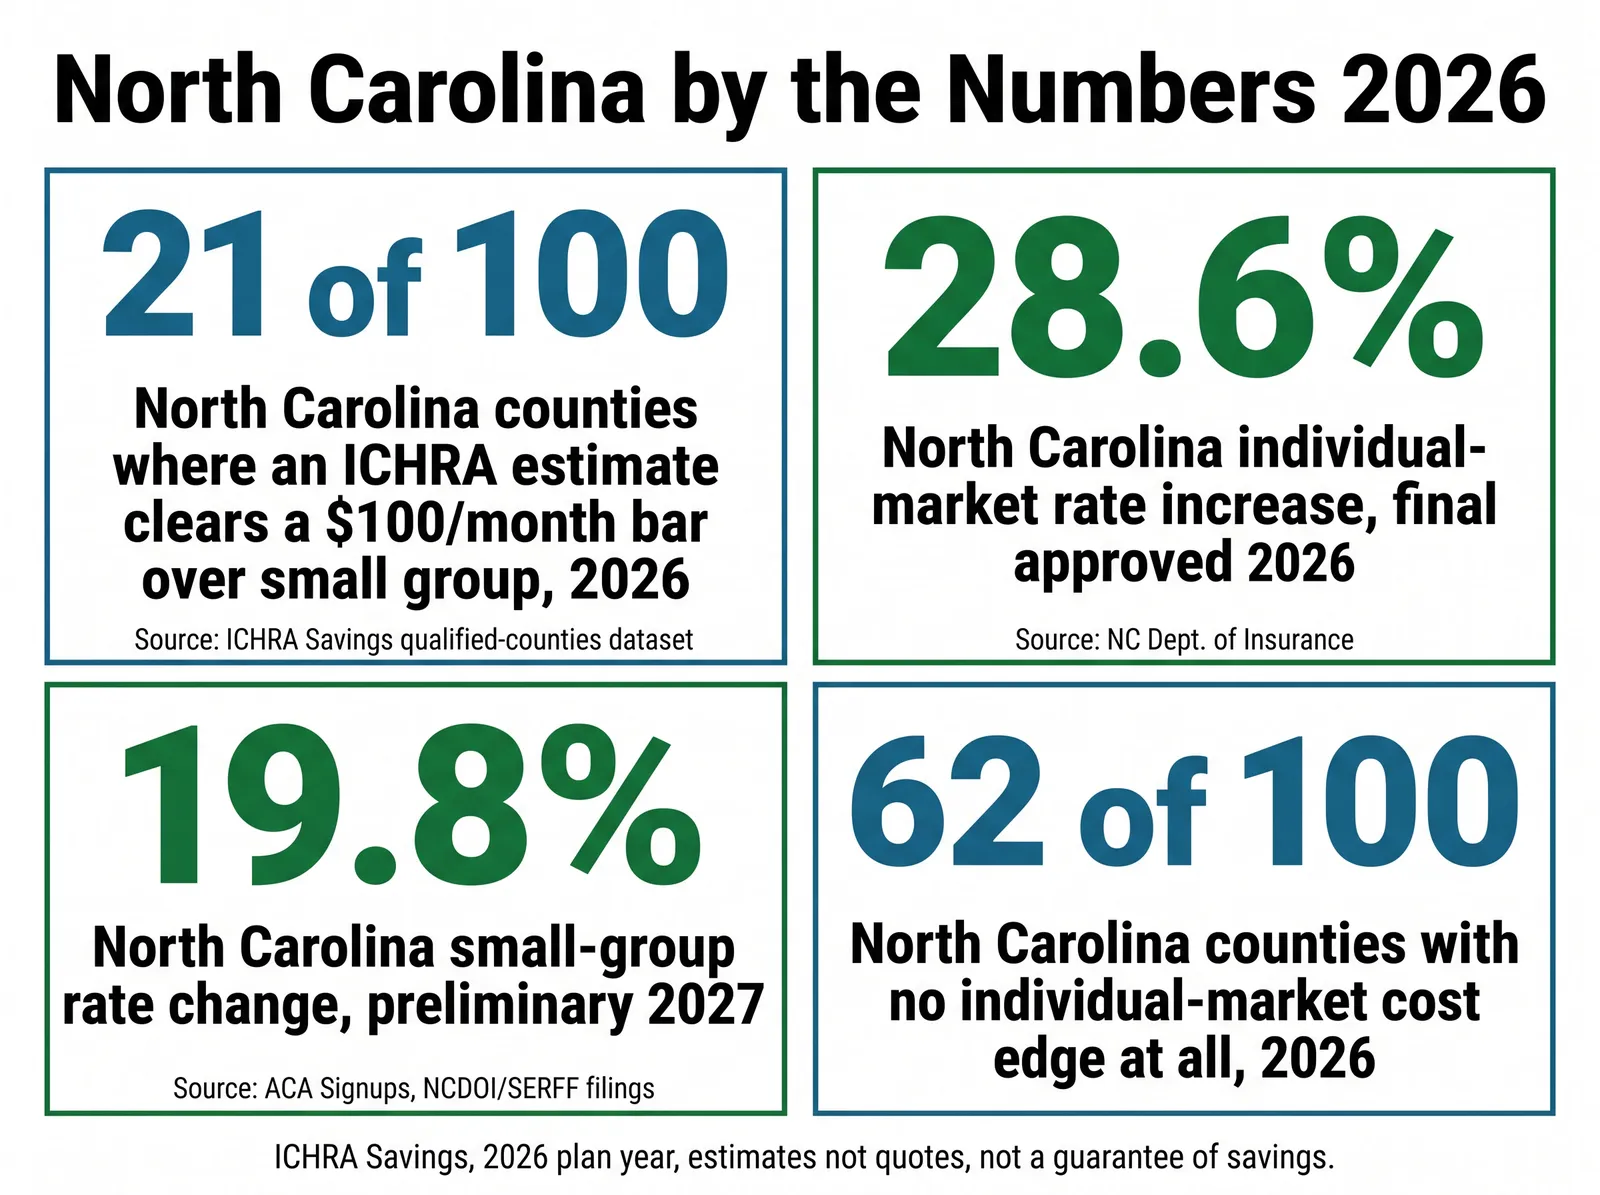
- Another 17 counties show a smaller, positive discount, and 62 counties (including Buncombe, New Hanover and Cumberland, home to Asheville, Wilmington and Fayetteville) show no individual-market edge at all.
- North Carolina's individual-market rates rose an approved 28.6% for 2026 per the state Department of Insurance, corroborated by an independent 27.7% weighted-average calculation from ACA Signups. Preliminary 2027 filings run 14.9% for individual coverage and 19.8% for small group.
- The 2026 IRS affordability threshold is 9.96% of household income: the number that decides whether an employee's ICHRA is considered affordable.
Does ICHRA beat small group in North Carolina?
In about a fifth of the state, clearly yes. In most of it, not really, at least not as a cost play. An ICHRA (Individual Coverage Health Reimbursement Arrangement) clears our county-qualifying bar, a monthly benchmark gap of at least $100 per employee, in an estimated 21 of North Carolina's 100 counties for the 2026 plan year. Those 21 counties make up about 2% of the 1309 counties nationwide where the math currently favors ICHRA, and cover roughly 5,356,994 residents.
If you haven't worked through the general decision yet, our ICHRA vs. small group decision guide walks through the framework this article applies specifically to North Carolina. Here's the part a simple "check your county" headline can undersell: it isn't a state where most counties qualify and a handful don't, the way it works in states like South Carolina or Ohio. It's closer to the reverse. Only 21 of 100 counties clear the bar, 17 more show a thin, positive gap that doesn't clear it, and 62 counties, a clear majority of the state, show no individual-market price advantage over small group at all in this dataset for 2026. That distribution, not a single statewide percentage, is the actual finding here.
Compare that to states we've already covered in this series: South Carolina qualifies in 42 of its 46 counties, and Georgia qualifies in 130 of its 159. North Carolina isn't in that camp; its 21-of-100 ratio sits much closer to Texas, where just 2 of 254 counties qualify, than to South Carolina or Georgia. It's still a meaningfully better result than Florida, where our 2026 dataset shows no county clearing the individual- versus-small-group gap at all. What separates North Carolina from Texas is where its qualifying counties happen to sit: under three of the state's biggest job centers, so the 21 counties that do clear the bar carry far more combined population than a short qualifying list usually would.
21 of 100
North Carolina counties where ICHRA clears our $100/mo bar in 2026
62 of 100
Counties with no individual-market cost edge at all
16.6%
Average estimated savings across qualifying counties
$1,678
Average estimated savings per employee, per year
Why North Carolina's rates keep climbing
North Carolina small-group employers are absorbing another steep round of increases, and the individual market moved even more. The North Carolina Department of Insurance approved a final average rate increase of 28.6% for 2026 individual ACA marketplace plans, announced October 29, 2025, with carrier-level individual increases ranging from 16.88% to 36.4% and small-group increases ranging from 12.66% to 17.5%. A second, independent tally from ACA Signups, built from the same underlying NCDOI and SERFF rate filings but weighted differently across carriers, calculated the final 2026 individual-market increase at 27.7%, close enough to the state's own 28.6% figure to corroborate the scale of the jump from two separate calculations.
Preliminary 2027 filings run a weighted 14.9% increase for the individual market and an 19.8% increase for the small-group market, per ACA Signups' compilation of North Carolina DOI and SERFF filings. On the individual side, requested increases include Ambetter at 8.5%, Blue Cross Blue Shield of North Carolina at 17.7%, and Oscar Health at 18.0%. Cigna is discontinuing individual marketplace coverage in North Carolina entirely for 2027, affecting an estimated 16,006 enrollees who will need to shop a new carrier during that year's open enrollment.
Filed is not final
The 2027 figures above are requested rates, not approved ones. North Carolina's Department of Insurance reviews every filing before approving anything, and the final number can move in either direction, the same way most states' preliminary filings shift once regulatory review closes.
| Source | Individual market | Small group market |
|---|---|---|
| NC Dept. of Insurance (direct) | 28.6% | 12.66% to 17.5% (range) |
| ACA Signups (NCDOI/SERFF compilation) | 27.7% | not separately reported |
None of this is happening in a vacuum. When individual-market rates rise faster than small-group rates, the spread this entire strategy depends on can narrow, and North Carolina's 2027 preliminary filings show exactly that pattern starting to show up: individual coverage requesting 14.9% while small group requests 19.8%, which would widen the gap back out if both get approved roughly as filed. That's exactly why every figure in this article is tied to a specific plan year, and why we rebuild the underlying county dataset every year rather than reusing prior numbers.
All 100 counties, and why only 21 clear the bar
North Carolina has 100 counties, more than all but one other state, spread across three very different regions: the mountainous west, the mid-state Piedmont anchored by Charlotte, Greensboro and the Triangle, and the coastal plain running to Wilmington and the Outer Banks. The qualifying-county pattern tracks that geography closely: every one of the 21 counties that clears our bar sits in the Piedmont, in or near the Charlotte, Triad, or Triangle metro areas. Savings for 2026 run from 14.5% up to 20.0% below the small-group benchmark among qualifying counties, averaging 16.6%.
| County | Population | Savings vs. small group | Est. annual savings / employee |
|---|---|---|---|
| Wake County | 1,132,103 | 16.1% | $1,586 |
| Mecklenburg County | 1,115,403 | 20.0% | $2,062 |
| Guilford County | 539,557 | 14.5% | $1,444 |
| Forsyth County | 383,739 | 14.5% | $1,438 |
| Durham County | 325,101 | 17.0% | $1,736 |
| Union County | 240,109 | 20.0% | $2,062 |
| Cabarrus County | 226,396 | 20.0% | $2,062 |
| Johnston County | 219,042 | 16.1% | $1,586 |
| Alamance County | 171,779 | 17.0% | $1,736 |
| Davidson County | 169,498 | 14.5% | $1,438 |
Wake County, home to Raleigh and the state's most populous county, qualifies at 16.1%. Mecklenburg County, home to Charlotte and a close second in population, qualifies wider, at 20.0%, tied for the strongest margin in the state. Guilford County (Greensboro) and Forsyth County (Winston-Salem), the anchors of the Piedmont Triad, both clear 14.5%. Durham County clears 17.0%. Every one of the state's ten most populous qualifying counties clears at least 14.5%, which means the qualifying list isn't a collection of sparsely populated rural counties; it's built around the state's biggest job centers.
How North Carolina's 100 counties break down
Number of counties in each band, 2026 plan year. Source: repo county dataset.
Illustrative and rounded; not an offer of insurance or a guarantee of savings.
See the full North Carolina savings breakdown for every qualifying county, or the national savings map to check a specific county by name.
Why Asheville, Wilmington and Fayetteville don't qualify at all
Buncombe County (Asheville), New Hanover County (Wilmington) and Cumberland County (Fayetteville) don't appear anywhere in our qualifying-counties dataset for the 2026 plan year. That's not a data gap; it means their 2026 individual-market benchmark premium isn't lower than their small-group benchmark premium at all, so there's no spread for an ICHRA contribution to capture as savings. The same is true for 59 other North Carolina counties, 62 in total, a clear majority of the state's 100 counties.
The 17 counties that do show a positive gap but fall short of our $100-a-month bar sit mostly along the western edge of the qualifying region, a transition zone between the Piedmont counties where ICHRA clears the bar and the mountain and coastal counties where it doesn't show any edge at all. Surry County, the thinnest margin of any county with a positive number, clears just 1.4%, worth about $141 a year per employee. Wilkes County sits close behind at 2.0%.
Zoom out and the pattern maps onto North Carolina's geography almost exactly. The state splits into three bands running roughly west to east: the Blue Ridge and Smoky Mountains around Asheville and Boone, the Piedmont plateau running from Charlotte through Greensboro, Winston-Salem, Durham and Raleigh, and the coastal plain stretching to Wilmington, Greenville and the Outer Banks. Every one of the 21 qualifying counties sits in that middle band. The mountain counties and the coastal counties, two regions that between them hold a large share of the state's population and most of its fastest-growing relocation markets, currently show either a thin, sub-bar discount or none at all. An employer headquartered in the Piedmont with a satellite office or a cluster of remote hires on either coast or in the mountains should expect the ICHRA cost case to weaken, sometimes to zero, the farther that workforce sits from the I-85/I-40 corridor.
North Carolina doesn't have one ICHRA story. It has a Mecklenburg County story at 20.0%, a Surry County story at 1.4%, and an Asheville story where the number is effectively zero. All three are true at once, in the same state, in the same plan year.
Mike Moore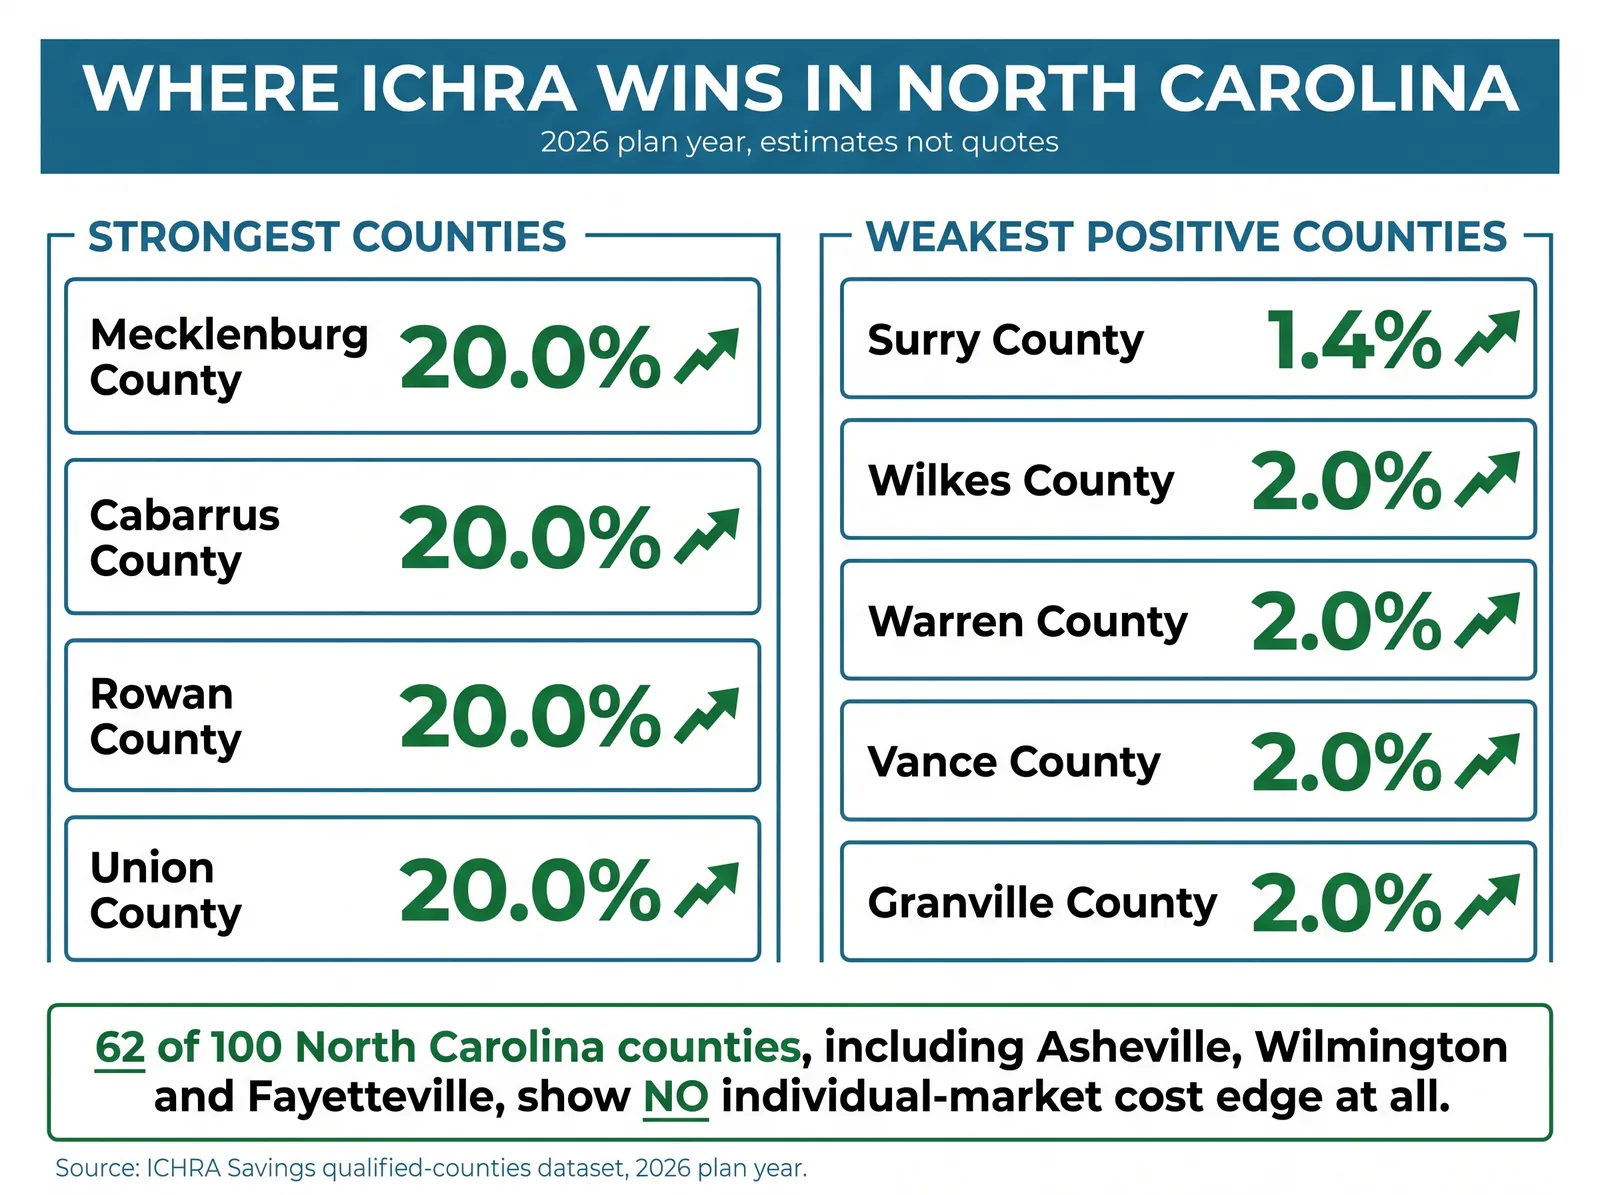
A worked example: Mecklenburg County versus Buncombe County
Here's what the county-level math actually looks like for a small employer with a split North Carolina workforce, using real 2026 rate data for two counties at opposite ends of the state's picture. Assume a 20-employee company headquartered in Charlotte with 14 employees in Mecklenburg County and 6 employees working remotely from Asheville, in Buncombe County.
Here's the math
In Mecklenburg County, the 2026 individual-market benchmark premium runs $688 a month against a small-group benchmark of $860, a savings of $172 a month, or $2,062 a year per employee. In Buncombe County, there's no equivalent figure to plug in: it doesn't appear in the qualifying dataset at all, meaning the 2026 individual-market benchmark there isn't below the small-group benchmark.
For this hypothetical 20-person company: 14 employees x $2,062 (Mecklenburg) + 6 employees x $0 in benchmark savings (Buncombe) = an estimated $28,867 a year in aggregate estimated savings, entirely from the Charlotte side of the workforce. The Asheville employees would still get a portable, tax-free ICHRA contribution under this design, just not one that's justified primarily as a discount versus small group; there, the case rests on flexibility, no participation minimum, and offering something at all rather than on the benchmark arithmetic. This is an illustrative estimate using real county rate data and a hypothetical headcount split; your actual result depends on your employees' ages, exact counties and the plan levels they choose.
Notice what this example does not do: claim a single statewide "North Carolina saves X%" figure, or pretend the Asheville side of the workforce doesn't exist. A headline like that would erase the fact that six of the twenty employees in this example aren't driving any of the estimated savings at all. Checking counties individually, not trusting a state average, is the entire argument for county-level data, and North Carolina is one of the sharper examples of why it matters, because a majority of its counties fall on the "no edge" side of the line.
The affordability test, in plain numbers
Every ICHRA has to clear the IRS's affordability test to avoid pushing an eligible employee's premium tax credit decision the wrong way. Under IRS Revenue Procedure 2025-25, the required contribution percentage for plan years beginning in 2026 is 9.96% of household income. In plain terms: an employer's ICHRA is considered affordable for an employee if that employee's own required monthly contribution toward the lowest-cost silver plan in their rating area doesn't exceed 9.96% of their household income, divided by 12.
Here's the math on affordability
Take a Mecklenburg County employee earning $36,000 a year. Under the 2026 required contribution percentage of 9.96%, their household's monthly contribution toward the lowest-cost silver plan is considered affordable if it doesn't exceed $298.80 a month (9.96% of $36,000, divided by 12). Mecklenburg County's 2026 individual-market benchmark premium runs near $688 a month; if the employer's ICHRA contribution covers, say, $260 of it, the employee's remaining share is under $298.80, so the ICHRA is affordable for this employee, meaning they must waive the premium tax credit to use it. A smaller contribution can still clear the line for a mid-income employee; a much smaller one, or a lower-income employee, can flip the answer. Modeling this test against your actual census, not a rule of thumb, has to happen before you set a contribution amount.
The subsidy trade-off, stated plainly
Taking an ICHRA is not free money layered on top of a marketplace subsidy. Under the federal rule that created ICHRA (26 CFR § 1.36B-2(c)(3)(i)(B), part of the joint Treasury, Labor, and HHS final rule at 84 Fed. Reg. 28888): if an employer's ICHRA offer is considered affordable, the employee is generally treated as having access to affordable employer coverage, and isn't eligible for the premium tax credit on marketplace coverage, whether or not they actually use the HRA. If the offer isn't considered affordable, the employee can generally choose between the ICHRA and the premium tax credit, but not both: to claim the credit, they have to decline the ICHRA offer entirely.
Say this plainly to employees
Taking an employer's ICHRA contribution generally means an employee waives the federal premium tax credit for that month, unless the ICHRA is unaffordable under the IRS test, in which case they can decline it and keep shopping the marketplace with a subsidy instead. Enhanced federal premium tax credits expired at the end of 2025 and the underlying 400% federal poverty line subsidy cliff is back for 2026, a separate topic we cover in full in our ACA subsidy cliff guide, which makes an employer-funded ICHRA contribution a more meaningful offer for higher-earning North Carolina employees than it was when broader subsidies were on the table, and a more consequential decision to explain clearly to every affected employee.
Why more North Carolina employers are looking at this now
North Carolina's rate filings aren't happening in a vacuum. The HRA Council, an industry association that aggregates anonymized enrollment data from 17 member organizations, released its newest annual report on August 12, 2026: Growth Trends for ICHRA & QSEHRA, Vol. 5. It found that more than 20,000 US businesses now offer ICHRA or QSEHRA, covering at least 500,000 employees nationally as of early 2026. Among small employers, more than two-thirds of those offering ICHRA, and 93% of those newly offering QSEHRA in 2026, had previously offered no health coverage at all. Applicable Large Employers were the fastest-growing segment, more than doubling their average ICHRA adoption since the prior year, and more than half of enrollments nationally, on- and off-exchange, are by employees under 45.
That distinction matters for a North Carolina employer weighing this for the first time. On the current individual marketplace, the state's 2026 open enrollment period saw 761,457 plan selections, down sharply from 975,110 during the 2025 open enrollment period, a 21.9% year-over-year decline, according to KFF's Marketplace Enrollment Snapshot for the 2026 open enrollment period. North Carolina uses HealthCare.gov as its marketplace platform in both years, so that drop reflects real people leaving the individual market, not a technical platform change; it's also a steeper decline than most states posted for the same period. For most small businesses in the state's qualifying counties, the realistic comparison isn't "ICHRA versus our current group plan." It's "ICHRA versus offering nothing," which is a much easier case to make when individual coverage is already getting harder to hold onto and small-group filings are up an average 19.8% for 2027. The IRS, DOL and HHS final rule that created ICHRA in 2020 sets no employer size minimum at all; a single-employee company can offer one on the same terms as a 500-person company, part of why adoption keeps climbing fastest among the smallest employers in the HRA Council's data.
New coverage, not always a switch
Two-thirds-plus of 2026 small-business ICHRA adopters had never offered coverage before.
Large-employer adoption is accelerating
ALE ICHRA adoption more than doubled on average year over year, per the HRA Council.
North Carolina marketplace enrollment is falling fast
Plan selections dropped 21.9% for 2026, per KFF, one of the sharper declines nationally.
How ICHRA Savings helps
None of the county math above requires talking to anyone. The savings map lets you look up every North Carolina county by name and see the same individual-market and small-group benchmark premiums used in this article, so you can check whether your specific workforce sits inside a strong-margin county like Mecklenburg or Cabarrus, a thin-margin one like Surry County, or one of the 62 that show no edge at all, before you spend time on anything else. Beyond the map, we help employers design and set up an ICHRA: building employee classes correctly, modeling affordability against your real census instead of a rule of thumb, and getting the required employee notice right and on time. We don't pick your employees' plans for them; that decision, and the choice of network, stays with each person buying their own coverage. Our part is the budget, the design and the compliance scaffolding around it.
Before anything else, check whether your county is one where this works well: https://ichrasavings.com/ichra-savings-map/. Ten minutes there tells you whether the rest of this process is worth starting on cost grounds, and whether your county lands closer to Mecklenburg's 20.0% or Asheville's effectively zero.
One more wrinkle worth flagging for North Carolina specifically: the state's qualifying counties cluster tightly around Charlotte, the Triad and the Triangle, while its mountain and coastal counties, popular relocation destinations for remote workers, currently show no edge. An employer with staff scattered across the state, or across state lines toward Virginia or South Carolina, needs each employee's actual county checked individually rather than assuming "North Carolina" means one answer.
Setting up an ICHRA in North Carolina
North Carolina doesn't add state-specific ICHRA rules on top of the federal framework. The same IRS, DOL and HHS final rule that governs ICHRA everywhere applies here, and the setup sequence is identical to any other state:
- Pull your census by county, not by office address. A company headquartered in Charlotte with field or remote staff in Asheville, Wilmington or Raleigh has a materially different savings story per location, and in North Carolina, that story can go from a real discount to none at all.
- Check each employee's county on the savings map. Don't assume a statewide average applies; a 20.0% county and a county with no edge both technically sit in "North Carolina," but they aren't the same decision.
- Model affordability using the 2026 threshold. At 9.96% of household income, the required contribution percentage sets how much an ICHRA contribution needs to cover to count as affordable.
- Define employee classes carefully, if you use them. An employee class is a group defined by an objective factor the IRS permits, such as full-time versus part-time status, geographic location, or salaried versus hourly work. Class rules carry minimum-size requirements and cannot offer the same class a choice between ICHRA and group coverage.
- Send the required notice on time. Under 26 CFR § 54.9802-4(c)(6)(i)(A), eligible employees generally need written notice at least 90 calendar days before the plan year begins, with specific required content about the offer and its effect on subsidy eligibility.
- Budget for onboarding support. Employees who have never shopped North Carolina's individual marketplace on their own need guidance, once, at enrollment, especially with several carriers exiting or reducing participation in the state's individual market for 2027.
See our full ICHRA setup timeline for the detailed rollout plan, including the exact notice content requirements, and our guide to ICHRA employee classes if your North Carolina workforce spans more than one region of the state.
Run your counties first
Before scheduling a single meeting, look up every county where you have employees on the savings map. If your North Carolina workforce sits mostly outside the Charlotte, Triad and Triangle corridor, you have a different, more marginal conversation ahead than an employer centered on Mecklenburg, Wake, Guilford or Forsyth Counties.
The honest limits of this data
Read this before you commit
- Most of the state shows no edge at all. 62 of North Carolina's 100 counties, including Buncombe (Asheville), New Hanover (Wilmington) and Cumberland (Fayetteville), don't appear in the qualifying dataset because their individual-market benchmark isn't below their small-group benchmark for 2026.
- "Qualifies" isn't a single tier even among the 21 that do. Yadkin County clears the bar at 14.5%; Mecklenburg County clears it at 20.0%. Both "qualify." One is a much stronger case.
- Rates move every plan year. With 2027 small-group filings already up an average of 19.8% against individual filings up 14.9%, next year's spread could widen or narrow from this year's; recheck before every renewal, not just once.
- These are benchmark comparisons, not a guarantee for your specific workforce. A qualifying county means the benchmark math favors ICHRA; model your actual census, ages and plan choices before committing.
- Filed 2027 rates are not approved. North Carolina's Department of Insurance can adjust either figure before finalizing rates.
How these numbers are calculated
Every county figure in this article comes from the same dataset that powers our savings map, not from a survey or a sales estimate. For each of North Carolina's 100 counties, we compare a 2026 individual-market benchmark premium, the second-lowest-cost silver plan available to a representative 50-year-old enrollee, against a small-group benchmark premium built from comparable small-group plan filings for that county's rating area. A county only appears in the dataset at all when its individual-market benchmark runs below its small-group benchmark; 38 of 100 North Carolina counties clear that first bar, covering 6,858,453 residents, and a county "qualifies" for its own page and for the counts in this article's headline when the gap reaches at least $100 a month per employee, 21 counties in North Carolina's case. The separate statewide rate-filing figures in this article come directly from the North Carolina Department of Insurance's own October 29, 2025 announcement, corroborated by ACA Signups' independent compilation of the same NCDOI and SERFF filings; neither is reflected in the county-level qualifying dataset above, which uses the 2026 benchmark comparison described here.
Three limitations are worth stating plainly. First, benchmark premiums are built around a representative enrollee profile, so an unusually young or unusually old workforce will see a different real-world spread than the county figure implies. Second, these are benchmark plans, not every plan on the market; an employee who chooses a richer or leaner plan than the benchmark will see a different premium, though the relative spread tends to hold directionally. Third, rates are filed and refreshed annually, so a county that shows no edge for 2026 is not guaranteed to stay that way for 2027, and a county that qualifies today isn't guaranteed to keep qualifying once next year's filings are approved. We rebuild this dataset each plan year rather than reusing prior-year figures, and we recommend employers do the same before every renewal.
Questions North Carolina employers actually ask
Does ICHRA beat small-group insurance everywhere in North Carolina?
No, and North Carolina is one of the clearer examples of why "does ICHRA work in my state" is the wrong question. An ICHRA estimate clears our $100-a-month-per-employee qualifying bar in an estimated 21 of North Carolina's 100 counties for the 2026 plan year, covering roughly 5,356,994 residents. Another 17 counties show a smaller, positive individual-market discount that doesn't clear the bar, and the remaining 62 counties, including the counties containing Asheville, Wilmington and Fayetteville, show no individual-market price advantage over small group at all in this dataset.
Why don't Asheville, Wilmington and Fayetteville have any ICHRA edge at all?
Buncombe County (Asheville), New Hanover County (Wilmington) and Cumberland County (Fayetteville) don't appear in our qualifying-counties dataset at all for the 2026 plan year, which means their 2026 individual-market benchmark premium isn't lower than their small-group benchmark premium; the math that makes ICHRA a cost play elsewhere simply isn't there in these three counties. That's a statement about relative benchmark pricing in those specific rating areas, not about ICHRA's legality or design; an employer there can still offer one for the flexibility, portability, and no-participation-minimum reasons, just not primarily as a cost-cutting move.
How much can a Mecklenburg County employer expect to save?
Mecklenburg County, home to Charlotte and North Carolina's most populous county, qualifies at an estimated 20.0% for 2026, tied for the widest spread in the state, worth about $2,062 per employee per year using benchmark premiums. That's an estimate built from public rate data, not a quote, and your real number depends on your employees' ages, exact counties, and the plans they choose.
What's happening with North Carolina's 2026 and 2027 health insurance rates?
North Carolina's Department of Insurance approved a final average rate increase of 28.6% for individual ACA marketplace plans for the 2026 plan year (individual carrier increases ranged from 16.88% to 36.4%; small-group increases ranged from 12.66% to 17.5%), announced October 29, 2025. A second, independent compilation by ACA Signups, built from the same NCDOI and SERFF filings, calculated a weighted average of 27.7% for the individual market. Preliminary 2027 filings, per ACA Signups' compilation of NCDOI/SERFF requested rates, run a weighted 14.9% for the individual market and 19.8% for small group. The 2027 figures are requested, not yet approved, rates.
What is the 2026 ICHRA affordability percentage, and why does it matter in North Carolina?
The IRS set the required contribution percentage for plan years beginning in 2026 at 9.96% of household income, under Revenue Procedure 2025-25. It decides whether an employee's ICHRA is considered 'affordable,' which in turn decides whether that employee must waive their ACA premium tax credit to use it. This is a federal number, the same in North Carolina as anywhere else, but the exact dollar contribution needed to clear it still depends on each employee's household income.
Does North Carolina impose any state-specific ICHRA rules?
No. ICHRA is a federal HRA structure created by an IRS, DOL and HHS final rule, and it works the same way in North Carolina as in any other state. North Carolina does not layer additional ICHRA-specific requirements on top of the federal rule, and standard state insurance-producer licensing still applies to anyone advising employees on plan selection. North Carolina uses HealthCare.gov as its marketplace rather than running a state-based exchange.
Is a county that only qualifies at 14.5% still worth pursuing?
Usually, yes, that's a real, meaningful margin, even if it's the thinnest tier that still clears our bar. Yadkin County, one of the counties in that tier, still works out to about $1,438 a year per employee. The more useful question is what happens in the 17 counties below the $100/mo bar, like Surry County at 1.4%, worth only about $141 a year, thin enough to be swallowed by the administrative cost of running an ICHRA correctly for a very small group. If your workforce sits mostly in a county like that, or in one of the 62 counties with no edge at all, the better comparison isn't "ICHRA versus small group," it's "ICHRA versus a taxable stipend versus offering nothing at all."
Where can I check whether my specific North Carolina county qualifies?
Use the savings map to look up any North Carolina county by name. It shows the 2026 individual-market and small-group benchmark premiums side by side, so you can see the estimated spread, or the lack of one, for your workforce's counties before you model a rollout.
Sources
- North Carolina Department of Insurance, "ACA health insurance rates released for 2026 open enrollment" (Oct. 29, 2025; approved 28.6% average individual increase, 12.66% to 17.5% small-group range)
- ACA Signups, "2026 FINAL Gross Rate Changes - North Carolina: +27.7%" (independent compilation of NCDOI/SERFF filings)
- ACA Signups, "2027 Rate Changes - North Carolina" (preliminary, +14.9% individual / +19.8% small group) (compiled from NCDOI/SERFF filings)
- IRS, Revenue Procedure 2025-25 (2026 ACA/ICHRA required contribution percentage, 9.96%)
- Federal Register, "Health Reimbursement Arrangements and Other Account-Based Group Health Plans" (84 Fed. Reg. 28888, June 20, 2019; the ICHRA final rule, including 26 CFR § 1.36B-2(c)(3)(i)(B) premium tax credit interaction)
- 26 CFR § 54.9802-4(c)(6), Individual Coverage HRA notice requirement
- IRS Newsroom, "Health Reimbursement Arrangements (HRAs)"
- KFF, "Marketplace Enrollment Snapshot for Open Enrollment 2026" (North Carolina plan selections, 761,457 vs. 975,110)
- HRA Council, "Strong ICHRA Growth Among Large Employers..." (Growth Trends for ICHRA & QSEHRA, Vol. 5) (Aug. 12, 2026)
- "List of counties in North Carolina" (100 counties)
- ICHRA final rule: Departments of the Treasury/IRS, Labor, and Health and Human Services (2020)