ICHRA in South Dakota 2026: Zero Counties Qualify
South Dakota has zero counties where a 2026 ICHRA estimate beats small group. See why, what 2027 rate filings show, and what to do instead.
The short version
- Zero of South Dakota's 66 counties clear our $100-a-month qualifying bar for the 2026 plan year. This is a rate-spread finding, not a verdict on ICHRA itself.
- South Dakota's individual marketplace runs on three insurers for 2026, and its statewide benchmark silver premium is an estimated $655 a month for a 40-year-old (KFF).
- Three Nebraska Panhandle counties bordering South Dakota's Black Hills region do qualify, at an estimated 16.4%, which shows the gap is regional, not fixed.
- South Dakota's preliminary 2027 filings show small-group rates rising faster than individual rates (about 14.2% versus 10.9%), the direction that would eventually narrow this gap.
- ICHRA still solves problems that have nothing to do with the rate spread: no participation minimum, a fixed budget, and coverage that travels with remote employees.
Does ICHRA beat small group in South Dakota?
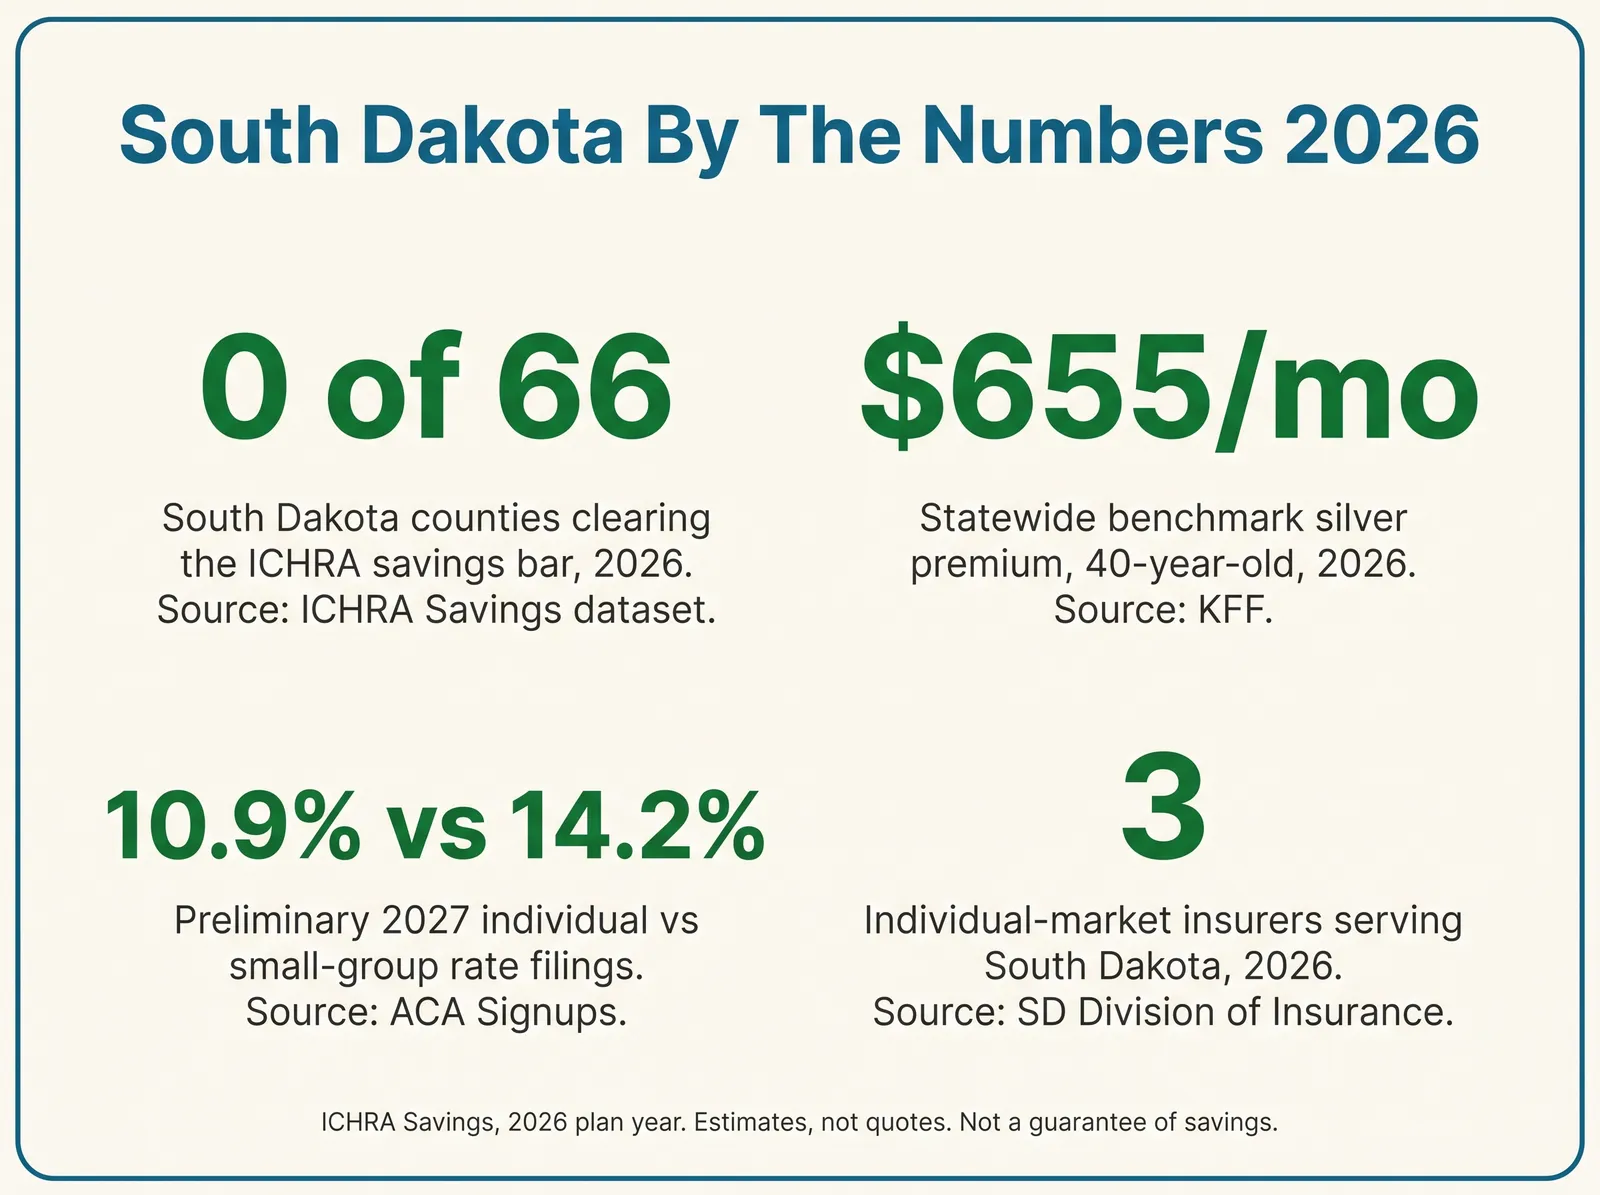
Not yet, and we are going to say that plainly before anything else. An ICHRA (Individual Coverage Health Reimbursement Arrangement) is a way for an employer to give each employee a fixed monthly amount, tax-free, to buy their own individual health plan instead of enrolling everyone in one employer-chosen group plan. Whether that beats a traditional small-group plan on pure cost comes down to a single question: does the individual-market premium in an employee's county run meaningfully below the small-group premium there? For South Dakota, checked county by county against our qualifying bar of at least $100 a month per employee, the answer for the 2026 plan year is zero of the state's 66 counties.
If you found this page because you already know what ICHRA is and want the general decision framework, our ICHRA vs. small group decision guide covers that ground. This article applies it specifically to South Dakota, using the same county-level dataset behind every state page on this site, and it is written from Sioux Falls, where our advisor is based and where this same math applies to his own backyard.
That "zero" is not the whole story, and it is worth saying up front why we are publishing a post about a state where the headline savings case does not currently work. The honest version is more useful than a state-by-state highlight reel: South Dakota employers researching ICHRA deserve to know the real number before they spend time modeling a rollout, and the same county data that says "not here" also says exactly where, just across the state line, it does.
It also matters what "zero counties" does and does not mean. It does not mean South Dakota employees pay unusually high premiums, or that individual coverage here is a bad deal on its own terms. It means that, specifically compared against this state's small-group benchmark premiums, the individual side does not currently come in far enough below to clear the threshold this site uses to call a county a genuine cost-arbitrage opportunity. A county can miss that bar by a wide margin or a narrow one, and South Dakota's counties, as the next sections show, tend to sit closer to par than counties elsewhere with a wide, double-digit spread. That distinction is worth carrying through the rest of this article: "doesn't qualify" is a specific, narrow finding, not a verdict that ICHRA has nothing to offer a South Dakota employer.
0 of 66
South Dakota counties clearing the qualifying bar for 2026
3
Individual-market insurers serving South Dakota for 2026
$655
Statewide benchmark silver premium, 40-year-old, 2026
16.4%
Nearest qualifying counties, just across the Nebraska line
What an ICHRA actually is
An ICHRA lets an employer of any size set a monthly reimbursement budget, and each employee uses it to buy their own plan on the individual market (a HealthCare.gov Marketplace plan or an off-exchange plan) and gets reimbursed tax-free for the premium and, if the employer allows it, other qualified medical expenses. It is a self-insured group health plan under IRS rules, created by a 2019 final rule from the Treasury/IRS, Department of Labor, and HHS, and it has no employer-size minimum: a five-person shop can offer one on the same legal terms as a five-hundred-person company. It is distinct from a QSEHRA (Qualified Small Employer HRA), a smaller HRA structure capped at a federal dollar limit that only employers with fewer than 50 employees and no group plan can use; ICHRA has no federal reimbursement cap and no employer-size ceiling. An employer cannot offer the same class of employees a choice between traditional group coverage and an ICHRA, though it can offer group coverage to one class (say, full-time staff) and an ICHRA to a different class (say, part-time or remote staff). ICHRA eligibility itself does not depend on whether a company is an ALE (Applicable Large Employer, generally an employer averaging 50 or more full-time-equivalent employees in the prior year, per IRS rules) or not; that status matters separately, because it decides whether the ACA's employer mandate, the requirement to offer affordable coverage or face a potential penalty, applies to a company at all. An ICHRA that clears the affordability test satisfies that mandate the same way traditional group coverage would.
Two more terms matter before the numbers do. An employee class is a group defined by an IRS-permitted factor, such as full-time versus part-time status, salaried versus hourly work, or geographic location, each of which can get its own ICHRA design and budget, subject to minimum-size rules. And substantiation is the paperwork side: before the first reimbursement and again with every claim, an employee has to show proof of individual coverage, either a document from the insurer or exchange or a signed attestation, which is what keeps the arrangement compliant as a tax-free benefit rather than taxable income.
A few more terms, briefly
A metal level (bronze, silver, gold, platinum) sets how a plan splits costs between premium and out-of-pocket spending; this article uses the silver benchmark, the standard ACA reference point. A rate area is a geographic pricing zone insurers use to set premiums, which is why neighboring counties sometimes price identically. The FPL (Federal Poverty Level) is an income threshold HHS publishes each year, used in one accepted method for testing ICHRA affordability. And MOOP (maximum out-of-pocket) is the ACA-mandated annual cap on what an enrollee pays in cost-sharing before their plan covers 100% of covered costs.
Why South Dakota's math doesn't clear the bar
South Dakota's individual marketplace is thinner, in carrier terms, than many states where this site's math works well. For the 2026 plan year, exactly three insurers write ACA-compliant individual plans in the state: Avera Health Plans and Sanford Health Plan, both statewide, and Wellmark Blue Cross Blue Shield of South Dakota, which the South Dakota Division of Insurance lists as active in 39 of the state's 66 counties. Both Avera and Sanford are the insurance arms of South Dakota's two dominant integrated health systems, which also run the hospitals and clinic networks much of the state uses. Three insurers is not unusually low by national standards, but it is fewer choices than drive some of the widest ICHRA-favoring spreads on this site, and less competition on the individual side tends to keep individual premiums from falling as far below group premiums as they do in more competitive markets.
The 2026 marketplace open enrollment period for South Dakota, like every state using HealthCare.gov, ran from November 1, 2025 through January 15, 2026, per the South Dakota Division of Insurance. That timing does not change the rate math, but it does set the calendar an employer needs to work around if the plan is to enroll employees who want to shop the individual market for the first time.
None of this means South Dakota's individual market is expensive in absolute terms, or that the state's small-group plans are unusually cheap. It means that, for the 2026 plan year, the gap this site's method looks for, individual-market benchmark pricing running meaningfully below small-group benchmark pricing, has not opened up here the way it has in a majority of U.S. counties nationally, where 1309 counties currently qualify.
There is also a structural wrinkle specific to South Dakota worth naming: Avera and Sanford are not just the two largest individual-market insurers, they are vertically integrated with the two health systems that operate most of the state's hospitals and clinics. That arrangement is common in rural, low-density states, where a small population spread across a large geography makes it hard to sustain more than a couple of competing full-service systems. It is not, by itself, evidence of anything improper; it simply means the price competition this site's method depends on, several insurers bidding against each other for the same individual-market enrollees, has fewer independent players pushing on it here than in a state with a dozen ACA carriers. Rate area pricing compounds that: South Dakota's individual-market premiums are set by geographic pricing zone rather than by county alone, so a wide swath of counties inside the same rate area can price identically, the same mechanism our sister article on how rating areas create identical premiums across different counties covers in Ohio.
What coverage actually costs today
A useful number to anchor the rest of this article: South Dakota's statewide benchmark silver premium, the second-lowest-cost silver plan for a 40-year-old, runs an estimated $655 a month for the 2026 plan year, according to KFF's Marketplace Average Benchmark Premiums tracker. That is the individual side of the comparison. The site's own dataset builds the small-group side from comparable small-group plan filings by rating area, and for every one of South Dakota's 66 counties, that small-group benchmark comes in at or below the individual benchmark, which is the literal definition of "zero qualifying counties" here. We are not publishing a South Dakota-specific small-group dollar figure in this article, because no public filing source breaks it out the way individual-market rate filings are broken out; the qualifying calculation itself, built from the same Ideon and CMS-cross-verified data behind every other state on this site, is what backs the zero.
A $655 average is not your employee's price
Benchmark premiums are built around a representative 40-year-old enrollee. A younger workforce will generally see lower individual-market premiums than $655; an older one will see higher. The relative comparison to small-group pricing is what decides whether ICHRA wins, not the raw dollar figure, which is exactly why this dataset compares the two side by side rather than quoting one number in isolation.
What next door looks like
Here is the part a flat "South Dakota doesn't work" headline would hide: drive two hours southwest from the Black Hills and the answer flips. Three Nebraska Panhandle counties that share a border with South Dakota, Dawes, Sheridan, and Sioux Counties, all clear our qualifying bar at an identical 16.4% estimated savings for 2026, worth about $2,115 a year per employee. Nebraska's Cherry County, also on the border, clears at a thinner 5.0%, about $569 a year. All four counties share the same individual-market benchmark premium ($896 a month), which points to a shared rate area; what changes county to county is the small-group side of the comparison.
| County (Nebraska) | Individual benchmark | Small-group benchmark | Est. savings | Est. annual savings / employee |
|---|---|---|---|---|
| Dawes County | $896 | $1,072 | 16.4% | $2,115 |
| Sheridan County | $896 | $1,072 | 16.4% | $2,115 |
| Sioux County | $896 | $1,072 | 16.4% | $2,115 |
| Cherry County | $896 | $943 | 5.0% | $569 |
This matters beyond curiosity. A South Dakota company headquartered in Rapid City (Pennington County) that employs even one remote worker living across the line in Dawes, Sheridan, or Sioux County, Nebraska, has a real, dataset-backed ICHRA case for that person, even though the company's own home county shows nothing. Our guide to ICHRA for remote teams across multiple states walks through exactly this kind of split workforce in more detail.
It is also a useful reminder for how HR and finance teams should actually run this check. It is tempting to look up a single state and treat the answer as final, the way a news headline might. The underlying dataset does not work that way; it is built county by county, and a state line is a political boundary, not an economic one. Rate areas, hospital networks, and insurer service territories routinely cross state lines without lining up with them, which is exactly why South Dakota and its nearest Nebraska neighbors can price so differently while sitting a short drive apart.
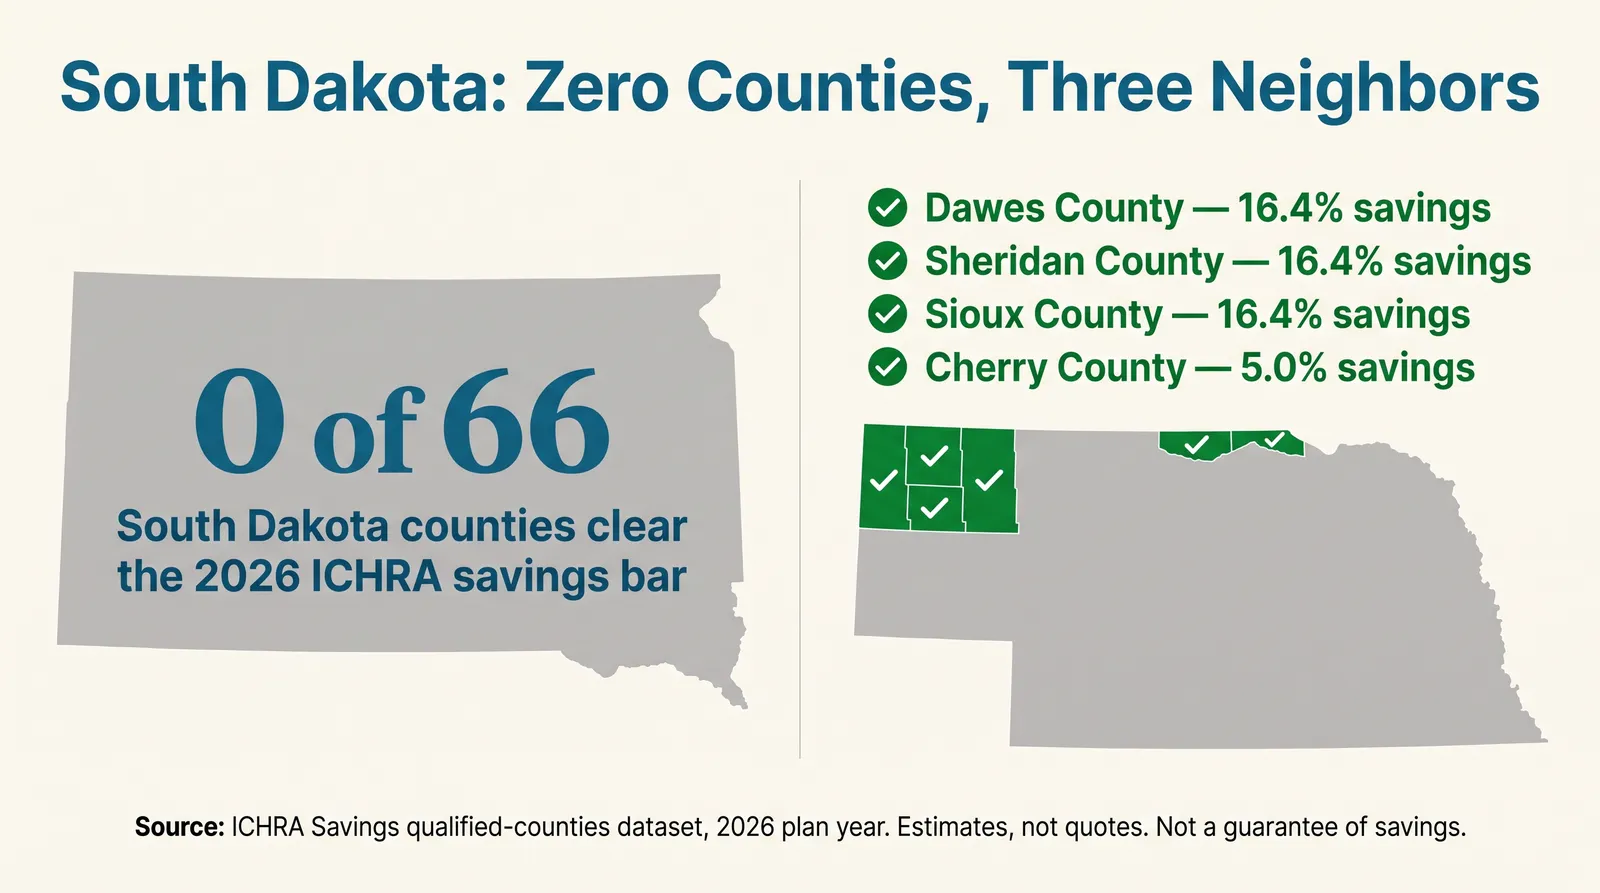
South Dakota isn't a state where ICHRA loses. It's a state where the line runs right along the Nebraska border, and knowing which side your employee lives on is the entire question.
Mike MooreHere is what that looks like arithmetically for a real company. Say a 12-employee South Dakota business is headquartered in Rapid City (Pennington County), with 10 employees living locally and 2 working remotely from Sheridan County, Nebraska, just across the state line.
Here's the math
For the 10 Pennington County employees, Pennington County is not in the qualifying dataset at all for 2026, so the rate-spread case for them is currently nothing, though they still gain the budget-certainty and no-participation-minimum benefits of an ICHRA if the employer chooses to offer one. For the 2 Sheridan County employees, the 2026 individual benchmark runs $896 a month against a small-group benchmark of $1,072, an estimated savings of $176 a month, or $2,115 a year each. That's $4,229 a year in aggregate estimated savings from a workforce where 10 of 12 people show no rate-spread case whatsoever. Small, real, and entirely dependent on where those two people happen to live, not on anything about the company itself.
Widen that same company by one more remote hire in Dawes or Sioux County and the number moves again, in either direction, depending on where that person lives. That's the entire point of checking every county individually instead of asking "does ICHRA work in South Dakota" as if it had one answer.
What the 2027 filings show
Rates are refreshed every plan year, and South Dakota's next cycle is already partway filed. Insurers have submitted preliminary 2027 rate requests showing a weighted individual-market average increase of about 10.9% against an unweighted small-group average increase of about 14.2%, according to ACA Signups' compilation of the federal Rate Review database. By carrier: Avera Health Plans requested an average 11.7% individual increase, covering roughly 21,516 members, effective January 1, 2027. Sanford Health Plan requested 11.76% for its TRUE product and 11.45% for its Simplicity product, covering roughly 17,910 members as of March 2026, also effective January 1, 2027. Wellmark's specific requested rate was not disclosed in the public filing summary; its South Dakota individual book covers roughly 8,000 members.
Filed is not final, and the direction is the story
These are requested rates, subject to South Dakota Division of Insurance and CMS review, and they can move before final approval, the same way Kansas's 2026 individual-market filing came down from a preliminary 30.5% to a final 26.6% once approved rates replaced requested ones. What is worth watching in South Dakota specifically is the direction: small-group rates are currently filed to rise faster than individual rates. If that holds through final approval, it is the exact mechanism that would eventually narrow, and possibly close, the gap that currently keeps every South Dakota county out of the qualifying dataset.
If your county isn't there
The fix is not a trick, and we are not going to pretend the rate-spread math says something it doesn't. Here is the real method, in order.
- Check every employee's actual county, not your office address. A South Dakota employer with even one remote hire, contractor-turned-employee, or field worker living outside the state can have a genuinely different answer for that person, as the Nebraska Panhandle counties above show.
- Separate the cost-arbitrage question from the other four reasons employers choose ICHRA. A fixed, employer-chosen monthly budget instead of a carrier-set annual renewal; no carrier participation minimum, which matters for a small South Dakota team where a few employees are on a spouse's plan; coverage that travels with anyone who works remotely or moves; and, for a company offering no benefit today, a real benefit at any size, starting at one employee. None of those depend on the individual market being cheaper than group.
- If you're a company under 50 employees with no group plan today, look at QSEHRA too. Its federal reimbursement caps are lower than an uncapped ICHRA, but it is simpler to administer for a very small team weighing "something" against "nothing."
- Recheck after 2027 rates are approved, not just once. With small-group filings currently running ahead of individual-market filings, the gap could move before your next renewal. We rebuild the underlying dataset every plan year specifically so this check stays current.
- If you still want to run the ICHRA math yourself, model your real census. County benchmarks describe the market; your workforce's actual ages, family sizes, and plan choices decide your real number.
The arithmetic above is generic
Your county, and each of your employees' counties, has its own answer, and you can look it up in about ten seconds: https://ichrasavings.com/ichra-savings-map/.
How ICHRA Savings helps
None of the county math above requires talking to anyone. The savings map lets you look up South Dakota, Nebraska, or any other U.S. county by name and see the same individual-market and small-group benchmark premiums used in this article, so you can check every county where you actually have an employee before spending time on anything else. Where we help past that: designing employee classes that hold up (geography-based classes are the relevant tool for a South Dakota employer with even one out-of-state remote hire), modeling affordability against a real census rather than a rule of thumb, and getting the required employee notice right and on time if the math and the workforce shape make ICHRA a fit. We don't pick anyone's individual plan for them; that choice, and the choice of network, stays with each employee. For a South Dakota employer specifically, the most common shape we see is a company weighing "offer something for the first time" rather than "replace an existing group plan," since a South Dakota business under 50 employees is under no legal obligation to offer coverage at all; an ICHRA at any budget size is still a real, tax-advantaged benefit in that comparison, independent of whether the rate-spread math favors it. If your renewal is already in hand and you have a deadline, it is worth a conversation: https://ichrasavings.com/book.
Setting one up anyway, if it fits
South Dakota does not add state-specific ICHRA rules on top of the federal framework; the same 2019 Treasury/IRS, Department of Labor, and HHS final rule governs it here as everywhere else, and the setup sequence is the same one we walk employers through in any state where the case is real, whether that's cost arbitrage, participation flexibility, or a remote workforce:
- Pull your census by county, not by office address. Include every remote hire, even one living out of state.
- Check each employee's county on the savings map. A South Dakota headquarters and a Nebraska Panhandle remote hire are two different stories under the same roof.
- Model affordability against real household incomes. The IRS's annual required contribution percentage decides whether a given employee's offer counts as affordable, which decides their premium tax credit (PTC, the ACA subsidy that lowers a Marketplace enrollee's monthly premium) eligibility. There are two accepted ways to run this test: measuring against the employee's actual household income, or using an affordability safe harbor, a simpler, IRS-approved substitute measure (an employee's Form W-2 wages, their rate of pay, or the FPL published annually by HHS) an employer can use instead of asking for real household income. Our affordability percentage guide covers the current federal threshold and each safe harbor in depth.
- Define employee classes carefully, if you use them. Class rules carry minimum-size requirements and cannot offer the same class a choice between ICHRA and group coverage.
- Send the required notice on time. Eligible employees generally need written notice at least 90 calendar days before the plan year begins, with specific required content about the offer and its effect on subsidy eligibility.
- Budget for onboarding support. Employees who have never shopped South Dakota's individual marketplace on their own need guidance, once, at enrollment.
See our full ICHRA setup timeline for the detailed rollout plan, and our guide to ICHRA employee classes if your South Dakota workforce spans more than one state.
Read this before you commit
The honest limits of this data
- Zero of South Dakota's 66 counties clear our qualifying bar for 2026. That is the finding of this specific method (a $100-a-month-per-employee individual-versus-small-group gap), not a statement that ICHRA cannot work here for other reasons.
- The nearest qualifying counties are in Nebraska, not South Dakota. Dawes, Sheridan, and Sioux Counties clear the bar; they only help a South Dakota employer if an actual employee lives there.
- These are benchmark comparisons, not a guarantee for your specific workforce. A non-qualifying state does not mean every individual plan costs more than every group plan for every person; model your real census before ruling anything out.
- Rates move every plan year. With 2027 small-group filings already running ahead of individual-market filings (14.2% versus 10.9%), next year's spread could narrow from this year's; recheck before every renewal, not just once.
- Filed 2027 rates are not approved. South Dakota's insurance regulators and CMS can adjust either figure before finalizing rates.
- Taking an ICHRA generally means waiving the premium tax credit for that month if the offer is considered affordable under the IRS test. This is not free money layered on top of a marketplace subsidy; it is a trade, and it should be explained to employees plainly.
How these numbers are calculated
Every county figure in this article comes from the same dataset that powers our savings map, not from a survey or a sales estimate. For each U.S. county, we compare a 2026 individual-market benchmark premium (the second-lowest-cost silver plan available to a representative enrollee) against a small-group benchmark premium built from comparable small-group plan filings for that county's rate area, using Ideon data cross-verified against CMS public-use marketplace files. A county enters the qualifying dataset when the gap between those two benchmarks reaches at least $100 a month per employee. None of South Dakota's 66 counties clear that bar for 2026; the three Nebraska Panhandle counties cited above do, using the identical method. South Dakota's total county count comes from the U.S. Census Bureau's 2020 county reference file. The statewide $655 benchmark-silver figure comes from KFF's Marketplace Average Benchmark Premiums tracker, a second-lowest-cost-silver, 40-year-old measure, separate from and not part of the qualifying-county calculation itself. The 2027 rate-filing figures come from the federal Rate Review database as compiled by ACA Signups, and are requested rates, not approved ones.
Two limitations are worth stating plainly. First, benchmark premiums are built around a representative enrollee profile, so an unusually young or unusually old South Dakota workforce will see a different real-world spread than a statewide average implies. Second, rates are filed and refreshed annually, so a state that does not qualify for 2026 is not permanently excluded; we rebuild this dataset every plan year rather than reusing prior numbers, and we recommend employers do the same before every renewal.
Questions South Dakota employers actually ask
Does ICHRA save South Dakota employers money compared to small-group insurance?
Not on the rate-spread math, as of the 2026 plan year. Our county dataset compares individual-market benchmark premiums against small-group benchmark premiums in every U.S. county, and zero of South Dakota's 66 counties currently show individual pricing at least $100 a month below small group. That is a statement about today's rate filings, not a permanent verdict, and it is an estimate from public and industry data, not a quote.
Why doesn't South Dakota have any qualifying counties when neighboring states do?
South Dakota's individual marketplace is served by three insurers for 2026 (Avera Health Plans, Sanford Health Plan, and Wellmark Blue Cross Blue Shield of South Dakota, the last active in 39 of the state's 66 counties), and its statewide benchmark silver premium runs an estimated $655 a month for a 40-year-old, per KFF's 2026 tracker. Just across the line, three Nebraska Panhandle counties bordering South Dakota's Black Hills region (Dawes, Sheridan, and Sioux Counties) do clear our qualifying bar, at an estimated 16.4% and about $2,115 a year per employee. That tells you the underlying spread is a regional pricing question, not a South Dakota-specific ceiling, and it can move with the next rate cycle.
What's happening with South Dakota's 2027 health insurance rates?
South Dakota insurers have filed preliminary 2027 rate requests showing a weighted individual-market average increase of about 10.9% against an unweighted small-group average increase of about 14.2%, according to ACA Signups' compilation of the federal Rate Review database. Avera Health Plans requested an average 11.7% individual increase (roughly 21,516 members) and Sanford Health Plan requested 11.76% for its TRUE product and 11.45% for Simplicity (roughly 17,910 members, as of March 2026), both effective January 1, 2027. These are preliminary, requested figures, not approved rates.
Is ICHRA still worth considering for a South Dakota employer if it does not save money on the rate spread?
It can be, for reasons that have nothing to do with the individual-versus-group rate spread. An ICHRA has no carrier participation minimum, so it does not collapse when part of a team is on a spouse's plan. It travels with employees who live in a different county or state than the company's office, which matters directly here: an employee living in one of the Nebraska Panhandle counties above would see real ICHRA savings even if the employer is headquartered in South Dakota. And it converts an unpredictable annual renewal into a fixed number the employer chooses.
What if my South Dakota company has remote employees living in another state?
Check each employee's actual county, not your office address. ICHRA reimbursements are driven by where an employee buys their individual-market plan, which is where they live, so a South Dakota employer with staff in a qualifying county elsewhere (or vice versa) gets a different answer for each person. This is exactly the situation our guide to ICHRA for remote and multi-state teams walks through in more depth.
Will South Dakota ever have a qualifying county?
Possibly. Rates are filed and refreshed every plan year, and South Dakota's own preliminary 2027 filings already show small-group rates rising faster than individual-market rates (an estimated 14.2% versus 10.9%), which is the direction that would eventually narrow or close this gap if the trend holds through final approval. We rebuild this dataset every plan year rather than reusing prior numbers, and we'd recommend any South Dakota employer do the same before ruling ICHRA out for good.
Does South Dakota add any state-specific ICHRA rules on top of the federal framework?
No. ICHRA is a federal HRA structure created by a 2019 Treasury/IRS, Department of Labor, and HHS final rule, and it works the same way in South Dakota as in any other state. South Dakota does not layer additional ICHRA-specific requirements on top of the federal rule, though standard state insurance-producer licensing still applies to anyone advising employees on plan selection.
Where can I check my own county, or my employees' counties?
Use the savings map to look up any U.S. county by name. It shows the same 2026 individual-market and small-group benchmark premiums used in this article, so you can check every county where you have an employee, not just your headquarters, before you spend time modeling a rollout.
Sources
- ICHRA Savings qualified-counties dataset (
src/data/qualified_counties.json), built from Ideon rate data cross-verified against CMS public-use marketplace files, 2026 plan year - South Dakota Division of Insurance, "Individual Exchange 2026" (3 insurers; Wellmark's 39-of-66-county coverage; Nov. 1, 2025 – Jan. 15, 2026 open enrollment)
- KFF, "Marketplace Average Benchmark Premiums" (South Dakota, 2026, $655/month, 40-year-old second-lowest-cost silver)
- ACA Signups, "2027 Rate Changes – South Dakota" (preliminary, compiled from the federal Rate Review database; individual +10.9%, small group +14.2%; Avera and Sanford filing detail)
- U.S. Census Bureau, 2020 county reference file for South Dakota (66 counties)
- HealthCare.gov, "Individual coverage HRA" (definition, employer-size rule, premium tax credit interaction)
- IRS, "Employer Shared Responsibility Provisions" (Applicable Large Employer / employer mandate, 50 full-time-equivalent threshold)
- ICHRA final rule: Departments of the Treasury/IRS, Labor, and Health and Human Services (2019)