ICHRA in Springfield, Ohio 2026: Clark County 58.3%
Clark County, Ohio employers can estimate 58.3% savings vs. small group with ICHRA in 2026: Springfield rate data, worked math, and local context.
The short version
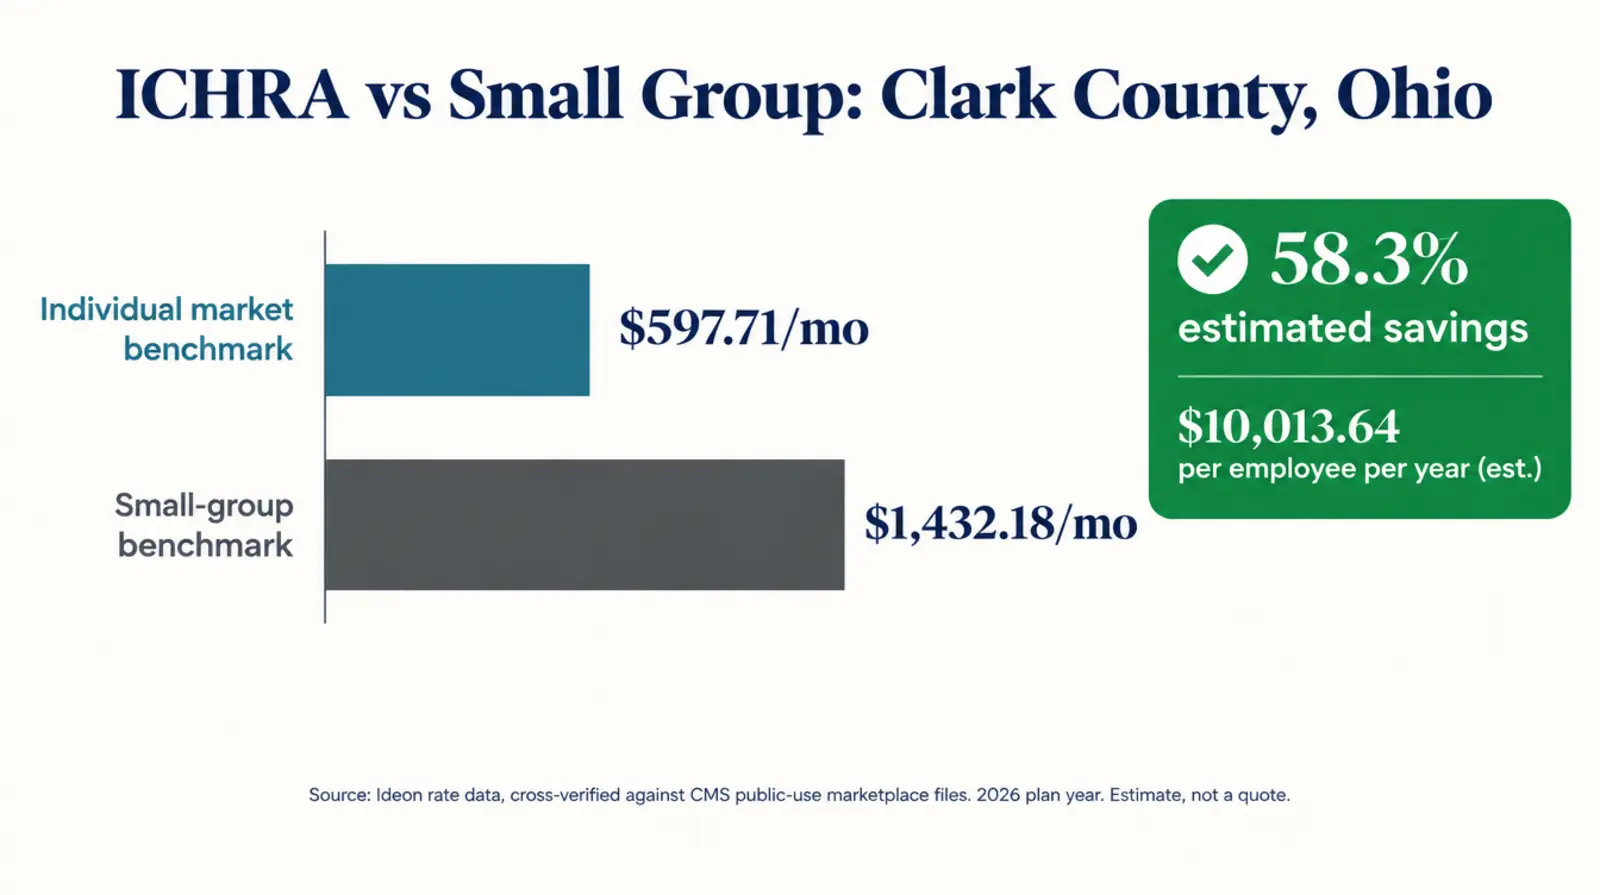
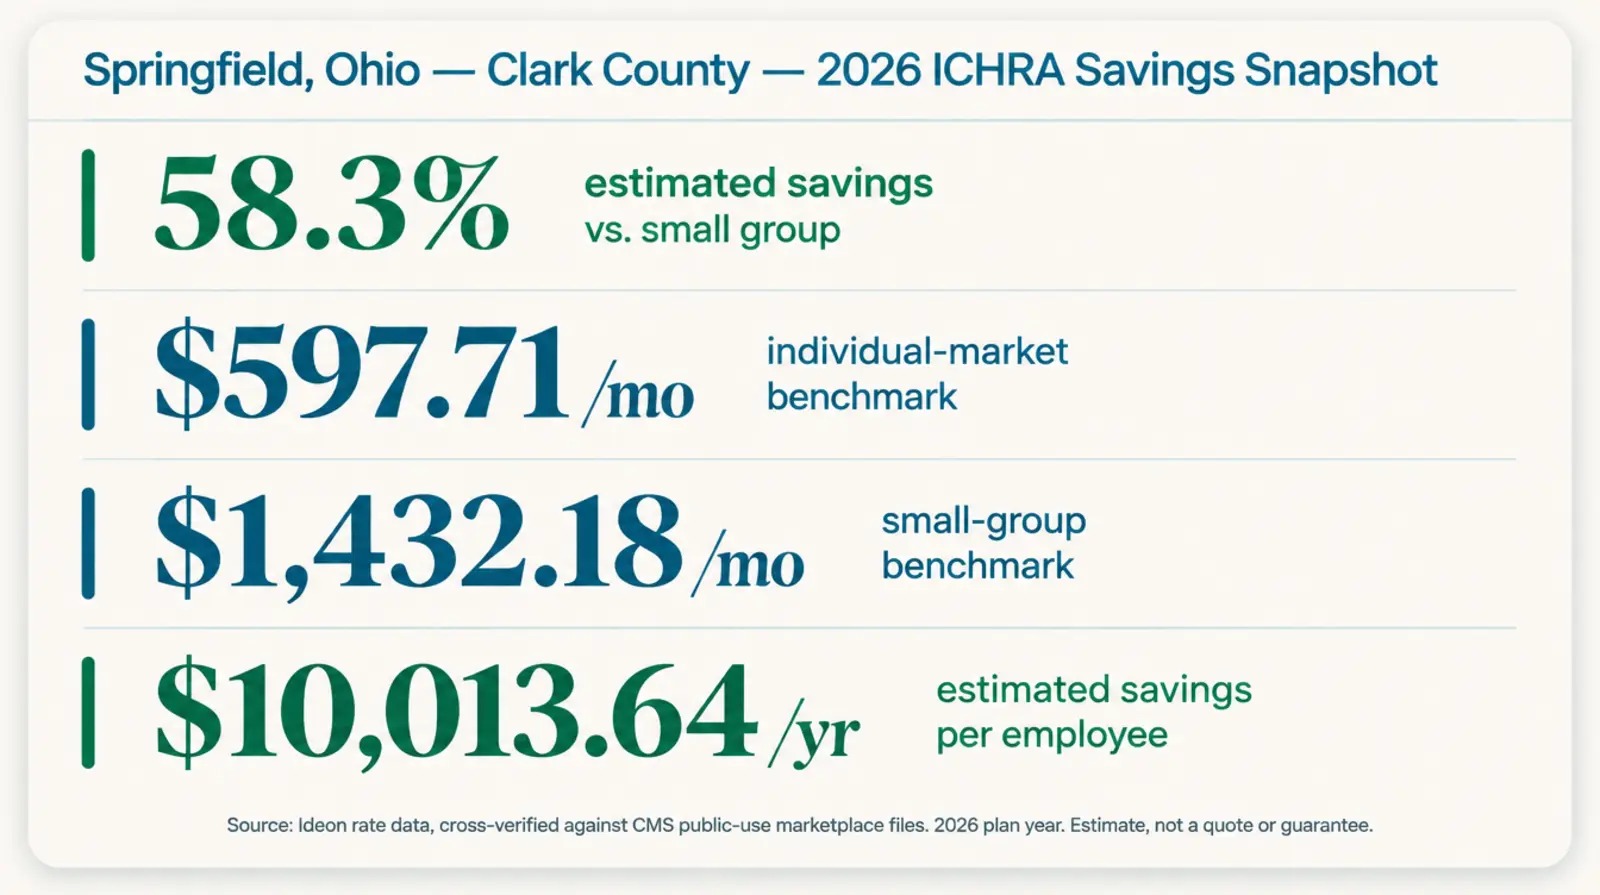
- Clark County's 2026 individual-market benchmark runs an estimated 58.3% below the small-group benchmark, about $10,014 per employee per year.
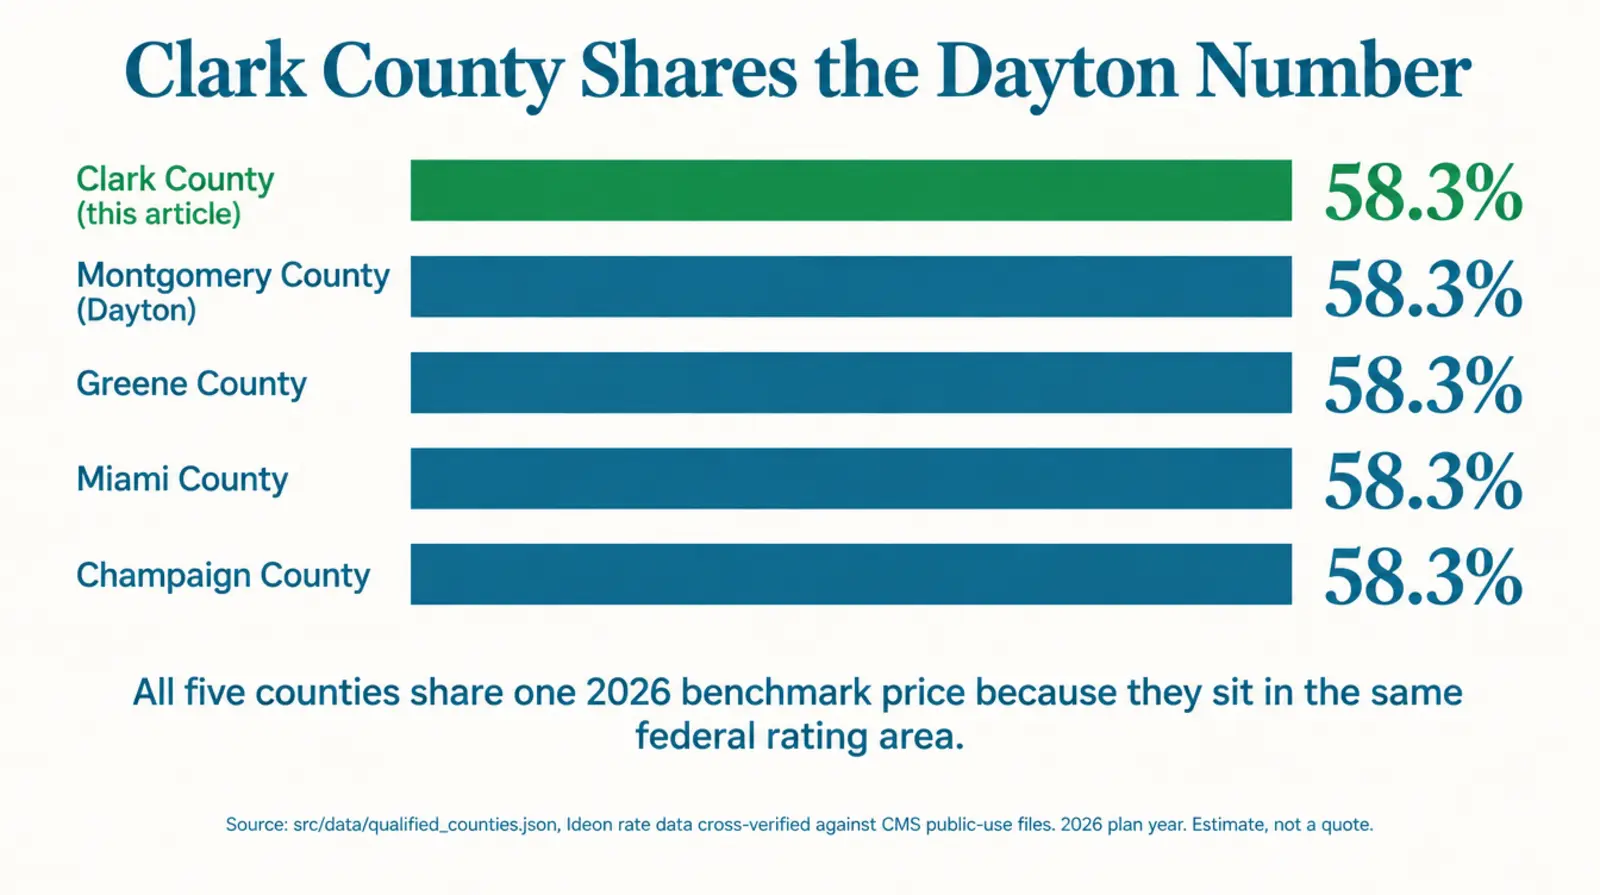
- Springfield, Clark County's seat, shares its exact benchmark numbers with Montgomery County (Dayton), Greene, Miami and Champaign counties — all five sit in the same federal rate area, so the identical price is not a coincidence.
- Electra, a hybrid-electric aircraft maker, is building an $850 million, 1,975-job production facility at AirPark Ohio next to Springfield-Beckley Municipal Airport, per a JobsOhio and Ohio Governor's office announcement on July 21, 2026 — a scale of single-employer hiring that smaller Clark County businesses now have to compete against for workers.
- Per the U.S. Bureau of Labor Statistics' Quarterly Census of Employment and Wages for Clark County (area code 39023), 2025 annual averages, the county's 2,418 private establishments employ 38,739 people; manufacturing alone employs 6,345 at an average annual wage of $66,572, well above the county's $52,484 all-private average.
- Ohio does not cap small-group carrier participation requirements by statute; Ohio Revised Code § 3924.03(E)(1) defines the "group participation rule" mechanic but leaves the specific enrollment bar to each carrier, which varies plan to plan.
- Qualifying is not the same as guaranteed savings for your business. The honest limits are covered later, including where this comparison breaks down for a specific workforce.
Does ICHRA beat small group in Springfield, Ohio?
Yes. An ICHRA (Individual Coverage Health Reimbursement Arrangement) is an IRS-defined arrangement that lets an employer set a fixed monthly reimbursement amount and let each employee buy their own individual-market plan with it, tax-free. In Clark County, the county whose seat is Springfield, Ohio, the 2026 individual-market benchmark premium runs an estimated 58.3% below the small-group benchmark premium, according to a county-by-county comparison built from Ideon rate data and cross-verified against CMS public-use marketplace files.
That 58.3% sits above the statewide average of 54.9%, ranking 36 out of Ohio's 88 counties by percentage. The dollar figure that matters most to a Clark County employer's budget is $10,014 per employee per year, ranking 35 of Ohio's 88 counties by that measure. Of the 1,309 counties nationwide in our dataset, 88 are in Ohio, and all 88 of them clear the $100-a-month gap we use as the floor for calling a county "qualifying" at all — Ohio is one of a small number of states where every county clears that bar, a point our statewide Ohio guide covers in more depth.
58.3%
Estimated Clark County savings vs. small group
$10,014
Estimated savings per employee per year
136K
Clark County residents
36/88
Clark's rank by percentage among Ohio counties
Why Clark County's number matches five of its neighbors exactly
Our earlier guide to Ohio's rating areas explains a pattern that holds across much of the state: carriers file one benchmark price for a whole cluster of counties at once, a federally defined geography called a rating area, so several counties end up showing the identical number to the cent. Clark County is a clean example of that pattern in action. Checked against every other Ohio county in our dataset, Clark's individual benchmark ($597.71) and small-group benchmark ($1432.18) match 7 other counties exactly, including Montgomery County, which contains Dayton, plus Greene, Miami, Champaign and Darke counties.
That's a useful, practical fact for a Springfield employer with staff who live in Dayton, Xenia, Troy, or Urbana: the county-level benchmark math doesn't change at the Clark County line. A business with a mixed Clark-Montgomery-Greene workforce can use one comparison for the whole team rather than pulling a different number for each employee's home address. That's not true everywhere in Ohio — our Morrow County guide covers a county whose number matches none of its neighbors — so it's worth confirming for your specific counties rather than assuming it, which this article does for Clark and four others.
| County | Population | Individual benchmark | Small-group benchmark | Savings vs. small group |
|---|---|---|---|---|
| Montgomery County | 536K | $597.71 | $1432.18 | 58.3% |
| Greene County | 168K | $597.71 | $1432.18 | 58.3% |
| Clark County (this article) | 136K | $597.71 | $1432.18 | 58.3% |
| Miami County | 109K | $597.71 | $1432.18 | 58.3% |
| Champaign County | 39K | $597.71 | $1432.18 | 58.3% |
Source: src/data/qualified_counties.json, 2026 plan year (Ideon rate data,
cross-verified against CMS public-use marketplace files). Estimates, not quotes.
Columbus is a different rate area entirely
Franklin County (Columbus), covered in our statewide "All 88 Counties Qualify" guide, shows an estimated 59.6%, a real and sourced figure, but a different rate area and a different number from Clark's 58.3%. Springfield sits roughly halfway between Dayton and Columbus on I-70, so don't assume a Columbus-area number applies to a Clark County workforce; check the county directly, which is what this article and the savings map are both built to let you do.
How Ohio's 88 counties break down by savings tier
Number of counties in each savings band, 2026 plan year. Source: Ideon rate data, cross-verified against CMS public-use files.
Clark sits in the upper-middle tier, above the statewide average. Illustrative and rounded; not an offer of insurance or a guarantee of savings.
Springfield's manufacturing comeback, in the numbers
Springfield spent decades known for the farm-equipment and machine-tool manufacturing that built the city, then watched a long stretch of plant closures hollow out that base. The most significant recent counterweight: on July 21, 2026, at the Farnborough International Airshow, Ohio Governor Mike DeWine, JobsOhio President and CEO J.P. Nauseef, and Electra CEO Marc Allen announced that Electra, a hybrid-electric aircraft maker, had selected a 96-acre site at AirPark Ohio, adjacent to Springfield-Beckley Municipal Airport, for its first production facility for the EL9 Ultra Short, a nine-passenger aircraft designed to take off and land in as little as 150 feet. Per JobsOhio's own announcement, the project represents an $850 million investment and is expected to create 1,975 jobs, with initial capacity for up to 400 aircraft a year, scaling to 800 in a later phase.
That single project will eventually out-employ most of the county's existing manufacturers combined, which changes the competitive picture for everyone else hiring locally. Clark County still has a working base of smaller manufacturers today: per the Greater Springfield Chamber of Commerce's own reporting, employers in the county include branches of multinational corporations like Konecranes, alongside homegrown manufacturers such as Fire Manufacturing Innovations LLC, a Clark County fire-equipment maker founded in 2007 that has said its goal is to "double our capacity in Clark County within the next five years." Those are the employers who have to compete for machinists, welders and technicians against a benefits package set by an $850 million aerospace employer that hasn't even opened yet.
Per the U.S. Bureau of Labor Statistics' Quarterly Census of Employment and Wages (QCEW) for Clark County (area code 39023), 2025 annual averages, the county's 2,418 private-sector establishments employed 38,739 people at an average annual pay of $52,484. Manufacturing, 148 establishments strong, employed 6,345 people at an average annual pay of $66,572 — well above the countywide private average. Health care and social assistance employed 6,724 people across 318 establishments at $58,687 average pay, the county's largest single private sector by headcount. Retail trade employed 4,653 people across 356 firms at $34,537 average pay, while accommodation and food services employed 4,743 people across 255 firms at $21,067 average pay, the lowest-paid major sector tracked. Local government employed 6,221 people across 119 establishments at $55,631 average pay.
| Sector | Establishments | Employment | Avg. annual pay |
|---|---|---|---|
| All private industry | 2,418 | 38,739 | $52,484 |
| Manufacturing (NAICS 31-33) | 148 | 6,345 | $66,572 |
| Health care and social assistance (NAICS 62) | 318 | 6,724 | $58,687 |
| Retail trade (NAICS 44-45) | 356 | 4,653 | $34,537 |
| Accommodation and food services (NAICS 72) | 255 | 4,743 | $21,067 |
| Local government | 119 | 6,221 | $55,631 |
Source: U.S. Bureau of Labor Statistics, Quarterly Census of Employment and Wages, Clark County, Ohio (area code 39023), 2025 annual averages.
A workforce larger than the private-sector total alone
Across all ownership types, BLS counts 45,578 total covered jobs across 2,566 establishments in Clark County against a dataset population of 136K. Once Electra's facility is operational, that total is set to grow by nearly 2,000 jobs at a single site, which is a meaningful share of the county's current private-sector base — and a reason smaller local employers are watching their own benefits budget more closely than they were a year ago.
Why a Clark County employer feels group-insurance pricing the hardest
A 14-person machine shop off U.S. 40, a specialty fabricator near the AirPark Ohio site, or a family-run HVAC or electrical contractor serving the Springfield-Beckley corridor all share a version of the same problem. None of them is large enough to negotiate group-insurance pricing the way a major employer can, and none has the kind of stable, uniformly full-time payroll that small-group underwriting assumes. A fabrication shop might run lean on office staff while carrying a skilled-trades crew that's exactly the kind of higher-wage, harder-to-replace worker an owner most wants to compete for with a real benefit, especially with Clark County's manufacturing wage average sitting at $66,572 — a number that is about to face new competition from an aerospace employer with an $850 million facility to staff.
Group health insurance is priced and underwritten around a knowable, largely stable enrolled population. A carrier protects that pricing with a minimum enrollment share among eligible employees before it will issue a policy, and the exact bar is set by the carrier, not capped by Ohio statute (more on that below). For a small Clark County employer with a mix of full-time shop staff, part-time administrative help, and employees already covered through a spouse's plan, clearing whatever bar a given carrier happens to set is a real obstacle — one that has nothing to do with whether the employer wants to offer a benefit and everything to do with a workforce shape group underwriting wasn't built for.
This is the pain point this guide is written for: an owner who priced group coverage, ran into either the participation math or a renewal number that jumped without warning, and assumed there was nothing realistic to offer, when in fact Clark County's individual market is priced low enough, relative to small group, that a modest fixed monthly contribution goes further here than in most other Ohio counties.
See the full Ohio savings breakdown for every qualifying county, the national savings map to look up a specific county by name, or the Ohio vs. Georgia comparison for how Clark's number fits into the bigger multi-state picture.
Springfield's next big employer story is an $850 million aircraft plant that hasn't hired its first worker yet. Every smaller shop and contractor already on the ground here is going to compete with that benefits package, and the 2026 county numbers say a fixed monthly ICHRA contribution can be a real answer, not a consolation prize.
Mike MooreHow an ICHRA (now also called CHOICE) actually works
Before the Clark County numbers mean anything, it helps to be precise about what's being compared.
An ICHRA is an employer-funded health reimbursement arrangement created by a 2019 final rule from the IRS and Treasury, the Department of Labor, and HHS, published in the Federal Register on June 20, 2019, applicable to plan years beginning on or after January 1, 2020. Instead of choosing one group health plan for everyone, the employer sets a fixed monthly reimbursement amount, and each employee uses that money to buy an individual-market plan of their own choosing, then submits proof of coverage (called substantiation) to get reimbursed tax-free. The employer isn't picking a plan for a workforce of households with different doctors and different needs; the employer is funding a budget, and the employee is doing the shopping.
Worth naming directly: as of this article's publish date, HealthCare.gov's own page on this arrangement is titled "CHOICE Arrangements," and states plainly that CHOICE Arrangements are "formerly known as the Individual Coverage Health Reimbursement Arrangements, or ICHRAs." That's an administrative renaming on federal consumer-facing pages, not a change to the 2019 final rule or to any compliance requirement described in this article. We use "ICHRA" throughout this site, since that's still the term used in the regulations themselves.
The comparison behind every number in this article rests on two specific prices for a given rating geography. The individual-market benchmark premium is the second-lowest- cost silver-level plan available to a representative 40-year-old enrollee. "Silver" is one of four ACA metal levels (bronze, silver, gold, platinum) describing how costs split between premium and out-of-pocket spending, not the quality of care. This is the same benchmark the federal government uses to calculate premium tax credits, which is why it's a defensible number to build a comparison on rather than one insurer's list price. The small-group benchmark premium is the equivalent figure built from comparable small-group plan filings for the same geography. When the individual benchmark is lower, the county "qualifies," and the gap between the two is the estimated per-employee savings if the employer funds ICHRA at that benchmark level.
Two more terms matter once an employer is actually deciding whether to switch. The affordability safe harbor is the test that decides whether the ICHRA offer counts as "affordable" under IRS rules — for plan years beginning in 2026 that test runs against a Required Contribution Percentage of 9.96% of household income (IRS Rev. Proc. 2025-25), rising to 10.22% for plan years beginning in 2027 (IRS Rev. Proc. 2026-26). Get the contribution amount wrong relative to that threshold and an ALE (applicable large employer, generally 50 or more full-time-equivalent employees) can trigger an employer-mandate penalty. Most Clark County machine shops, fabricators and small contractors, running well under 50 employees, sit comfortably under that threshold, though a growing supplier positioning itself near the AirPark Ohio site should model it before crossing 50 heads.
Clark County's rate spread, in dollars
Here is the actual 2026 benchmark comparison for Clark County, the county whose seat is Springfield, Ohio. The individual-market benchmark premium is $597.71 a month. The small-group benchmark premium, built from comparable small-group plan filings for the same geography, is $1432.18 a month. That's a gap of $834.47 a month, or $10,014 a year, per employee, an estimated 58.3% in favor of the individual market.
Put next to the rest of the I-70 corridor, Clark's percentage ties Montgomery County (Dayton), Greene County, Miami County and Champaign County exactly, at 58.3%. Because all five matching counties share the exact same benchmark prices, the per-employee dollar savings figure, $10,014 a year, is also identical across every one of them — a rare case on this site where five neighboring geographies genuinely do share one answer, not just a similar one.
Ohio's group participation rule, and why there's no state-set ceiling
Small-group health insurance isn't sold to individual employees one at a time; it's underwritten as a pool, and a carrier can require a minimum share of a company's eligible employees to actually enroll before it will issue the policy at all. Ohio law defines this mechanic in Ohio Revised Code § 3924.03(E)(1), which states that "'group participation rule' means a requirement relating to the minimum number of employees or dependents that must be enrolled in relation to a specified percentage or number of eligible individuals or employees of an employer." The same subsection permits a small-group carrier to establish such a rule "as allowed under the law of this state," but the statute itself does not cap the percentage a carrier is allowed to require.
In practice, that means a Clark County employer shopping small-group coverage may see a different minimum-participation requirement from one carrier to the next, and that requirement isn't published anywhere in one place the way a statutory cap would be; it has to be confirmed plan by plan. A 15-person machine shop with a couple of part-timers, a new hire still inside a waiting period, or an employee covered elsewhere can end up short of whatever bar a given carrier happens to set, even though every one of those employees technically has coverage somewhere.
An ICHRA (or CHOICE Arrangement, per HealthCare.gov's current naming) sidesteps the mechanic entirely when it's the only benefit offered. Per HealthCare.gov, there is no participation-percentage requirement at all in that case. A minimum class size only applies when an employer offers a CHOICE Arrangement to one employee class while also offering a traditional group plan to a different class: 10 employees for employers with fewer than 100 total employees, 10% of the total workforce for employers with 100 to 200 employees, and 20 employees for employers with more than 200. Those class-size rules exist to keep the two benefit types properly separated when both are in use; they don't apply at all to an employer offering only a CHOICE Arrangement, which describes most Clark County small businesses.
If a group quote already fell through on participation
If you've already tried to set up small-group coverage in Clark County and a carrier's participation requirement blocked the quote, that's a specific, common signal that an ICHRA is worth pricing out next, since the mechanic that blocked you doesn't apply to it when it's the only benefit you offer.
A worked example for a Clark County employer
Here's what the Clark County numbers look like applied to a real headcount. Assume a 16-employee Clark County company — a machine shop off U.S. 40, a specialty fabricator near AirPark Ohio, or a small contracting firm serving Springfield and New Carlisle — currently renewing a small-group plan priced at this year's Clark County benchmark.
Here's the math
The 2026 small-group benchmark in Clark County is $1432.18 a month per employee, or $17186.16 a year. The 2026 individual-market benchmark is $597.71 a month, or $7172.52 a year. The difference is $10,014 a year per employee. For a 16-person company, funding ICHRA contributions at the benchmark level instead of renewing small group works out to an estimated $160,218 a year in aggregate estimated savings.
This is illustrative math built from real 2026 county rate data and a hypothetical headcount. It is not a quote, and it assumes the employer sets the ICHRA contribution at the benchmark level, which is a design choice, not a requirement. Your actual number depends on your employees' ages, exact home counties, and the plans they choose once they're shopping with their own budget.
The same arithmetic scales down cleanly to a smaller case: a 6-person specialty fabrication shop in Springfield that never seriously priced group coverage because the owner assumed a business that small couldn't offer anything worth having. At the $ 597.71 individual benchmark, funding an ICHRA for all six employees costs about $3586 a month in total contributions — a real, tax-free benefit offered to every eligible employee, since there's no enrollment percentage to clear and no group underwriting to qualify for.
At the other end of the size range, a growing supplier chasing work tied to the Electra buildout and crossing 50 employees moves into ALE territory under the employer mandate, which changes the calculus without changing the underlying county math. The same benchmark comparison applies, but an ALE has to run the affordability safe-harbor test — against the 9.96% threshold for 2026 or 10.22% for 2027 — carefully for every employee class, since an ICHRA offer judged "unaffordable" for even a handful of lower-paid employees can trigger a penalty. That's not a reason to avoid ICHRA at that size; it's a reason to model the affordability test before setting a contribution amount, which our eligibility guide walks through in detail.
Setting up an ICHRA in Clark County
Ohio doesn't layer a statewide participation cap on top of the federal framework the way some states do, but the underlying setup sequence is the same one that applies everywhere. What determines whether a Clark County rollout goes smoothly:
- Pull your census by county, not by office address. A business headquartered in Springfield with staff commuting in from Dayton (Montgomery County), Xenia (Greene County), or Troy (Miami County) will see the same benchmark numbers, since all three share the same rate area — but staff commuting from counties outside that cluster see a different percentage, so check each employee's home county rather than assuming the Clark number applies to everyone.
- Decide how you'll define your eligible class. An hours-based eligible class (for example, employees regularly scheduled 30+ hours a week) is a legitimate way to extend a benefit to full-time shop or administrative staff without promising it to every part-time or seasonal hire.
- Check whether you're offering ICHRA alone or alongside a group plan. That decision determines whether any class-size minimum applies at all.
- Model affordability before you set a contribution. The reimbursement level decides whether an employee keeps or waives premium tax credit eligibility, against the 9.96% (2026) or 10.22% (2027) Required Contribution Percentage.
- Send the required notice on time. Eligible employees need written notice at least 90 days before the plan year starts, with specific required content.
- Budget for onboarding support. Shop-floor and administrative staff who've never shopped Ohio's individual marketplace need guidance once, at enrollment, not a lengthy annual open-enrollment process.
See our full ICHRA setup timeline for the detailed rollout plan, including the exact notice content requirements, and our eligibility guide for the affordability test itself.
If your employer just offered you an ICHRA
This guide is written for the employer side of the decision, but if you're a Clark County employee who was just told your benefit is changing, the short version is: you'll get a fixed monthly amount and shop for your own plan on the individual marketplace instead of picking from your employer's group menu. Our guide for employees walks through what to expect.
The honest limits of this data
A strong county average is not a guarantee for your specific workforce
- A benchmark comparison is not your actual renewal. The $1432.18 Clark County figure is a small-group benchmark built from filed rates, not your specific carrier's quote for your specific group.
- Matching Montgomery, Greene, Miami and Champaign counties today doesn't guarantee matching tomorrow. Rate areas are federally defined geographies, and a carrier can still price differently within the same area from one plan year to the next; recheck the comparison at every renewal rather than assuming the five-county match holds for 2027.
- Older or higher-risk workforces change the math. Individual-market premiums are age-rated more steeply in some geographies than small-group premiums, which can narrow real-world savings for an older ownership or management team below the benchmark figure.
- Carrier participation rules still apply if you keep a group plan alongside ICHRA. Ohio's lack of a statutory cap means a carrier's own bar could be higher than you expect; confirm it directly with any carrier you're still comparing against.
- Rates move every plan year. A carrier entering or leaving this geography can shift the comparison for 2027; recheck before every renewal, not just once. Ohio's individual market already moved 19.8% for 2026 per healthinsurance.org, so don't assume this year's spread holds next year.
- This dataset relies on one rate-data provider for the county comparison. The 58.3% figure itself is drawn from a single source, Ideon, cross-verified against CMS public-use marketplace files rather than a second independent rate-data vendor; treat it as a strong estimate for screening, not a substitute for your own carrier quotes.
- Waiving the premium tax credit is part of the deal. An employee whose ICHRA offer is deemed affordable generally cannot also claim a marketplace subsidy for that month. Model both sides before assuming the reimbursement is pure upside.
How these numbers are calculated
Every county figure in this article comes from the same dataset that powers our savings map, not a survey or a sales estimate. For each county, we compare a 2026 individual-market benchmark premium — the second-lowest-cost silver plan available to a representative enrollee, the same benchmark the federal government uses to calculate premium tax credits — against a small-group benchmark premium built from comparable small-group plan filings for that geography. Both figures come from Ideon, a licensed insurance rate-data provider, and are cross-verified against CMS public-use marketplace files before publication. A county appears in our location-page dataset when the individual benchmark sits below the small-group benchmark by at least $100 a month; the percentage and dollar figures in this article are the gap between those two numbers, expressed as an annual per-employee figure at 12 times the monthly difference.
Clark County's population figure (136K) comes from the same underlying county dataset used across the site. The employment figures in the economy section — 38,739 total private jobs across 2,418 establishments at $52,484 average pay, 6,345 manufacturing jobs across 148 establishments at $66,572 average pay, 6,724 health care and social assistance jobs across 318 establishments at $58,687 average pay, 4,653 retail-trade jobs across 356 establishments at $34,537 average pay, 4,743 accommodation-and-food-services jobs across 255 establishments at $21,067 average pay, and 6,221 local-government jobs across 119 establishments at $55,631 average pay — come from the U.S. Bureau of Labor Statistics' Quarterly Census of Employment and Wages, Clark County, Ohio (area code 39023), 2025 annual averages, a separate federal dataset from our own county premium comparison, fetched directly from BLS's public CEW API. The total covered (all ownerships) figure of 45,578 jobs across 2,566 establishments comes from the same BLS source. The Electra facility's investment figure ($850 million), job count (1,975), site size (96 acres) and location come from JobsOhio's own July 21, 2026 announcement. The Konecranes and Fire Manufacturing Innovations details come from the Greater Springfield Chamber of Commerce's published manufacturing feature. The Ohio participation-rule citation comes directly from the text of Ohio Revised Code § 3924.03(E)(1), as published by the Ohio Legislative Service Commission at codes.ohio.gov. The national small-group premium figure (Peterson-KFF), the Ohio individual-market figures (healthinsurance.org), the IRS affordability percentages (Rev. Proc. 2025-25 and 2026-26), and the HealthCare.gov participation and naming details each come from separately published, independent sources, described and cited where they appear. We've kept these data sources clearly separate throughout this article rather than blending them into one number.
Three limitations are worth stating plainly. First, benchmark premiums are built around a representative enrollee profile, so an unusually young or unusually old workforce will see a different real-world spread than the county figure implies. Second, these are benchmark plans, not every plan on the market; an employee who chooses a richer or leaner plan than the benchmark will see a different premium, though the relative spread tends to hold directionally. Third, rates are filed and refreshed annually, so a geography that qualifies for 2026, and even a five-county match like Clark, Montgomery, Greene, Miami and Champaign, is not guaranteed to hold its current percentage, or stay matched, for 2027 if a carrier enters or exits that rate area.
Questions Clark County employers actually ask
Does ICHRA beat small-group insurance in Springfield, Ohio?
Yes. Springfield is the county seat of Clark County, and Clark's 2026 individual-market benchmark premium runs an estimated 58.3% below the small-group benchmark, about $10,014 per employee per year. That's an estimate built from public and industry rate data, not a quote. The percentage ranks 36 of Ohio's 88 counties, and the dollar gap ranks 35 of 88.
Why does Clark County show the exact same number as Montgomery County (Dayton)?
Both counties sit in the same federal rate area, a geography carriers use to file one benchmark price for a whole cluster of counties at once, the same pattern our earlier guide to Ohio's rating areas describes for a different nine-county cluster elsewhere in the state. Clark's 2026 individual benchmark ($597.71) and small-group benchmark ($1432.18) match 7 other Ohio counties to the cent, including Montgomery County (Dayton), Greene County, Miami County and Champaign County. A Springfield employer with staff commuting in from any of those counties sees the identical county-level math.
How much can a Clark County employer expect to save?
Using 2026 benchmark data, the estimated gap in Clark County is $834.47 a month, or $10,014 a year, per employee. For a 16-employee company, that's roughly $160,218 a year in aggregate estimated savings if the employer funds ICHRA contributions at the benchmark level instead of renewing small group. This is illustrative math from public rate data, not a projection of what any specific employer will actually pay.
Why did my 2026 small-group renewal come in higher than expected?
Nationally, small-group insurers filed a median proposed premium increase of 11% for the 2026 plan year across 318 insurers in all 50 states and the District of Columbia, according to the Peterson-KFF Health System Tracker brief published September 24, 2025; about two-thirds of those filings landed between 5% and 15%, and roughly 10% proposed 20% or more. On the individual-market side, healthinsurance.org's Ohio marketplace guide (updated August 23, 2026) puts the average unsubsidized rate increase at 19.8% across the 11 insurers offering marketplace plans in Ohio for 2026, with the average premium enrollees actually pay, across all enrollees including those with no subsidy, running about $233 a month.
Does a small Clark County employer have to hit a participation minimum to offer ICHRA?
No, not if ICHRA is the only benefit offered. Ohio Revised Code § 3924.03(E)(1) defines a "group participation rule" as "a requirement relating to the minimum number of employees or dependents that must be enrolled in relation to a specified percentage or number of eligible individuals or employees of an employer," and lets small-group carriers set their own bar; the statute does not cap that percentage statewide. Per HealthCare.gov's current CHOICE Arrangement guidance, there is no participation-percentage requirement at all when an employer offers the arrangement on its own, which sidesteps carrier-by-carrier variation entirely.
What happens to my employees' premium tax credit if I switch to ICHRA?
An employee who is offered an affordable ICHRA generally becomes ineligible for a premium tax credit for any month that offer applies, whether or not they accept it. Affordability is measured against the IRS's Required Contribution Percentage, which is 9.96% of household income for plan years beginning in 2026 (Rev. Proc. 2025-25) and rises to 10.22% for plan years beginning in 2027 (Rev. Proc. 2026-26). Model that test before you set a contribution amount for any Clark County employee currently receiving marketplace subsidies.
Does the new Electra aircraft plant change the math for smaller Clark County employers?
Electra's planned $850 million, 1,975-job production facility at AirPark Ohio, next to Springfield-Beckley Municipal Airport, announced by JobsOhio and Governor DeWine on July 21, 2026, will eventually bring a large single employer's benefits package into the county's labor market. That raises the bar smaller Clark County employers compete against for workers, which is exactly the scenario an ICHRA budget is built to answer: a 10- or 20-person supplier or service business can't match a $850 million employer's group plan, but it can still offer a real, tax-free monthly contribution that current benchmark pricing stretches further here than in most Ohio counties.
Is ICHRA now called something else? I keep seeing "CHOICE Arrangement."
HealthCare.gov now labels the same arrangement a "CHOICE Arrangement," stating it is "formerly known as the Individual Coverage Health Reimbursement Arrangements, or ICHRAs." That is an administrative naming update on federal consumer-education pages, not a change to the underlying 2019 federal rule or the compliance requirements it sets. We use "ICHRA" throughout this site because it is still the term used in the regulations themselves; the two names describe the identical arrangement.
Sources
- Ohio Legislative Service Commission, Ohio Revised Code § 3924.03(E)(1) — definition of "group participation rule" for small-employer health benefit plans
- Peterson-KFF Health System Tracker, "How Much and Why Premiums Are Going Up for Small Businesses in 2026" (Sept. 24, 2025)
- healthinsurance.org, "Ohio Health Insurance Marketplace" guide (updated Aug. 23, 2026)
- IRS Revenue Procedure 2025-25 — Required Contribution Percentage, plan years beginning in 2026 (9.96%)
- IRS Revenue Procedure 2026-26 — Required Contribution Percentage, plan years beginning in 2027 (10.22%)
- 84 Fed. Reg. 28888 — ICHRA final rule, Departments of the Treasury/IRS, Labor, and Health and Human Services (June 20, 2019)
- HealthCare.gov, "CHOICE Arrangements" — participation and class-size rules; naming update from "Individual Coverage HRA"
- U.S. Bureau of Labor Statistics, Quarterly Census of Employment and Wages — Clark County, Ohio (area code 39023), 2025 annual averages
- JobsOhio, "Electra to Usher in the Next Era of Aviation with Advanced Production Facility in Springfield, Ohio" (July 21, 2026)
- Greater Springfield Chamber of Commerce, "We're Celebrating Manufacturing Businesses Made in Springfield"
- County-level premium comparison:
src/data/qualified_counties.json, 2026 plan year (Ideon rate data, cross-verified against CMS public-use marketplace files)