ICHRA Is Now the CHOICE Arrangement: 2026 Federal Rename
CMS and SBA renamed ICHRA the CHOICE Arrangement in September 2026. See what changed, what stayed the same, and this year's sourced county data.
The short version
- Starting in September 2026, CMS and the Small Business Administration began calling ICHRA the "CHOICE Arrangement" in their own outreach material, including a September 14, 2026 press release and HealthCare.gov's employer page.
- This is a naming change made by the agencies, not a change to the underlying law. The arrangement still runs on the 2019 IRS/DOL/HHS final rule that has applied since plan year 2020.
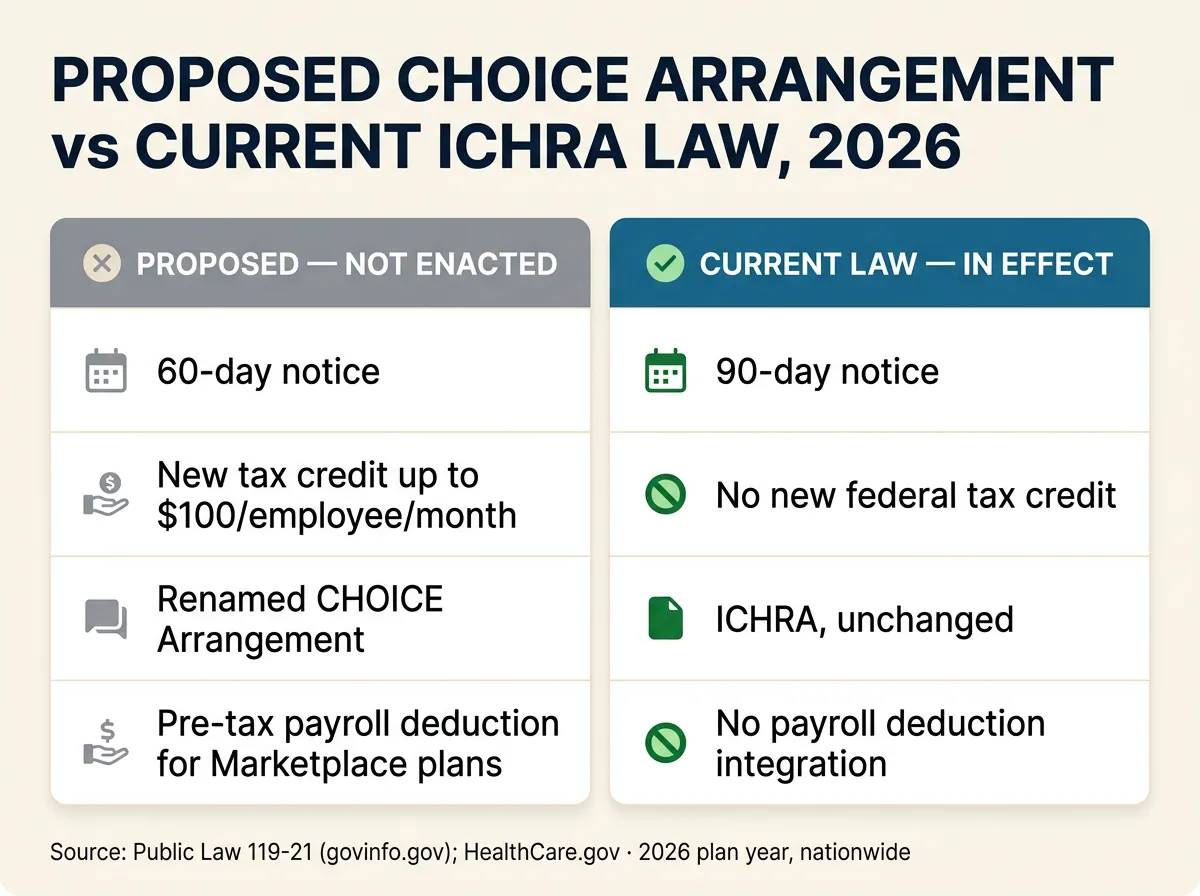
- A separate, unrelated set of congressional bills also used the name "CHOICE Arrangement" in 2025, but proposed to change actual rules (a shorter notice period, a new tax credit). Those bills have not passed the Senate.
- Nothing about your 2026 compliance obligations, notice timing, or affordability math changed because of any of this.
Has ICHRA really been renamed "CHOICE Arrangement"?
In one sense, yes, as of September 2026. If your benefits vendor, a broker's newsletter, or a LinkedIn post recently told you that ICHRA (Individual Coverage Health Reimbursement Arrangement, an employer-set monthly budget employees use tax-free to buy their own individual health insurance) now goes by "CHOICE Arrangement," that part is accurate. We checked HealthCare.gov's small-business page for this arrangement directly this session: it is currently titled "CHOICE Arrangements." CMS published a press release on September 14, 2026 using the same name, and the Small Business Administration's own site describes "CHOICE Arrangements" as the current federal term, noting plainly that they "were previously known as Individual Coverage Health Reimbursement Arrangements (ICHRAs)."
In the sense that matters for compliance, nothing changed. The rename did not arrive through a new law. It arrived through the executive branch choosing new language for an existing rule. That distinction is the entire point of this article, because it is easy to read "renamed" and assume a new set of requirements came with it. They did not.
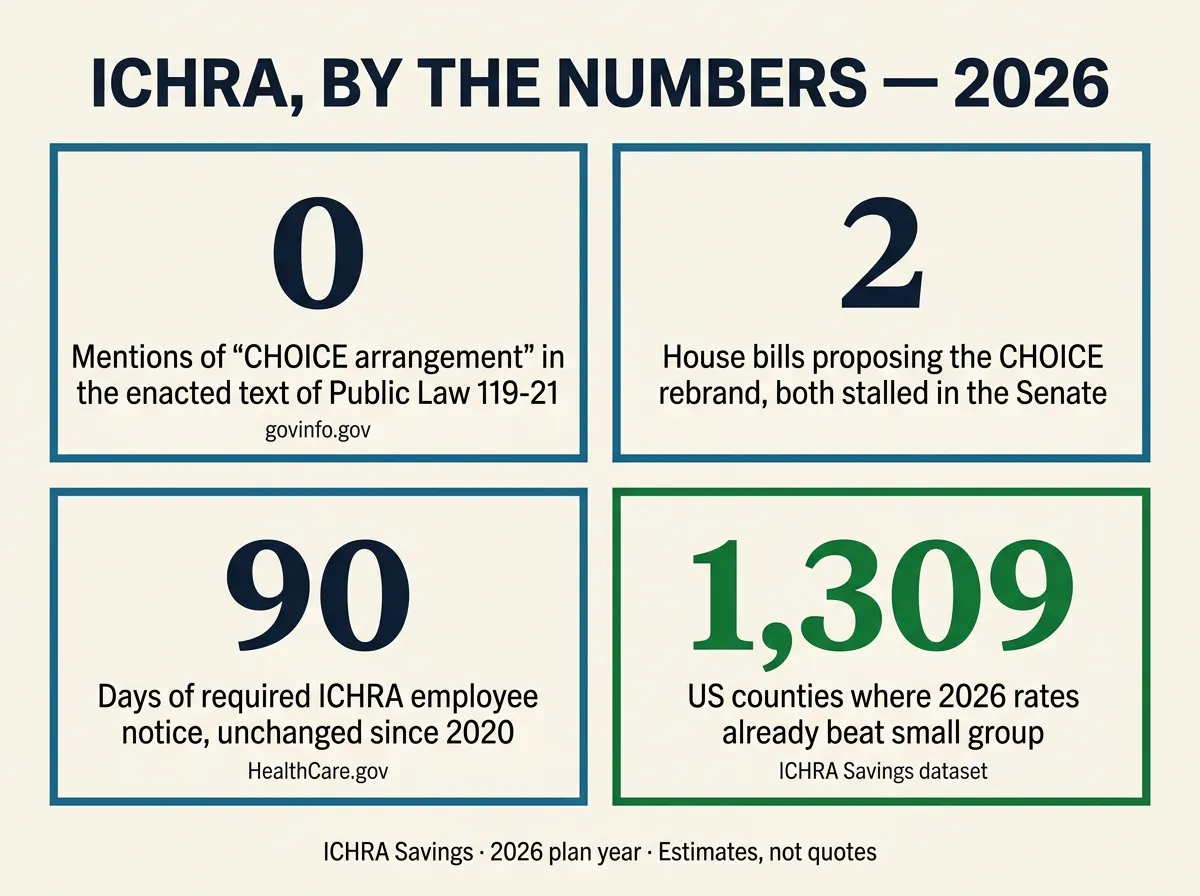
Sept. 14, 2026
CMS press release date naming the CHOICE Arrangement rebrand
2019
Year of the federal final rule that still governs the arrangement, unchanged
90
Days of required employee notice under current rules, unchanged
1,309
US counties where 2026 individual-market rates already beat small group
What CMS and SBA actually announced
The clearest primary record is a CMS press release, "CMS, SBA, and Georgia Recognize Innovative CHOICE Arrangements as Major Win for Small Businesses," dated September 14, 2026. CMS Administrator Dr. Mehmet Oz is quoted saying CHOICE Arrangements "let workers choose coverage that meets their unique healthcare needs" and that he is "excited to partner with Administrator Loeffler to promote this underused option." SBA Administrator Kelly Loeffler is quoted calling the arrangement a "win-win" in which "employers set a monthly contribution level, and employees pick the qualifying plan that suits their families." Georgia Insurance and Safety Fire Commissioner John F. King took part in the same event. Several industry outlets, including Becker's Payer Issues and PeopleKeep, separately reported an earlier announcement the week of September 3, 2026 in Indiana; we were not able to independently confirm that specific date from a primary federal source this session, so we are attributing it to that trade coverage rather than presenting it as independently verified.
What the release does not say is as important as what it does. It does not cite a new regulation, a new Federal Register notice, or a new statute. CMS's own material, including an "Employer Initiatives" page we checked this session, describes the change directly: "CHOICE Arrangements were previously known as Individual Coverage Health Reimbursement Arrangements (ICHRAs)," with no mention of a substantive rule change alongside it. That is consistent with how every outlet covering the announcement has framed it: a rebrand meant to make the option easier to understand and market, not a rewrite of the rule.
The full timeline, 2019 to 2026
Laid end to end, the sequence makes the "branding versus law" distinction easier to see than any single paragraph can. Two congressional bills carrying CHOICE language bracket a federal rule that has not moved since 2020, and the September 2026 rename slots in after both bills, not because of either one.
| Date | What happened |
|---|---|
| June 20, 2019 | IRS, DOL, and HHS publish the joint final rule creating ICHRA in the Federal Register (Doc. 2019-12571) |
| Jan. 1, 2020 | Final rule becomes applicable; the first ICHRA plan years begin under it |
| May 22, 2025 | House passes its reconciliation bill with CHOICE-branded provisions, a new tax credit, and a 60-day notice |
| July 4, 2025 | President signs Public Law 119-21; the enacted text contains no CHOICE or ICHRA provisions, per govinfo.gov |
| Dec. 17, 2025 | House passes H.R. 6703, the Lower Health Care Premiums for All Americans Act, reviving similar CHOICE language |
| Sept. 2026 | CMS and SBA begin using "CHOICE Arrangement" as their public name for ICHRA in outreach material and on HealthCare.gov |
| Sept. 14, 2026 | CMS press release, with SBA and Georgia, formally recognizes CHOICE Arrangements as a small-business option |
What the arrangement does, under either name
Whatever you call it, the mechanics have been the same since 2020. An employer sets a fixed monthly reimbursement budget, at any dollar amount it chooses, and each employee uses it to buy an individual health plan on the open market or through the ACA Marketplace, reimbursed tax-free. HealthCare.gov's current CHOICE Arrangement page states that "generally, employers of any size can offer" one, with no federal minimum or maximum contribution requirement, and that a written notice must go to current employees "90 days before the start of each plan year." That structure comes from a single source: a joint final rule from the IRS, the Department of Labor, and the Department of Health and Human Services, published in the Federal Register on June 20, 2019 (document 2019-12571), applicable to plan years beginning on or after January 1, 2020.
A few terms are worth pinning down, because both the branding change and the older legislative proposals reuse them. QSEHRA (Qualified Small Employer HRA) is a separate, older arrangement capped by a federal dollar limit and restricted to employers under 50 full-time- equivalent employees; this arrangement, under either name, has no such cap or size ceiling. The affordability safe harbor is the IRS test deciding whether a given employee's contribution counts as "affordable," which determines whether that employee keeps access to a premium tax credit for that month; HealthCare.gov puts the 2026 threshold at 9.96% of household income. An employee class is a group of workers defined by an IRS-permitted factor, such as full-time versus part-time status or work location, letting an employer offer different terms, or a group plan, to different segments of its workforce. None of these definitions moved in September 2026.
One clarification worth making explicitly, because the two arrangements are easy to mix up: the September 2026 rename applies only to ICHRA. QSEHRA, capped at $6,450 for self-only coverage and $13,100 for family coverage in 2026 under IRS Revenue Procedure 2025-32 (see our full ICHRA vs. QSEHRA comparison for the complete numbers) and restricted to employers under 50 full-time-equivalent employees, was created directly by Congress rather than by the 2019 regulatory rule, so CMS and SBA renaming ICHRA has no bearing on it. If your business runs a QSEHRA, nothing in this article changes what you call it or how you administer it.
If you are an employee rather than an employer, and your company's HR team recently told you your benefit is now called a "CHOICE Arrangement" instead of an ICHRA, the short version is the same one this whole article is making: it is the same money, under the same rules, with a different label. Your reimbursement process, the individual plan you already picked or are choosing, and your employer's contribution amount are unaffected. Our guide for employees walks through how to actually use the benefit, regardless of which name is on your HR portal.
Two different "CHOICE" stories, and why they get confused
There are genuinely two separate "CHOICE" stories running in parallel, and most of the confusion online comes from writers conflating them.
The first is legislative. A House-passed 2025 reconciliation bill, and later a standalone bill, H.R. 6703 (the Lower Health Care Premiums for All Americans Act, passed by the House on December 17, 2025), each proposed writing a "CHOICE Arrangement" directly into the tax code, with real rule changes attached: a shortened 60-day notice period, a temporary small-employer tax credit, and the ability to route pre-tax payroll deductions toward Marketplace premiums. We pulled the full, enacted text of Public Law 119-21 (the reconciliation act, signed July 4, 2025) directly from govinfo.gov this session and searched it for "CHOICE arrangement," "custom health option," and "health reimbursement arrangement." None of those phrases appear anywhere in the document. The Senate removed that language before the bill became law. H.R. 6703 passed the House in December 2025; we could not independently confirm its current Senate status this session because congress.gov and GovTrack both blocked our automated access, so treat any claim about that bill's status, including in older coverage, as something to verify directly on Congress.gov before relying on it.
The second is administrative, and it is the one that actually happened: CMS and SBA adopting "CHOICE Arrangement" as their preferred name for the existing ICHRA rule in outreach material, starting around September 2026, without waiting for either bill to pass. An agency can rename a program it already administers without new legislation; what it cannot do on its own is change the program's legal requirements, which is why the notice period, the affordability formula, and the class rules are all still the ones from the 2019 rule.
The one-sentence way to keep this straight
The agencies changed what they call it. Congress has not yet changed what it is. Both are true at the same time, and a vendor or article that blends the two into "ICHRA has new rules now" is wrong regardless of which "CHOICE" story it thinks it is describing.
Branding change versus law change, side by side
Here is every material fact lined up against what it does, and does not, require you to do.
| Dimension | What happened | Bottom line |
|---|---|---|
| What actually happened, Sept. 2026 | CMS and SBA began using "CHOICE Arrangement" as the public-facing name for ICHRA in their own material | An administrative branding choice by the executive branch, not a new statute |
| Governing rule | Same 2019 final rule (26 CFR Part 1; 29 CFR Parts 2510, 2590; 45 CFR Parts 144, 146, 147) | Unchanged; still the operative law for 2026 |
| Employee notice period | 90 days before the plan year, per HealthCare.gov's current CHOICE Arrangement page | Unchanged from the pre-rename ICHRA notice rule |
| Affordability test | 9.96% of household income for 2026, per HealthCare.gov | Same IRS-linked calculation as before the rename |
| The separate legislative "CHOICE Arrangement" bills | Would add a small-employer tax credit, a 60-day notice, and pre-tax payroll deduction for Marketplace premiums | Proposed only; not signed into law as of publish |
| Do you need to change anything | No new paperwork, no new notice, no new tax filing category | Keep operating under the rules you already follow |
Why this is more confusing than a normal rebrand
Most product rebrands do not have a second, unrelated legislative effort using the exact same new name. This one does. A search for "ICHRA CHOICE Arrangement" right now returns a mix of: accurate, current reporting on the September 2026 agency branding; older, once-accurate reporting on the 2025 legislative proposal that has not become law; and content that blends the two into a single, wrong claim that "ICHRA rules changed in 2026." All three read similarly once a search result strips away the publish date and the writer's sourcing.
The practical fix is the same one we used to write this article: ask whether a claim points to an actual enacted statute or an actual government press release, or just to another article's summary of one. HealthCare.gov's own page and the CMS press release are both linked in our sources below, so you do not have to take our word for any of this.
What this means for vendors, brokers, and your plan documents
If you administer your arrangement through a third-party administrator, you may start seeing the CHOICE Arrangement name show up in that vendor's portal, employee-facing emails, or marketing material over the next few months. That is a cosmetic update on the vendor's end, not a sign that your contract or plan document needs to be reissued. A plan document, adoption agreement, or Section 125 wrap document that references "ICHRA" by name remains a correct, enforceable description of what you offer; nothing in the September 2026 announcement requires reissuing existing paperwork under a new name.
Where this is worth a direct question to your administrator or broker: if anyone tells you the rename comes bundled with a new feature, a new tax credit, or a shortened notice period, ask them to point to the specific federal rule or statute behind it. As of this article's publish date, the features attached to the name in the 2025 legislative proposals, the small-employer tax credit, the 60-day notice, and the pre-tax payroll deduction for Marketplace premiums, are not part of what CMS and SBA rolled out in September 2026. A vendor conflating "we renamed our product page" with "the IRS changed the rule" is a sign to ask more questions, not a compliance requirement to act on.
Why an agency can rename a program without Congress
It is worth explaining why this is possible at all, because it is not a loophole; it is how federal agencies routinely operate. CMS and the SBA administer ICHRA under authority Congress already gave them in the 2019 final rule, so the wording they use to describe it in press releases, web pages, and consumer-facing tools is an agency communications decision, not a regulatory one. The same authority that lets an agency choose plain-language names for programs it already runs, rather than requiring the public to learn a technical acronym, is why federal websites regularly use shorthand names that do not appear anywhere in the statute or regulation they describe. What an agency cannot do on its own is change who is eligible, shorten a statutory or regulatory notice period, create a new tax credit, or authorize a payroll mechanism the rule does not currently permit. Those changes require either a new final rule through formal rulemaking or a new statute from Congress, which is exactly the higher bar the 2025 CHOICE bills have not yet cleared.
What to actually do about your 2026 plan
A short, practical list, regardless of which name your paperwork uses:
- Keep running your plan, or set one up, under the rules you already know. The class structure, the 90-day notice, the affordability test, and the reimbursement mechanics have not moved.
- Don't let a vendor sell you a "new CHOICE feature." The pre-tax payroll deduction for Marketplace premiums, the shortened notice window, and the small-employer tax credit described in the 2025 congressional proposals are still not operative law. An administrator offering any of them as a current feature is describing a bill, not a rule.
- Use either name in your own communications. "ICHRA" and "CHOICE Arrangement" now both point to the same thing in federal materials. Pick the one your employees will recognize; neither is more legally correct than the other at this point.
- Watch the number that actually moves every year: your county's rate spread. Individual-market and small-group premiums are re-filed annually, independent of what any agency calls the arrangement, and that is what decides whether it saves your business money this year.
The question worth answering this week
Not "did the rules change" (they did not), but "does the math work for my counties right now, under the rules that already exist." Check your specific counties on the savings map. It takes about ten seconds per county and uses this year's actual rate data, not a press release.
A worked example, using rules that have not moved
To make the "the name changed, the math didn't" point concrete, here is what the arrangement still
looks like today, using real county data from the ICHRA Savings qualified-counties dataset for the
2026 plan year, generated this session directly from src/data/qualified_counties.json.
The dataset currently lists 1,309 counties,
across 32 states, where the
individual-market benchmark premium already runs below the small-group benchmark for 2026.
How 1,309 qualifying counties break down by savings size, 2026
Generated this session from the ICHRA Savings qualified-counties dataset. None of this shifts based on what the arrangement is called.
2026 plan year. Estimates from benchmark premiums, not quotes or a guarantee of savings.
Here's the math, unaffected by the September 2026 rename
In Erie County, Ohio, the 2026 individual-market benchmark premium is $544.80 a month against a small-group benchmark of $1473.56 a month, an estimated 63% spread, or $11,145 a year per employee. It is one of several Ohio counties tied for the highest spread in the national dataset; our Sandusky, Ohio breakdown covers this same county in more depth. In Marin County, California, the same comparison shows a much thinner 0.1% spread, about $5 a year per employee, still technically "qualifying," but not a number that changes a hiring decision. The national median across all 1,309 qualifying counties, using Bath County, Virginia as the closest example to that midpoint, sits around 19.2%, or $1,663 a year per employee.
None of these three figures moved because of anything in this article, or because of anything CMS or the SBA called the arrangement in September. They come from this year's actual, filed insurance rates, refreshed for the 2026 plan year, and they will move again next year regardless of the name on the paperwork. That is the number worth tracking closely. The name is not.
Scale that to a small employer with people in more than one place, which is where most real decisions actually get made. Take a 10-person company split evenly between Erie County, Ohio and Marin County, California, five employees each. At benchmark-level contributions, the Ohio half is worth an estimated 5 × $11,145 = $55,726 a year in aggregate savings; the California half, at a much thinner 0.1% spread, adds roughly $25. Combined, that is about $55,750 a year across the whole company, almost entirely driven by the Ohio side. A national average across both counties would flatten that into one misleading number; the two-county math is the only version worth taking to a hiring or budget decision. If your team spans Ohio and Georgia instead, our Ohio vs. Georgia comparison walks through why those two states land so differently.
The agencies changed the label in September 2026. They did not change the notice period, the affordability math, or your county's numbers. Check those, not the name on the folder.
Mike MooreIf you haven't worked through the general decision yet, our employer decision guide walks through the framework independent of any of the naming noise covered here, and our step-by-step setup timeline covers the current 90-day notice requirement and every other rule you would actually follow to launch one this year. For the separate annual number that does change every year on schedule, see our piece on the 2027 affordability percentage.
Questions employers are asking right now
Has ICHRA been renamed "CHOICE Arrangement"?
As federal branding, yes. CMS and the Small Business Administration began calling it the CHOICE Arrangement in official material starting in September 2026, and HealthCare.gov's own page for employers now carries that title. As a matter of law, no statute rewrote the arrangement. It still runs on the same 2019 IRS/DOL/HHS final rule, effective since plan year 2020. Two separate bills that would have written a "CHOICE Arrangement" into the tax code, with different rules attached, have not passed the Senate.
So is this the same "CHOICE" that Congress tried to pass in 2025?
Same name, different mechanism, and that is the part causing confusion. The 2025 congressional proposals (in the House-passed reconciliation bill and later in H.R. 6703) would have changed the rules: a shorter notice period, a new tax credit, pre-tax payroll deduction for Marketplace premiums. Neither bill has been signed into law. What CMS and SBA did in September 2026 is different: they started using "CHOICE Arrangement" as the plain-English name for the existing ICHRA rule, without changing any of the rule's mechanics.
Do I need to redo my plan documents, employee notice, or paperwork because of the rename?
No. Nothing in your plan design, your 90-day employee notice, your affordability calculation, or your reimbursement process changes because a federal agency now prefers a different name in its own outreach material. Formal plan documents, payroll setups, and past employee communications that say "ICHRA" remain accurate and valid.
What does CHOICE actually stand for?
The name traces back to the 2025 congressional proposal, where House committee documents defined it as "Custom Health Option and Individual Care Expense." CMS's own September 2026 material uses "CHOICE Arrangement" as the name but does not spell out the acronym in the pages we could access this session, so we are attributing that specific expansion to the original legislative text rather than to CMS directly.
Who announced this, and where?
A CMS press release dated September 14, 2026, titled "CMS, SBA, and Georgia Recognize Innovative CHOICE Arrangements as Major Win for Small Businesses," quotes CMS Administrator Dr. Mehmet Oz and SBA Administrator Kelly Loeffler, with Georgia Insurance and Safety Fire Commissioner John F. King participating. Multiple industry outlets reported an earlier announcement event the week of September 3, 2026; we could not independently confirm that specific date from a primary federal source this session, so we are attributing it to that trade coverage rather than asserting it as verified.
Does the 2026 affordability percentage change under the new name?
No. HealthCare.gov states the 2026 figure at 9.96% of household income, calculated the same way it was before the name change: an arrangement is affordable if the employee's cost for the lowest-cost self-only Silver plan, after your contribution, is under that share of income. See our separate article on the 2027 percentage for next year's number.
Should I wait to set up an ICHRA (or CHOICE Arrangement) until the naming settles down?
There is no compliance reason to wait. The class structure, the 90-day notice, the affordability test, and the reimbursement mechanics are unchanged. A vendor telling you to hold off because "the rules are in flux" is describing a branding announcement, not a regulatory one.
Where can I check this myself instead of taking a blog post's word for it?
Read HealthCare.gov's own page, currently titled "CHOICE Arrangements," and the CMS press release linked in our sources below. For the legislative history, Congress.gov's bill tracker covers H.R. 6703; we could not fetch it directly this session, so verify its current status there rather than relying on any article, including this one, for real-time bill status.
Sources
- CMS Newsroom, "CMS, SBA, and Georgia Recognize Innovative CHOICE Arrangements as Major Win for Small Businesses" (Sept. 14, 2026)
- HealthCare.gov, "CHOICE Arrangements" (fetched this session)
- U.S. Small Business Administration, "Healthcare options for small businesses: CHOICE Arrangements"
- CMS, "Employer Initiatives"
- U.S. Government Publishing Office, Public Law 119-21, full enacted text (signed July 4, 2025)
- Federal Register, "Health Reimbursement Arrangements and Other Account-Based Group Health Plans," Doc. 2019-12571 (June 20, 2019)
- Health Affairs Forefront, "The House Republican Budget Reconciliation Legislation: Unpacking The ICHRA And HSA Changes" (May 22, 2025)
- IRS, Revenue Procedure 2025-32, Section 4.63 (2026 QSEHRA reimbursement limits)
- Office of Rep. Tim Moore, press release on the H.R. 6703 House vote (Dec. 17, 2025)
- Becker's Payer Issues, "CMS rebrands ICHRA" (trade coverage of the September 2026 announcement)
- ICHRA Savings qualified-counties dataset, 2026 plan year (
src/data/qualified_counties.json)